



PW Consulting: Automotive Blade Fuse Market to Reach $1.96B by 2032, CAGR 5.8%

Navigating the Automotive Blade Fuse Market: Strategic Intelligence for 2026 Decision-Making
The automotive electrical ecosystem is undergoing a structural transformation driven by electrification, advanced driver-assistance systems, and increasingly complex in-vehicle power architectures. At the foundation of these circuits lies a critical yet often overlooked component: the automotive blade fuse. As vehicle manufacturers and aftermarket suppliers navigate tightening reliability standards, fluctuating raw material costs, and shifting regional demand patterns, the need for precise, forward-looking market intelligence has never been more acute. Our latest Automotive Blade Fuse Market research delivers exactly that, translating historical trajectories and multi-year projections into actionable strategic frameworks for 2026 and beyond.
This analysis is designed specifically for executives, procurement leaders, product planners, and competitive intelligence teams who require more than headline figures. The study anchors its methodology in verified historical data spanning 2020 through 2025, then extends the analytical lens across a forecast period from 2026 to 2032. Over the historical window, the market demonstrated steady expansion, moving from approximately 0.99 billion USD in 2020 to 1.31 billion USD by 2025. The trajectory continues into the forecast horizon, with 2026 projections reaching 1.43 billion USD and sustained growth anticipated through 2032, when the market is expected to approach 1.96 billion USD. These figures reflect a compound annual growth rate of 5.8 percent, a pace that signals consistent demand expansion rather than speculative volatility.
Such macro-level momentum creates both opportunity and complexity. Growth is not uniformly distributed across product categories, application segments, or geographic corridors. Manufacturers must understand how pricing dynamics, regulatory compliance, supply chain localization, and vehicle architecture shifts interact to shape revenue pools. Our report dissects these intersections without overwhelming readers with fragmented statistics, instead presenting a structured narrative that clarifies where strategic focus will yield the highest return on investment.
What the Research Delivers: Operational Intelligence for Product, Pricing, and Portfolio Strategy
A market study is only as valuable as its applicability to real-world decision cycles. This report is built around operational utility. It moves beyond generic industry commentary to provide structured assessments that can be integrated directly into annual planning, sourcing evaluations, and competitive positioning exercises. Readers will encounter detailed evaluations of product architecture trends, including the continued dominance of blade-style configurations in contemporary vehicle electrical designs, alongside comparative insights into glass tube and other specialized fuse formats. The analysis examines how form factor preferences align with OEM specifications, aftermarket replacement cycles, and regional certification requirements.
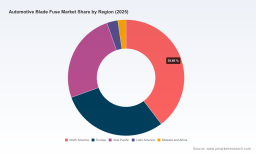
The research also maps the evolution of application-driven demand. Passenger vehicle platforms remain the primary consumption base, reflecting high production volumes and extensive electrical component integration. Commercial vehicle segments introduce distinct load profiles, environmental durability expectations, and maintenance intervals that influence fuse selection and procurement frequency. Other application corridors, including specialty mobility platforms and emerging aftermarket service networks, are evaluated for their incremental contribution to overall market expansion. By contextualizing these segments within broader vehicle production forecasts and fleet turnover cycles, the study enables stakeholders to anticipate demand shifts rather than react to them.
Pricing architecture and value chain dynamics receive equal attention. The report explores how automotive-grade manufacturing standards, testing protocols, and certification pathways influence cost structures and competitive positioning. It examines the interplay between volume-driven OEM supply agreements and the margin characteristics of aftermarket distribution, highlighting how players optimize portfolio mix to balance volume stability with profitability. Supply chain considerations are addressed through the lens of component sourcing, production capacity allocation, and the increasing importance of regional supply resilience.
Forecasting methodology is transparent and grounded in observable industry indicators. Projections integrate historical growth patterns, vehicle production outlooks, electrification roadmaps, and regulatory trajectories to construct a multi-scenario view of market development. This approach allows decision-makers to stress-test internal assumptions against external baselines, reducing exposure to overconfidence or missed inflection points.
Competitive Landscape: Concentration, Positioning, and Strategic Differentiation
Market structure plays a decisive role in pricing power, innovation pacing, and customer access. The automotive blade fuse sector exhibits meaningful concentration, with a compact group of established manufacturers capturing a substantial share of global demand. The report profiles the companies that define this landscape, analyzing their geographic footprints, product specializations, certification capabilities, and go-to-market strategies.
Littelfuse, Inc., headquartered in Rosemont, Illinois, operates as a broad-line manufacturer of automotive blade fuses and related circuit protection products, serving both OEM and aftermarket channels with a focus on standardized reliability and integrated protection solutions. Eaton Corporation, based in Cleveland, Ohio, leverages its Bussmann series to deliver blade fuse offerings tailored for automotive and marine overcurrent protection, combining engineering heritage with extensive distribution networks. Mersen S.A., headquartered in Courbevoie, France, supplies automotive fuses including blade types, positioning itself within electrical protection portfolios that emphasize material performance and application-specific engineering.
Beyond North America and Western Europe, the competitive field includes highly specialized manufacturers with strong regional anchors and global supply relationships. Pacific Engineering Corporation (PEC), located in Ogaki, Gifu, Japan, manufactures automotive blade fuses supplied to global vehicle makers, underscoring the importance of precision manufacturing and long-term OEM collaboration. MTA SpA, based in Codogno, Italy, produces certified automotive blade fuses and power distribution components, aligning product quality with rigorous automotive certification expectations. Conquer Electronics Co., Ltd., in New Taipei City, Taiwan, operates as a designer and manufacturer of automotive and other fuses including blade types, reflecting the role of flexible manufacturing and export-oriented production in the broader supply ecosystem.
European specialist producers further diversify the landscape. ESKA Erich Schweizer GmbH, headquartered in Kassel, Germany, produces miniature and automotive fuses including blade designs, emphasizing compact form factors and application-sensitive engineering. SIBA, based in Lünen, Germany, manufactures high-quality fuses for automotive and industrial applications, reinforcing the market's emphasis on durability and compliance. AEM Components (USA), Inc., located in San Diego, California, supplies automotive-grade surface mount and blade fuses, addressing niche requirements that span conventional and advanced electrical architectures.
Thermal Fuse Market
The report evaluates how these players compete across dimensions that matter most to procurement and strategy teams: certification breadth, production scalability, OEM relationship depth, aftermarket penetration, and responsiveness to regional specification variations. It also examines the structural implications of market concentration, where a limited number of large suppliers shape baseline pricing expectations and technology adoption rhythms. Understanding this concentration is essential for identifying negotiation leverage, assessing entry barriers, and evaluating partnership or sourcing diversification strategies.
Industry Dynamics Shaping 2026 and the Forecast Horizon
No market develops in isolation. The automotive blade fuse sector is influenced by overlapping forces that alter demand timing, product requirements, and supplier competitiveness. Vehicle electrification continues to redefine electrical load characteristics, increasing the importance of reliable circuit protection across hybrid, battery-electric, and conventionally powered platforms. At the same time, the proliferation of electronic control units, connectivity modules, and advanced sensors expands the number of protected circuits within a single vehicle, changing fuse density requirements and replacement patterns.
Regulatory and safety expectations further tighten the operational environment. Automotive-grade certification, thermal performance validation, and environmental durability standards influence both product design and supplier qualification processes. These requirements create meaningful differentiation between general-purpose and certified automotive offerings, affecting how manufacturers structure their portfolios and how buyers evaluate total cost of ownership.
Supply chain configuration is another critical dynamic. Regional production footprints, logistics resilience, and material availability shape lead times and cost predictability. As manufacturers and Tier-1 suppliers increasingly prioritize supply security, the ability to source from trusted, certified producers with stable capacity becomes a strategic advantage rather than a tactical preference. The report places these dynamics in context, showing how they interact with demand growth to influence market outcomes over the 2026 to 2032 window.
Automotive Blade Fuse Market
Aftermarket behavior also remains a steady demand engine. Vehicle fleet aging, service interval patterns, and the replacement of legacy electrical components sustain consumption even as new vehicle architectures evolve. The interplay between OEM volume cycles and aftermarket replacement demand creates a multi-layered market rhythm that rewards companies capable of balancing both channels effectively.
Why This Research Matters for 2026 Strategy
The strategic value of this study lies in its ability to convert market complexity into structured decision support. For product planning teams, it clarifies where blade fuse demand is most likely to intensify and how application requirements are shifting. For procurement and sourcing leaders, it provides context on concentration, certification, and supply chain resilience that can inform supplier evaluation and contract negotiation. For competitive strategy groups, it outlines how established players position themselves and where differentiation opportunities may emerge.
Most importantly, the report is designed to prevent strategic overreach. Market growth at a 5.8 percent CAGR is meaningful, but it does not eliminate risk. Regional variation, application segmentation, and competitive concentration mean that aggregate growth can mask divergence at the segment level. Companies that rely on headline numbers alone may misallocate resources or underestimate the operational requirements needed to capture demand in specific corridors. By integrating historical performance, forward-looking projections, and competitive context, this research equips stakeholders to make calibrated decisions rather than assumptions.
The complete study expands on every dimension introduced here, offering detailed market sizing across historical and forecast periods, segmentation analysis that identifies where growth concentrates, competitive profiling that maps supplier strengths and positioning, and strategic implications tailored to product, pricing, and sourcing decisions. It is built for teams that require a rigorous baseline before committing capital, capacity, or commercial strategy.
For executives planning 2026 initiatives, the strategic question is no longer whether the automotive blade fuse market is expanding, but how to position within that expansion with precision. This report provides the analytical foundation to answer that question with confidence, while the full dataset and segment-level intelligence remain available for teams that need to ground strategy in complete, validated market intelligence.
For detailed analysis of this topic, please visit the official page: Automotive Blade Fuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


