



PW Consulting: Sodium Hypochlorite Generator Market to Hit USD 239M by 2032, 8.7% CAGR

Navigating the Sodium Hypochlorite Generator Market: Strategic Intelligence for 2026 Decision-Makers
As global industries accelerate the transition toward decentralized and sustainable water treatment solutions, the sodium hypochlorite generator market has emerged as a critical battleground for infrastructure investment, public health modernization, and operational resilience. For executives, municipal planners, and industrial operators navigating the 2026 landscape, understanding the trajectory of on-site chemical generation is no longer a technical exercise—it is a strategic imperative. PW Consulting’s latest market intelligence study dissects the forces shaping this sector, offering a rigorous, data-backed framework to align capital allocation, supply chain strategy, and regulatory compliance with the decade ahead.
The market has already demonstrated remarkable momentum over the past half-decade. Valued at approximately 90.6 million USD in 2020, it has consistently expanded through successive years, crossing the 116.5 million USD threshold by 2023 and climbing to an estimated 134.0 million USD in 2025. This historical trajectory underscores a structural shift rather than a cyclical fluctuation. Looking forward, our forecast model projects sustained expansion through the end of the decade, with revenue expected to approach 239.0 million USD by 2032. The implied compound annual growth rate of 8.7 percent reflects deepening adoption across water utilities, industrial facilities, and commercial operations that are actively seeking to mitigate supply chain vulnerabilities, reduce reliance on bulk chemical transport, and improve on-site disinfection reliability. These macro figures, while compelling, represent only the surface of a highly nuanced landscape. The true strategic advantage lies in understanding how regional deployment patterns, capacity tiering, application-specific demand, and shifting compliance requirements intersect to create asymmetric opportunities for early movers.
The 2026 Decision Matrix: Why Traditional Procurement Models Are Falling Short
For years, water disinfection procurement followed a familiar playbook: order bulk sodium hypochlorite, manage storage and handling risks, and absorb the volatility of chemical shipping and seasonal supply bottlenecks. The 2026 operating environment has rendered that model increasingly fragile. Infrastructure modernization initiatives are accelerating, and public and private operators alike are recognizing that on-site electrolysis systems offer a compelling alternative to centralized chemical logistics. The strategic calculus has shifted from simple cost-per-gallon comparisons to total lifecycle value, encompassing regulatory compliance, worker safety, environmental footprint, and resilience against transport disruptions.
Utilities and industrial facilities are now evaluating generator deployments through a multi-dimensional lens. Municipal operators must weigh NSF/ANSI/CAN 61 certification pathways for drinking water applications against evolving state-level procurement standards, while industrial managers must align system capacities with fluctuating production schedules and brine feedstock availability. Meanwhile, commercial and recreational operators are exploring compact generation units that can deliver consistent disinfection without the logistical overhead of chemical delivery. The procurement cycle has lengthened, the technical evaluation criteria have multiplied, and the competitive field has matured. Organizations that approach this transition with fragmented vendor comparisons or outdated cost models risk overcommitting to suboptimal configurations. The market demands a structured, forward-looking evaluation framework—and that is precisely what our research delivers.
Decoding the Competitive Arena
The sodium hypochlorite generator market is characterized by a concentrated yet strategically active competitive landscape. CR3 firms account for approximately 35 percent of market revenue, while the top five players collectively command around 45 percent. This concentration reflects the technological barriers to entry, the capital intensity of electrolytic system development, and the lengthy qualification cycles required to secure municipal and industrial contracts. Yet the market remains dynamic, with established players continuously refining system architectures, expanding application portfolios, and responding to emerging compliance mandates.
Among the most prominent participants, De Nora, headquartered in Milan, Italy, has built a recognized portfolio around its ClorTec® on-site low-strength sodium hypochlorite generators, alongside the CECHLO-MS high-strength systems that leverage electrolytic brine electrolysis for demanding disinfection environments. The company’s dual focus on low-strength and high-strength architectures positions it to serve both routine municipal water treatment and specialized industrial applications where concentration precision matters.
Xylem Inc., based in Chicago, Illinois, has established a strong presence through its OSEC® branded on-site hypochlorite generation systems, including the B-Plus, B-Pak, and L series. These platforms are engineered for municipal, aquatics, and industrial water disinfection, and their electrolytic process design aligns with utilities seeking to transition away from bulk chemical handling. Xylem’s integration of generation technology within broader water infrastructure offerings gives it a distinctive value proposition for operators pursuing end-to-end system optimization.
Sodium Hypochlorite Generator Market
Ecolab Inc., headquartered in St. Paul, Minnesota, brings a different dimension to the market through its eChlorine® electrolytic sodium hypochlorite generation systems. Designed for on-site production at the point of use, these systems have found particular traction in healthcare and hospitality environments where localized disinfection control, safety, and operational flexibility are paramount. Ecolab’s service-oriented model and cross-sector expertise allow it to address compliance and hygiene requirements that extend beyond traditional water treatment boundaries.
Electrolytic Technologies, operating in the United States, rounds out the competitive core with its Klorigen™ systems, which generate high-strength sodium hypochlorite in the 10 to 15 percent range alongside chlorine gas for municipal water and wastewater disinfection as well as industrial applications. This dual-output capability reflects a differentiated engineering approach that appeals to facilities seeking integrated disinfection chemistry rather than isolated hypochlorite production.
The competitive field is not static. Recent procurement activity and industry engagement signal where demand is crystallizing and where regulatory attention is intensifying. In March 2026, the City of Westminster issued a request for proposals for the purchase and delivery of two on-site sodium hypochlorite generation systems, illustrating how mid-sized municipal operators are moving from evaluation to execution. In November 2025, the City of Tampa’s Water Department completed construction of a new on-site sodium hypochlorite generation facility to produce liquid bleach on-site for disinfection, underscoring the growing momentum behind utility-scale deployments. Meanwhile, the Chlorine Institute scheduled its 2026 Annual Meeting with a focused agenda on sodium hypochlorite manufacturers and on-site chemical generator compliance, signaling that industry standardization and regulatory alignment will remain central themes throughout the forecast period.
Sodium Hypochlorite Market
Regulatory Realities and Infrastructure Tailwinds
No strategic assessment of this market can be separated from the regulatory and infrastructure context that shapes procurement decisions. On-site generation is not merely a technology substitution; it is an operational model change that intersects with drinking water certification, environmental verification, and standards development. The NSF/ANSI/CAN 61 certification framework applies to on-site generated sodium hypochlorite systems used in drinking water treatment, and compliance with these requirements has become a baseline expectation for municipal procurement teams evaluating system reliability and public health protection.
Parallel to certification requirements, the EPA Environmental Technology Verification program has confirmed the performance of on-site hypochlorite generation systems for primary and residual disinfection, reinforcing the technical credibility of electrolytic approaches in environments where consistent disinfection efficacy must be demonstrated. These verification pathways are increasingly referenced in procurement documentation and technical evaluation scores, making them a practical consideration rather than an abstract regulatory footnote.
Beyond drinking water, evolving standards and compliance expectations are shaping adjacent markets. The EN 18087:2026 standard sets requirements for in-situ chlorine dioxide generation from sodium chlorite, reflecting broader momentum toward on-site chemical generation and stricter controls over disinfection chemistry handling. While this standard addresses a different chemical pathway, it illustrates the regulatory trajectory: authorities are formalizing performance, safety, and operational expectations for decentralized generation systems, and manufacturers able to align their architectures with emerging standards will gain a distinct advantage in qualification processes.
Infrastructure dynamics further reinforce demand. Utility infrastructure upgrades are driving demand for on-site generators as operators seek to replace bulk chemical deliveries with more resilient, locally controlled production. This trend is reinforced by the practical realities of brine electrolysis systems, which use diluted salt solution as the primary electrolyte feedstock. The relative availability and logistical simplicity of salt-based feedstocks, combined with the reduction in hazardous chemical transport, make on-site generation an increasingly attractive option for facilities reevaluating their supply chains. These dynamics do not operate in isolation; they interact with regional procurement cycles, utility capital planning horizons, and industrial production requirements, creating a complex but navigable landscape for organizations that have access to granular, forward-looking intelligence.
Inside the PW Consulting Research Framework
Our study is structured to convert market complexity into actionable decision support. Rather than presenting abstract trends, the report maps the operational, financial, and competitive parameters that executives and technical leaders must evaluate before committing to on-site generation investments. The analysis covers the full forecast window from 2026 through 2032, anchored in a verified historical base that traces market development from 2020 onward. This temporal span allows readers to distinguish between short-term procurement cycles and longer structural shifts, ensuring that investment theses are calibrated to realistic adoption timelines.
The report examines capacity segmentation patterns, differentiating between lower-capacity systems designed for localized or intermittent disinfection needs and higher-capacity architectures suited to continuous utility-scale or large industrial operations. These capacity tiers are not merely technical specifications; they determine footprint requirements, brine handling logistics, maintenance cadences, and the economics of scale that vary significantly across deployment contexts. Our analysis unpacks how these capacity splits influence procurement strategy, vendor selection criteria, and total cost of ownership across different operational profiles.
Application-level demand is similarly dissected. Municipal water and wastewater disinfection remains a foundational driver, but the market also encompasses industrial process disinfection, food industry hygiene applications, and swimming pool and recreational water treatment. Each application segment carries distinct compliance expectations, 화학 concentration requirements, and operational rhythms. By mapping these application dynamics without oversimplifying them, the report equips decision-makers to identify where their organization’s operational profile aligns with the strongest demand signals and where cross-segment learning can accelerate evaluation timelines.
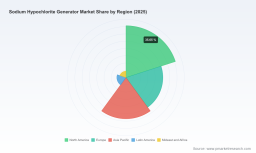
Regional deployment patterns are analyzed with attention to market maturity, procurement pacing, and infrastructure readiness. Rather than reducing regional variation to static share percentages, the research contextualizes how North American, European, Asia Pacific, Latin American, and Middle East and Africa markets differ in terms of utility modernization cadence, regulatory emphasis, and the pace at which bulk chemical delivery models are being supplemented or replaced by on-site production. This regional framing is critical because the same generator architecture may present very different risk-return profiles depending on the local procurement environment and infrastructure context.
Competitive positioning is evaluated through a combination of technology architecture, application coverage, geographic reach, and recent procurement momentum. The report does not stop at company descriptions; it examines how incumbent players are leveraging their system portfolios, service networks, and compliance credentials to shape procurement outcomes, and where gaps in application coverage or regional presence may create openings for new entrants or strategic partnerships. Recent project completions, RFP activity, and industry meetings are integrated into this analysis to connect high-level competitive positioning with real-world procurement behavior.
How to Translate This Intelligence Into 2026 Action
The strategic value of this research lies in its applicability to concrete decision points. For capital planners, the forecast trajectory and segmentation framework support scenario-based budgeting, helping organizations align procurement timing with capacity availability and financing cycles. For technical evaluation teams, the report’s treatment of certification pathways, brine electrolysis feedstock considerations, and performance verification provides a structured basis for vendor qualification and specification development. For commercial and corporate strategy leaders, the competitive concentration data, company profiles, and recent procurement signals offer a lens for assessing partnership opportunities, differentiation potential, and market entry timing.
Organizations that treat on-site sodium hypochlorite generation as a commodity procurement decision risk underestimating the operational and compliance nuances that determine long-term success. Those that approach it as a strategic infrastructure investment, grounded in robust market intelligence, are better positioned to select the right system architecture, align procurement with regional readiness, and anticipate the regulatory developments that will shape qualification standards in the years ahead.
The complete PW Consulting market research study delivers the detailed segmentation data, regional deployment context, application-level demand mapping, and competitive intelligence required to build a decisive 2026 strategy. We invite executives, procurement leaders, and technical decision-makers to access the full report, where the macro trajectory outlined here is expanded into the granular, actionable intelligence necessary to navigate this market with confidence.
For detailed analysis of this topic, please visit the official page: Sodium Hypochlorite Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


