



PW Consulting HVAC Air Filter Market to Hit $316.2M by 2032, Rising at 5.6% CAGR

Strategic Intelligence for HVAC Air Filter Market: Navigating the 2026 Decision Landscape
The global HVAC air filter market stands at a pivotal inflection point. As infrastructure modernization accelerates, indoor air quality regulations tighten, and supply chain dynamics continue to reshape procurement strategies, organizations across residential, commercial, and industrial sectors face a complex array of strategic choices. Our latest comprehensive market research report provides executives, procurement directors, and industry strategists with the analytical framework needed to navigate this evolving landscape with confidence. This overview outlines the strategic value embedded within the study, demonstrating how data-driven insights can directly inform capital allocation, competitive positioning, and long-term growth planning for 2026 and beyond.
Market Trajectory and Structural Evolution
Over the past half-decade, the HVAC air filter industry has demonstrated remarkable resilience and steady expansion. From a baseline of approximately 178.5 million USD in 2020, the total addressable market has steadily climbed through successive years, reaching 216.5 million USD by 2025. This trajectory reflects sustained demand across multiple end-use verticals, driven by heightened health consciousness, stricter building performance standards, and the ongoing replacement cycles inherent to filtration infrastructure. The report projects continued momentum through the 2026-2032 forecast window, with the market anticipated to advance toward 316.2 million USD by the terminal year. This growth is underpinned by a compound annual growth rate of 5.6 percent, a figure that signals not only stability but also the emergence of structural tailwinds that astute organizations can leverage for competitive advantage.
Air Filters Market
Importantly, this expansion is not merely a function of population growth or new construction activity. Underlying shifts in material preferences, performance expectations, and regulatory compliance requirements are fundamentally reshaping how filtration solutions are specified, manufactured, and maintained. Organizations that understand these underlying drivers will be better positioned to anticipate demand fluctuations, optimize inventory strategies, and align product development roadmaps with market realities.
Key Demand Catalysts and Industry Dynamics
Several interconnected forces are accelerating transformation within the HVAC air filtration sector. First, regulatory frameworks continue to evolve with increasing precision, placing greater emphasis on measurable performance outcomes. Recent updates to recognized testing methodologies have established more rigorous evaluation protocols for air cleaning technologies, addressing concerns around secondary emissions such as ozone and formaldehyde. Concurrently, updated compliance guidelines for healthcare environments mandate minimum filtration efficiencies that directly influence procurement specifications across institutional buyers. Energy efficiency certification programs have also introduced new performance criteria, compelling manufacturers and end-users alike to balance filtration effectiveness with operational cost considerations.
Second, the post-pandemic era has permanently altered procurement priorities. Building managers, facility operators, and residential homeowners now approach air quality with a heightened level of scrutiny, recognizing filtration as a critical component of occupant wellbeing and operational continuity. This cultural shift has elevated the strategic importance of filtration systems from routine maintenance items to essential infrastructure investments.
Third, technological innovation cycles are compressing. Recent industry gatherings and product launches have showcased advanced filtration media, improved airflow dynamics, and smarter replacement scheduling tools. Manufacturers are increasingly differentiating through specialized product lines that address specific application requirements, from high-capacity commercial environments to precision-sensitive industrial facilities. These developments create both opportunities and risks: organizations that rapidly adopt performance-leading solutions can capture market share, while those relying on legacy specifications may face compliance gaps or operational inefficiencies.
Pricing dynamics further complicate the decision environment. Basic filtration options remain accessible, but premium-grade solutions with enhanced particle capture capabilities command significantly higher price points and distinct replacement intervals. Understanding where specific applications fall on this value spectrum is essential for cost-effective procurement and long-term total cost of ownership optimization.
Segmentation Insights and Strategic Positioning
While aggregate market figures provide a useful top-line perspective, the true strategic value of our research lies in its granular segmentation analysis. The report dissects demand patterns across multiple dimensions, revealing how material preferences, application requirements, and regional procurement behaviors intersect to shape market outcomes.
Material composition remains a critical differentiator. Synthetic polymer-based solutions continue to dominate volume share, reflecting their balance of performance, durability, and manufacturing scalability. Fiberglass alternatives retain relevance in cost-sensitive applications, while carbon and metal media serve specialized niches where chemical filtration, thermal resistance, or extended service life are prioritized. The research examines how these material categories perform across varying operational conditions, enabling organizations to align specification choices with actual environmental demands rather than convenience or legacy habits.
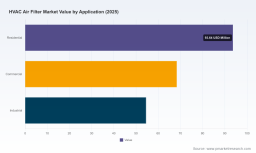
Application segmentation further illuminates demand concentration. Residential settings represent a substantial volume driver, but commercial and industrial applications introduce distinct performance thresholds, procurement cycles, and compliance considerations. The report evaluates how different end-use environments interact with filtration requirements, offering guidance on where value creation is most pronounced and where competitive intensity is highest.
Regional analysis reveals equally important patterns. North American and Asian markets exhibit robust demand fundamentals shaped by construction activity, regulatory environments, and established distribution networks. European procurement behavior reflects a strong emphasis on energy efficiency and sustainability metrics, while emerging markets in Latin America and the Middle East and Africa present evolving opportunities tied to infrastructure development and growing awareness of indoor environmental quality. The study contextualizes these regional dynamics without reducing them to simplistic comparisons, instead providing the nuanced understanding necessary for market entry, expansion, or resource allocation decisions.
Market concentration metrics indicate that the industry remains moderately fragmented, with the top three players collectively commanding approximately 45 percent of revenue and the top five reaching just over 52 percent. This structure suggests that while established incumbents hold meaningful share, there remains sufficient openness for strategic entrants, specialized niche players, and well-positioned distributors to compete effectively through differentiation, service excellence, or regional focus.
Competitive Landscape and Strategic Implications
The HVAC air filter market features a diverse array of participants, each pursuing distinct strategic approaches to capture value. Understanding these competitive postures is essential for any organization seeking to benchmark its positioning or identify partnership opportunities.
HVAC Air Filter Market
Several established manufacturers operate with a clear emphasis on customization and specialized engineering. Companies such as Universal Air Filter and Air Filters Inc. have built reputations around tailored filtration solutions designed for demanding environments, appealing to clients who require precise performance characteristics beyond standard catalog offerings. Similarly, Filterbuy and Filter King maintain strong positions in the replacement and distribution space, leveraging broad product availability and brand recognition to serve both consumer and commercial buyers.
Global and regional leaders like AAF International and Camfil USA occupy the premium performance segment, emphasizing high-efficiency filtration and clean air solutions for applications where air quality directly impacts critical operations. These organizations typically invest heavily in research, testing validation, and technical support, creating competitive moats around performance credibility and long-term customer relationships.
Energy management and lifecycle optimization represent another strategic axis. Nalco Water, operating within broader environmental and water treatment portfolios, integrates filtration technologies with energy-efficient filter life cycle management, appealing to organizations seeking to minimize operating expenses while maintaining compliance. Meanwhile, manufacturers like EAWAY and AirSan Corporation provide specialized product ranges that serve both commercial and industrial applications, often emphasizing media packs, pre-filters, and pocket filter configurations that address specific airflow and contaminant profiles.
Legacy manufacturers such as Glasfloss Industries bring historical manufacturing depth and domestic production capabilities, while specialized suppliers like Tex-Air Filters and Brookaire Co. focus on industrial-commercial segments and extensive MERV-rated inventory, respectively. Factory Direct Filters illustrates another viable model: direct-to-customer distribution of custom-sized filtration products for residential and commercial applications, bypassing traditional intermediaries to capture margin and enhance responsiveness.
Recent market activities underscore the pace of competitive maneuvering. Industry exhibitions have highlighted continuous innovation in filtration technology, with major players showcasing advanced solutions for HVAC applications. Product catalog expansions, including new pre-filter, pleated, and pocket filter lines, reflect ongoing efforts to broaden addressable markets and capture incremental demand. Simultaneously, standardization bodies have introduced updated assessment protocols that will influence how products are evaluated, compared, and ultimately specified by buyers. Organizations that proactively align their offerings with these evolving benchmarks will be better positioned to maintain or improve market standing.
Research Architecture and Operational Utility
The comprehensive report is structured to deliver immediate, actionable intelligence alongside strategic foresight. Our methodology combines rigorous quantitative modeling with qualitative industry assessment, ensuring that findings are both statistically grounded and contextually relevant.
Key components of the study include a detailed historical analysis covering the 2020-2025 period, providing context for recent market behavior and establishing baseline trends that inform forward-looking projections. The forecast framework extends through 2032, offering scenario-aware estimates that account for potential variations in regulatory implementation, economic conditions, and technological adoption rates.
Segmentation chapters dissect market composition by region, material, and application, revealing not just where demand is concentrated but why it concentrates there. These analyses are designed to support product portfolio planning, geographic expansion evaluations, and sales territory prioritization. Competitive profiling extends beyond basic company descriptions, examining strategic focus areas, product philosophies, and likely response patterns to market shifts. Recent developments tracking integrates regulatory announcements, trade show innovations, product launches, and standardization milestones, ensuring that readers understand the immediate forces shaping buyer behavior and manufacturer strategy.
The report also incorporates practical guidance on procurement considerations, including the cost and replacement implications of different filtration grades, the performance expectations associated with various media types, and the compliance implications of evolving testing and certification standards. By connecting technical specifications with financial and operational outcomes, the study enables decision-makers to evaluate trade-offs systematically rather than reactively.
Translating Intelligence into 2026 Action
Access to high-quality market intelligence is valuable only when it translates into concrete strategic action. For 2026 planning cycles, the insights contained within this research can inform a range of critical decisions. Procurement teams can use segmentation and pricing analyses to refine specification guidelines, negotiate more effectively with suppliers, and balance upfront costs against long-term performance and replacement frequency. Product development and innovation groups can identify whitespace opportunities where existing solutions fall short of emerging requirements, particularly as regulatory standards place greater emphasis on comprehensive emission assessment and energy efficiency metrics.
Strategic planners and executives can leverage regional demand patterns and competitive concentration data to evaluate market entry feasibility, partnership potential, and resource allocation priorities. Organizations supplying filtration manufacturers or adjacent HVAC components can use the report's application and material breakdowns to anticipate order volume shifts and align production or inventory accordingly. Investors and analysts will find the revenue trajectory, growth rate context, and competitive structure analysis useful for evaluating sector attractiveness and identifying leading indicators of market maturation.
Ultimately, the report is designed to reduce uncertainty without oversimplifying complexity. It provides the analytical depth required to make informed choices while maintaining the clarity necessary for executive-level communication and cross-functional alignment.
Conclusion
The HVAC air filter market is entering a phase where performance expectations, regulatory scrutiny, and strategic differentiation will increasingly separate leading organizations from those that merely follow. Our comprehensive research report delivers the structured, data-informed perspective needed to navigate this environment with precision. From historical trajectory analysis and forward-looking growth modeling to detailed segmentation evaluation and competitive landscape assessment, every component of the study is purpose-built to support high-stakes decision-making. For leaders seeking to transform market complexity into strategic advantage, the full report offers the complete intelligence foundation required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: HVAC Air Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


