



PW Consulting: Barcode Reader Market Hits $7.67B in 2025, Forecast to $12.3B by 2032 at 6.98% CAGR

Strategic Intelligence in the Barcode Readers Market: Navigating the 2026–2032 Outlook
As digital transformation accelerates across global supply chains, the barcode readers market stands at a critical inflection point. What was once a commoditized peripheral has evolved into a sophisticated interface between physical operations and real-time data ecosystems. For executives navigating 2026 procurement strategies, capital allocation decisions, and technology roadmaps, understanding the structural forces shaping this market is no longer optional. This comprehensive industry analysis delivers a rigorous, data-driven assessment of market trajectories, competitive positioning, and operational dynamics through 2032, providing the analytical foundation required for enterprise-level decision-making.
Macroeconomic Trajectory and Growth Architecture
The market has demonstrated resilient, compounding growth over the past half-decade, with total revenue expanding from approximately $6.91 billion in 2020 to an estimated $7.67 billion in 2025. This historical expansion reflects sustained enterprise adoption across supply chain modernization initiatives, regulatory compliance requirements, and the ongoing digitization of asset tracking workflows. Forecasts extending through the 2026–2032 horizon indicate continued upward momentum, with projected revenue reaching roughly $8.19 billion in 2026 and scaling toward $12.30 billion by 2032. The implied compound annual growth rate of 6.98 percent underscores a market characterized by steady, structurally supported expansion rather than speculative volatility.
This growth trajectory is underpinned by several converging forces. Organizations are increasingly replacing legacy scanning infrastructure with imaging-based and AI-enhanced readers capable of decoding damaged, low-contrast, or high-density codes in variable lighting conditions. Simultaneously, the proliferation of omnichannel fulfillment models, just-in-time inventory practices, and real-time location tracking requirements has elevated barcode scanning from a back-office utility to a mission-critical operational node. Enterprise buyers in 2026 must therefore evaluate scanner portfolios not merely on unit cost, but on interoperability, durability, software integration readiness, and total cost of ownership across multi-year deployment cycles.
Report Scope and Operational Utility
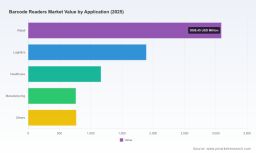
This market research study is engineered to function as a practical decision-support instrument rather than a purely academic overview. The analysis spans multiple dimensional layers, allowing readers to isolate the variables most relevant to their operational context. Coverage includes granular assessments of product architecture categories, deployment environment suitability, and vertical-specific adoption patterns. The report maps the historical performance baseline from 2020 through 2025, establishes forward-looking projections across the 2026–2032 forecast window, and contextualizes these figures within prevailing macroeconomic and regulatory conditions.
Readers will find structured evaluations of technology transitions affecting reader design, including the shift from laser-based illumination to advanced imaging engines, the integration of machine vision capabilities, and the emergence of AI-augmented decoding algorithms that improve read rates in challenging environments. The study also examines procurement considerations such as ruggedization standards, connectivity protocols, firmware lifecycle management, and the extent to which scanner ecosystems integrate with warehouse management systems, enterprise resource planning platforms, and point-of-sale architectures. By consolidating these dimensions into a single analytical framework, the report enables managers to benchmark vendor offerings, model scenario-based investment paths, and identify inflection points where premature or deferred procurement may carry measurable operational risk.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants collectively commanding approximately 25 percent of total revenue and the top five firms accounting for roughly 35 percent. This distribution reflects an environment where established incumbents maintain strong brand equity and installed-base loyalty, while regional specialists and technology-focused entrants compete on feature differentiation, pricing agility, and vertical-specific customization. Understanding the strategic posture of leading suppliers is essential for buyers evaluating long-term partnership stability, service-level commitments, and innovation roadmaps.
Datalogic, headquartered in Bologna, Italy, has cemented its position as a leading manufacturer of CCD and laser-based barcode readers, offering handheld, fixed-mount, and OEM models tailored to retail, manufacturing, and logistics workflows. Its product philosophy emphasizes ergonomic design, read-performance consistency, and broad environmental adaptability. Cognex, based in Natick, Massachusetts, operates at the intersection of industrial barcode reading and machine vision, with its DataMan series spanning fixed-mount, handheld, and verification solutions widely deployed in automation and traceability applications. Cognex's competitive advantage lies in the tight integration of decoding hardware with vision processing algorithms, enabling high-speed identification in precision manufacturing and automotive contexts.
Zebra Technologies, located in Lincolnshire, Illinois, provides a comprehensive range of rugged, ultra-rugged, and general-purpose 1D and 2D scanners designed for retail, healthcare, logistics, and harsh-environment deployments. Zebra's strategy centers on end-to-end device ecosystems, durable construction standards, and deep integration with enterprise mobility platforms. Honeywell, headquartered in Charlotte, North Carolina, manufactures plug-and-play barcode scanners and modules leveraging both laser and imaging technologies, serving general-purpose, industrial, and healthcare applications with an emphasis on ease of integration and standardized configuration options.
Newland AIDC, based in Fuzhou, Fujian, China, has carved out a specialist position in barcode scanners, mobile terminals, and OEM scan engines, increasingly incorporating AI-powered models to serve industrial, retail, and logistics segments. Its growth reflects broader trends in cost-optimized engineering, rapid feature iteration, and expanding distribution reach across emerging and developed markets. Opticon, operating from Renton, Washington, produces 1D laser and 2D imaging barcode scanners, including handheld, fixed-mount, and mobile computer solutions, with a reputation for reliable performance in retail and light-industrial settings. Collectively, these firms illustrate a competitive field where differentiation is achieved through a combination of hardware robustness, software ecosystem maturity, vertical expertise, and supply chain responsiveness.
Industry Dynamics and Regulatory Influences
Market behavior in the barcode readers sector is increasingly shaped by external regulatory pressures, compliance frameworks, and operational events that influence procurement priorities and risk assessments. Recent developments highlight the sensitivity of scanner-dependent operations to pricing accuracy mandates, cross-border trade policy shifts, and manufacturing quality standards. For instance, Zebra Technologies has factored potential tariff-related impacts into its near-term profit outlook, reflecting how trade policy uncertainty can affect component sourcing, final-device pricing, and margin structures for major hardware suppliers. Such dynamics underscore the importance of scenario planning for enterprises with globally distributed supply chains or multi-regional deployment footprints.
Smart Card Readers Market
On the retail compliance front, enforcement actions around price-scanning accuracy have drawn renewed attention to the operational reliability of scanning infrastructure. Regulatory bodies in several jurisdictions have imposed fines and corrective measures on retailers where register-scanner discrepancies resulted in consumer pricing errors, reinforcing the link between scanner performance, software calibration, and audit readiness. In parallel, frameworks such as the Scanner Price Accuracy Code continue to evolve, with updated discount thresholds and enforcement expectations shaping how retailers configure checkout equipment and validate price-display integrity. These regulatory currents create both compliance obligations and procurement incentives, as operators seek hardware and firmware configurations that minimize mismatch risk and facilitate audit documentation.
Manufacturing and quality-assurance standards also exert structural influence on market development. ISO-certified production facilities have become a baseline expectation for many procurement teams, particularly in sectors where device failure carries operational, safety, or regulatory consequences. European market projections further emphasize the role of regulatory compliance in shaping long-term growth trajectories, as buyers align equipment selection with evolving standards related to electromagnetic compatibility, environmental durability, and data-handling expectations. Taken together, these dynamics indicate that purchasing decisions in 2026 and beyond will increasingly weigh compliance readiness and certification status alongside traditional performance metrics.
Barcode Readers Market
Key Decision Frameworks for 2026 and Beyond
Effective market participation in the current cycle requires decision-makers to reconcile several overlapping priorities. First, technology selection must account for the operational environment in which readers will function. Fixed-mount installations in automated production lines or conveyor systems impose different durability, read-angle, and integration requirements than handheld devices used by mobile floor staff or field service teams. Buyers should evaluate whether imaging-based architectures, laser-based architectures, or hybrid configurations best match their code types, label quality, and throughput demands. Second, deployment strategy should consider the increasing prevalence of software-defined features, over-the-air firmware updates, and integration hooks that determine how quickly a scanner fleet can adapt to changing workflows or new barcode symbologies.
Third, supply chain resilience and vendor stability merit close scrutiny. As tariff exposures, component availability, and logistics variables influence lead times and pricing, organizations benefit from mapping vendor manufacturing footprints, service-network coverage, and spare-parts logistics before committing to large-scale rollouts. Fourth, total cost of ownership analysis should extend beyond initial purchase price to encompass training requirements, device lifecycle expectations, battery replacement cycles for mobile units, and the cost of integration with existing management software. Finally, the moderate market concentration observed among leading suppliers suggests that while scale players offer broad portfolios and established support infrastructures, specialized vendors may provide more tailored engineering, faster customization turnaround, and competitive pricing in niche segments.
The strategic implications are clear: barcode readers are no longer interchangeable commodities. They are integral components of data-capture architectures that influence inventory accuracy, order fulfillment speed, compliance posture, and customer experience. Executives who treat scanner procurement as a strategic systems decision, rather than a tactical hardware purchase, will be better positioned to align operational performance with broader digital transformation objectives.
Accessing the Complete Strategic Intelligence
This overview has outlined the structural parameters, competitive forces, and operational considerations that define the barcode readers market as organizations move through 2026 and plan for the decade ahead. The full report expands substantially on these themes, delivering detailed segmentation analysis, forward-looking revenue projections, technology-transition assessments, vendor benchmarking matrices, and scenario-based guidance calibrated to distinct procurement contexts. Readers seeking to translate these macro insights into precise investment decisions, vendor evaluations, and deployment roadmaps are encouraged to access the complete publication. The comprehensive dataset and analytical frameworks contained within provide the depth required to move from general market awareness to actionable, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Barcode Readers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


