



PW Consulting: Industrial Machine Vision Camera Market Hits $2.88 Billion in 2025, Projected 8.3% CAGR to 2032

Industrial Machine Vision Camera Market: Strategic Intelligence for 2026 Enterprise Decision-Making
Executive Context: The Imperative for Precision Intelligence
In the rapidly evolving landscape of industrial automation, machine vision has transitioned from a supportive technology to a central pillar of operational excellence. As we navigate the mid-2020s, the industrial machine vision camera market is undergoing a period of significant transformation. Shaped by technological standardization, shifting trade dynamics, and aggressive adoption of AI-driven inspection, the sector is defined by both complex headwinds and unprecedented upside. For enterprise stakeholders, moving beyond surface-level market narratives is no longer optional. It requires granular, forward-looking intelligence that translates market trajectories into actionable investment and operational strategies.
PW Consulting's latest comprehensive research on the Industrial Machine Vision Camera Market delivers exactly that depth. Built upon a rigorous historical foundation and a disciplined forecast horizon, this report equips strategic leaders with the analytical clarity required to navigate 2026 and the decade beyond. Rather than presenting a static snapshot, the analysis constructs a dynamic framework for understanding how competitive forces, technological inflection points, and supply-chain realities will converge across the forecast period.
Macro Trajectory and Structural Growth Architecture
The historic performance of the industrial machine vision camera sector demonstrates a clear and sustained expansion curve. Across the historical window spanning 2020 through 2025, the market advanced from a baseline of approximately 1,945 million USD to an estimated 2,880 million USD in the most recent full-year assessment. This progression reflects the compounding effect of manufacturing digitization, escalating quality assurance standards, and the integration of vision capabilities into smart production ecosystems. The compound annual growth rate of 8.3 percent underscores the market's resilience and its capacity to outpace broader industrial equipment spending in multiple regions.
Looking toward the forward-looking window extending through 2032, the trajectory indicates continued acceleration. Projected revenue climbs steadily from the 2026 baseline, crossing successive thresholds as adoption scales across industries and technological capabilities mature. By the end of the forecast horizon, the sector is positioned to approach a substantially higher valuation, driven by the compounding demand for high-resolution imaging, embedded vision architectures, and integrated intelligence at the edge. For enterprise planners, this growth architecture is not merely a revenue projection; it represents a structural shift in how industrial value is created, monitored, and optimized.
The growth narrative is anchored by a bifurcated technology landscape. Area scan architectures continue to command substantial share, reflecting their versatility in high-speed inspection, dimensional measurement, and assembly verification. Line scan configurations maintain their critical role in continuous web processing, surface inspection, and high-throughput material handling. Understanding the strategic deployment patterns, performance trade-offs, and pricing dynamics between these technology streams is essential for aligning procurement strategies with operational requirements across diverse production environments.
2026 Market Dynamics: Standards, Supply Constraints, and Trade Realities
The current market environment is defined by a convergence of regulatory, technical, and logistical forces that demand nuanced strategic interpretation. One of the most consequential developments for system architects and procurement leaders is the approval of GigE Vision Version 3.0 by the Association for Advancing Automation in April 2026. This standard update incorporates RoCEv2 technology, enabling high-speed image streaming capabilities reaching 400 Gbps and beyond. For enterprises designing next-generation inspection lines, logistics tracking systems, or real-time process monitoring architectures, this represents a generational leap in data throughput. However, realizing the operational benefits of these bandwidth capabilities requires synchronized investments in network infrastructure, compute architecture, and software stack optimization. Our analysis delineates the realistic adoption timelines and infrastructure prerequisites required to translate this technical leap into measurable throughput gains.
Simultaneously, the industry continues to consolidate measurement rigor through the evolution of EMVA1288, which has been promoted to full international standard status as ISO 24942 and unified under Version 4.1. For engineering and quality teams, standardized camera and sensor characterization eliminates ambiguity in performance benchmarking. Yet, the operational implications extend further: standardized measurement protocols influence vendor selection criteria, drive competitive differentiation around verifiable performance metrics, and reshape procurement evaluation frameworks. The report examines how enterprises are adjusting technical qualification processes to leverage the new standard for supply-chain transparency and performance assurance.
Trade policy remains an active determinant of cost structures and sourcing strategies. The imposition of 25 percent US tariffs on Chinese-origin lenses, contrasted against substantially lower duties on most other machine vision components, has created an asymmetric cost landscape that demands deliberate component-level sourcing optimization. Enterprises that treat vision systems as monolithic procurement packages face heightened exposure to tariff-driven cost inflation. Conversely, organizations that pursue modular sourcing strategies and regional diversification can mitigate exposure while preserving technical performance. The research maps the strategic pathways available to balance cost efficiency with supply reliability in the current tariff environment.
Compounding these trade dynamics are persistent supply-chain constraints affecting image sensors and optical components. These constraints continue to influence production timelines for industrial machine vision systems, creating lead-time variability that can disrupt line integration schedules and capacity ramp-up plans. Strategic procurement and inventory architecture have therefore become critical competitive differentiators. Our analysis evaluates the evolving supplier ecosystem, identifies the capacity allocation patterns that influence lead-time predictability, and provides guidance on structuring procurement commitments to preserve operational continuity without sacrificing agility.
Competitive Landscape: Strategic Profiling and Ecosystem Positioning
The competitive architecture of the industrial machine vision camera market is characterized by a mix of established system integrators, specialized camera manufacturers, and critical sensor technology providers. Industry concentration metrics indicate that the three largest players collectively account for approximately 25 percent of market revenue, while the top five expand that share to roughly 35 percent. This structure reflects a market that is neither fully consolidated nor highly fragmented, but rather one where scale, technological differentiation, and application-specific expertise determine competitive advantage.
Cognex Corporation, headquartered in Natick, Massachusetts, remains a defining presence in the sector. Its portfolio of industrial machine vision cameras, barcode readers, and complete vision systems supports automated inspection, defect detection, and robotic guidance across broad manufacturing verticals. The company's strength lies in its ability to deliver integrated, application-tuned solutions that reduce system integration complexity for end-users operating at scale.
Basler AG, based in Ahrensburg, Germany, has built a reputation for manufacturing industrial machine vision cameras that emphasize premium sensors, robust connectivity options including USB 3.0, GigE, and CoaXPress, and a comprehensive range of area scan, line scan, 3D, and embedded models. For automation engineers seeking reliability and interface flexibility across demanding deployment scenarios, Basler's product architecture provides a compelling foundation.
Teledyne FLIR, operating from Wilsonville, Oregon, extends the competitive field into advanced thermal and multispectral imaging territory. Its capabilities in inspection, quality control, and non-contact measurement provide distinctive value in applications where conventional visible-spectrum imaging is insufficient. This positions the company at the intersection of traditional machine vision and specialized sensing modalities.
In the Asia-Pacific competitive axis, Omron Corporation, based in Kyoto, and Keyence Corporation, headquartered in Osaka, represent powerful contenders. Omron's smart cameras and software platforms are engineered for precision inspection, measurement, and tight integration into automated production lines. Keyence focuses on high-performance cameras and measurement systems optimized for high-speed defect detection, dimensioning, and assembly verification, with particular penetration in electronics and automotive manufacturing environments.
The European specialist tier includes Allied Vision Technologies in Thalwil, Switzerland, which emphasizes high-resolution sensors and flexible interfaces for robotics, logistics, and quality assurance applications; IDS Imaging Development Systems in Obersulm, Germany, which has established itself in robust cameras, sensors, and systems optimized for machine integration and real-time industrial imaging tasks; and JAI A/S in Rødovre, Denmark, whose product emphasis on high sensitivity and versatile connectivity supports food inspection, semiconductor, and biomedical applications.
At the component level, Sony Semiconductor Solutions, headquartered in Tokyo, supplies industrial-grade image sensors and machine vision cameras leveraging advanced CMOS and related technologies for high-resolution, low-light industrial inspection. Meanwhile, SICK AG in Waldkirch, Germany, integrates AI-enabled vision sensors and cameras for automated defect detection, sorting, and process monitoring, reflecting the broader market shift toward intelligent, algorithm-driven inspection at the sensor and camera level.
Industrial Cameras Market
Strategic positioning within this landscape requires more than recognizing brand presence. It demands a granular understanding of how each competitor's product roadmaps, connectivity strategies, application focus, and partnership ecosystems align with specific enterprise requirements. The report maps these alignments and provides the analytical basis for vendor evaluation, partnership structuring, and technology roadmap planning.
Report Architecture: Operational Content and Decision-Readiness
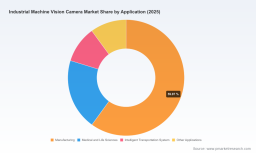
The research is designed for direct integration into corporate planning workflows. Its architecture balances macro-level strategic framing with the operational detail required by engineering, procurement, and commercial teams. Core coverage includes comprehensive market sizing and forward projections anchored in a disciplined historical baseline and a clearly defined forecast horizon. The analysis decomposes the market across technology architectures, application environments, and regional demand patterns. Critically, the report avoids superficial aggregation and instead examines the structural drivers that differentiate growth trajectories across segments.
Beyond quantitative sizing, the report delivers operational instruction in several high-value areas. It profiles the competitive positioning of leading firms, evaluates recent product releases, standard updates, and trade show activity, and interprets their implications for procurement timing and technology adoption. The inclusion of recent developments, such as the Phoenix 28×28 mm camera release by LUCID Vision Labs in March 2026, the VISION Show 2026 exhibition plans for IMAGO Technologies and Active Silicon, and the ongoing EMVA certification processes tied to the unified ISO-standardized characterization method, ensures that decision-makers are grounded in near-term market activity rather than backward-looking summaries.
The study also provides structured evaluation frameworks for assessing vendor viability, technology readiness, and total cost of ownership across different deployment contexts. For enterprises planning capacity expansion, technology refresh cycles, or supplier diversification, these frameworks translate market complexity into actionable selection criteria. The report's treatment of trade exposure, supply-chain lead-time variability, and standardization-driven procurement evolution gives procurement and operations leaders the context needed to build resilient sourcing strategies.
Industrial Machine Vision Camera Market
Strategic Value for 2026 Enterprise Decision-Making
The industrial machine vision camera market in 2026 is no longer a commodity procurement category. It is a strategic technology domain where performance differentiation, integration velocity, and supply resilience directly influence production quality, throughput, and operational cost. Enterprises that rely on fragmented market intelligence risk misaligning technology investments with actual adoption trajectories, overpaying for components exposed to tariff volatility, or underestimating the infrastructure requirements needed to exploit next-generation connectivity standards.
This research was constructed to eliminate those blind spots. By combining rigorous historical analysis with forward-looking scenario framing, it enables enterprises to prioritize technology roadmaps, calibrate procurement strategies, and align internal engineering capacity with market realities. The analysis is particularly relevant for organizations evaluating high-bandwidth imaging deployment, navigating component-level tariff exposure, standardizing performance qualification processes, or restructuring supplier relationships in response to persistent sensor and optics supply constraints.
The complete research deliverable provides the full segmentation architecture, regional demand structures, application-specific revenue breakdowns, technology adoption curves, and competitive benchmarking data necessary to convert market insight into executable strategy. To access the complete intelligence package, including detailed segmentation, competitive positioning matrices, and actionable procurement guidance tailored to 2026 planning cycles, visit the source page and obtain the full report. In a market where timing, precision, and supply resilience define competitive advantage, comprehensive intelligence is not an optional enhancement; it is a strategic prerequisite.
For detailed analysis of this topic, please visit the official page: Industrial Machine Vision Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


