



PW Consulting: Chelating Agents Market Set for 6.1% CAGR to Reach $344.8 Million by 2032

Navigating the Next Wave: Strategic Imperatives in the Global Chelating Agents Market Through 2032
The global chelating agents market stands at a critical inflection point. Based on comprehensive historical analysis from 2020 through 2025 and forward-looking forecasts extending to 2032, the market has demonstrated a trajectory of robust, compound annual growth. For executive leadership teams, procurement directors, and strategic planners, the question is no longer whether demand will expand, but how organizations can position themselves to capture value amidst shifting regulatory tides, raw material volatility, and an increasingly bifurcated product landscape defined by traditional performance versus emerging sustainability mandates. Our latest market research report offers the granular intelligence required to navigate this complexity, transforming macro-level economic signals into actionable strategic roadmaps for the 2026 fiscal year and beyond.
The historical data outlines a market that has steadily accelerated its revenue generation. Reviewing the performance from a base of approximately $163.15 million in 2020, the sector climbed consistently through successive years, reaching $170.07 million in 2021, $172.94 million in 2022, $185.51 million in 2023, and $206.85 million in 2024. Entering the most recent reporting year of 2025, the market total was valued at $215.0 million. This established foundation sets the stage for the forecast period beginning in 2026, where the market size is projected to surge to $236.38 million, followed by projected valuations of $247.57 million in 2027, $257.16 million in 2028, $284.71 million in 2029, $297.93 million in 2030, $312.61 million in 2031, and ultimately reaching $344.8 million by 2032. This trajectory, underpinned by a robust compound annual growth rate (CAGR) of 6.1% across the forecast horizon, signals sustained structural demand. For decision-makers, this growth represents both a significant opportunity for market share expansion and a rising risk of supply chain disruption if capacity investments and procurement strategies are not meticulously aligned with forecasted consumption patterns.
Chelating Agents Market
Chelants Market
However, relying solely on top-line revenue figures is insufficient for sophisticated strategic planning. The true competitive advantage lies in decoding the intricate segmentation dynamics that drive these numbers. Our research dissects the market across multiple critical dimensions, specifically analyzing regional consumption patterns, the evolving dichotomy between application-specific performance chemistries, and the distinct categorization by product nature. While the overall economic signal is strong, the distribution of value is not uniform. Understanding where demand is intensifying, which product archetypes are gaining traction, and how industrial, commercial, and consumer applications are diverging is paramount.
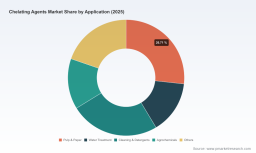
In the realm of geographic consumption, distinct regional economic profiles dictate varied growth drivers. Certain established markets maintain heavy reliance on mature industrial ecosystems, while high-growth regions are accelerating adoption due to expanding manufacturing bases, urban infrastructure development, and stringent environmental compliance requirements. The ability to align supply chain logistics and distribution networks with these disparate regional consumption velocities is a key differentiator. Similarly, the analysis of how demand is partitioned across core verticals reveals critical interdependencies. End-use sectors are the ultimate arbiters of volume. Traditional industrial applications continue to anchor volume, yet we are observing a marked acceleration in segments where water remediation, advanced cleaning formulations, and chemical processing are driving incremental growth. The report delves deep into these application-specific volumes, providing the granular breakdown necessary to identify which sectors offer the highest margin potential and which are susceptible to commoditization pressures. Furthermore, the categorization by product nature presents a strategic crossroads: the market remains anchored by non-biodegradable variants that dominate current volume, yet the share attributable to biodegradable alternatives is expanding at a significantly faster pace, propelled by regulatory pressure and brand owner sustainability commitments. Understanding the precise revenue mix and the elasticity of demand between these two archetypes is essential for portfolio optimization.
The Competitive Architecture: Navigating a Consolidated yet Dynamic Landscape
The chelating agents market is characterized by a moderately concentrated competitive structure. With the top three players accounting for a significant portion of market share and the top five controlling over half of total industry revenue, the landscape is dominated by multinational chemical giants with deep integration capabilities. However, the market remains contestable, with regional specialists and innovators driving disruption through niche product development, cost-competitive manufacturing, and sustainable chemistry alternatives. Our report provides a detailed competitive profiling of the key entities shaping the market trajectory, enabling clients to benchmark their strategic positioning against the moves of the industry's most influential players.
BASF SE, headquartered in Ludwigshafen, Germany, remains a foundational pillar of the global supply chain. As a leading producer of the Trilon® EDTA-series chelating agents, BASF provides comprehensive solutions spanning home care, industrial cleaning, agriculture, and broad industrial applications. The company's extensive product portfolio and brand recognition in the EDTA space make it a benchmark for performance and reliability. In a telling recent development that highlights the cost pressures ravaging the industry, BASF announced in June 2026 a price increase effective July 1, 2026, or as existing contracts allow, raising prices by $0.33 per kilogram for a broad select of its Trilon® chelating agents portfolio in North America. This adjustment affects liquid and solid forms of Trilon B, Trilon BD, Trilon BS, Trilon BX, Trilon C, Trilon CA Food Grade, Trilon D, Trilon G, and Trilon NA Food Grade. The rationale, as stated in BASF's official press release, points to an unrelenting convergence of cost drivers: continued increases in key raw material inputs, spiraling energy costs, and persistent logistics inflation, compounded by ongoing supply chain volatility. For customers and competitors alike, this move is a stark indicator of the margin compression facing traditional chemistry and the necessity for robust hedging strategies and supply diversification.
Dow Inc., based in Midland, Michigan, United States, maintains a formidable presence through its VERSENE™ EDTA and acid chelating agents. Dow's portfolio is engineered for broad pH metal ion control, serving critical functions in detergents, food processing, and complex industrial systems. Their ability to deliver consistent performance across widely varying pH environments positions them as a preferred supplier for applications where process chemistry precision is non-negotiable. Meanwhile, Nippon Shokubai Co., Ltd., operating from Osaka, Japan, distinguishes itself through innovation in high-performance polymeric chelating agents. Their AQUALIC™ line exemplifies this technological focus, targeting detergents, water treatment, and paper/pulp applications. This specialization allows Nippon Shokubai to command premium positioning in segments where efficiency and specific material interactions are valued over commoditized pricing.
On the Asian manufacturing front, Shandong IRO Chelating Chemical Co., Ltd., headquartered in Zaozhuang, Shandong, China, has established itself as a manufacturer of a remarkably full-spectrum chemistry catalog. Their production capabilities encompass the full EDTA-series, DTPA-series, NTA-series, and organophosphine chelating agents. This breadth enables Shandong IRO to serve a vast array of downstream markets including detergents, agriculture, textiles, and food applications, often providing a cost-competitive alternative to western incumbents and catering to the rapid industrialization demands of the Asia Pacific region. In the sustainability corner, two European players stand out for their strategic pivot toward bio-based solutions. Jungbunzlauer, based in Basel, Switzerland, is a recognized producer of biodegradable fermentation-based chelating agents, specifically citrates and gluconates. Their expertise is highly relevant for sensitive applications such as food, beverage, and personal care formulations, where natural origin and safety profiles are paramount. Complementing this, Nouryon, headquartered in Amsterdam, Netherlands, is a manufacturer of advanced biodegradable chelating agents including GLDA, MGDA, IDS, and HBED. These next-generation chemistries are engineered for demanding applications in agriculture, detergents, and industrial processes, offering performance profiles that can rival traditional EDTA while addressing the biodegradability gaps that are increasingly drawing regulatory scrutiny.
The strategic implications of this competitive map are profound. BASF's recent pricing maneuver serves as a case study in the vulnerability of supply chains dependent on petrochemical derivatives and energy-intensive production routes. It underscores the value of contracts with long-term price stabilization clauses and the potential for suppliers of alternative chemistries to gain traction as buyers seek to mitigate cost risk. The divergence between BASF/Dow's commodity-scale EDTA focus and the specialized offerings of Nippon Shokubai, Jungbunzlauer, and Nouryon highlights the market's polarization. Buyers must now evaluate not just price per kilogram, but the total cost of performance, including regulatory compliance costs, consumer perception risks, and the operational flexibility offered by different chemical architectures. Our report dissects these competitive dynamics, analyzing market share concentrations, strategic partnerships, capacity expansions, and the product launch trajectories that will define market winners and losers over the forecast period.
Actionable Intelligence for 2026 Decision-Making
A market research report is only as valuable as its applicability to real-world business challenges. Our Chelating Agents Market study is designed as an executive toolkit, providing the operational intelligence required to make informed decisions in procurement, R&D, M&A, and market entry. The report structure moves beyond descriptive analytics to deliver prescriptive insights. Key components include:
- Detailed Value Chain Mapping: An end-to-end analysis of the supply ecosystem, from key raw material precursors like formaldehyde, sodium cyanide, and ethylene diamine to the manufacturing processes, logistics networks, and downstream consumption loops. This mapping identifies critical bottlenecks, sub-tier supplier dependencies, and points of leverage where supply disruptions or cost pass-through mechanisms are most likely to impact margins.
- Regulatory and Sustainability Deep-Dive: A comprehensive review of the evolving regulatory landscape across major jurisdictions. This includes an assessment of restrictions on EDTA usage in certain household detergents in the European Union and other regions, the growing emphasis on aquatic toxicity profiles, and the incentives driving the adoption of readily biodegradable alternatives. The report evaluates the timeline for regulatory enforcement and its projected impact on demand substitution across different regions and applications.
- Technology and Formulation Trends: An evaluation of emerging chelating technologies and formulation science. This covers the development of hybrid chelants, synergistic blends, and the integration of chelating agents into concentrated and solid detergent formats. Understanding these technical shifts is crucial for product developers aiming to future-proof their formulations against performance degradation or regulatory non-compliance.
- Procurement and Negotiation Intelligence: Drawing on the cost pressure signals exemplified by BASF's recent announcement, the report provides a framework for analyzing supplier pricing power, raw material exposure indices, and the negotiation levers available to buyers. It helps procurement teams anticipate price volatility cycles and structure contracts that balance supply security with cost control.
- Segmentation-Specific Growth Models: While the aggregate market data provides the macro context, this report unlocks the specific regional and application-level drivers. The segmentation data reveals how demand is ordered across the top-five regions, the interplay between type-based consumption of non-biodegradable versus biodegradable chemistries, and the volume distribution across key application verticals. This level of detail is essential for allocating marketing resources, targeting plant expansion, and identifying white-space opportunities in underserved niches.
The Path Forward: Translating Data into Advantage
The chelating agents market of 2026 is not merely a reflection of past industrial activity; it is a complex system influenced by the interplay of chemical engineering, environmental policy, global supply chain resilience, and shifting consumer expectations. The headline growth figures, while impressive, are a composite of divergent underlying forces. Some segments will thrive on volume and cost efficiency, while others will be propelled by performance differentiation and the urgent need for sustainable alternatives. Organizations that treat this market with a one-size-fits-all strategy risk being blindsided by localized disruptions, margin erosion, or regulatory headwinds.
Access to the complete intelligence contained in this report is the bridge between reactive management and proactive strategy. The data on regional consumption velocities, the precise revenue contributions of each product type, and the application-specific volume forecasts allow planning teams to model multiple scenarios with confidence. The competitive profiles provide the context to anticipate competitor moves, whether that involves BASF's pricing adjustments to protect margins or Nouryon's push into bio-based agriculture solutions. The industry context, highlighted by raw material and energy cost dynamics, equips stakeholders with the foresight to manage risk proactively.
We invite you to explore the full scope of this analysis. The insights presented here are a glimpse into a comprehensive body of work designed to empower your executive team with the clarity and depth needed to lead in a dynamic market environment. By leveraging the detailed segmentation data, the granular competitive assessments, and the forward-looking scenario analyses provided in the full report, you can transform the 6.1% CAGR growth trajectory into a tailored strategic advantage. To access the complete dataset, regional and application breakdowns, and the full suite of strategic recommendations, please visit our source page to download the full study. Equip your organization with the intelligence required to navigate the complexities of the chelating agents market and capture the value that lies ahead.
For detailed analysis of this topic, please visit the official page: Chelating Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


