



PW Consulting: Canned Tuna Market Hits $215M in 2025, Growing at 4.2% CAGR to $284M by 2032

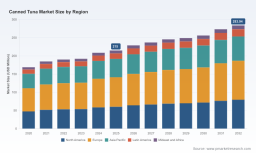
Strategic Intelligence for the Canned Tuna Sector: Navigating a USD 283.94 Million Landscape by 2032
The global canned tuna market is entering a critical inflection point. As supply chains recalibrate, regulatory frameworks shift, and consumer preferences fragment, executives need more than high-level projections to make informed decisions. PW Consulting’s latest Canned Tuna Market research report was built to answer that need. Drawing on a comprehensive historical baseline from 2020 through 2025 and projecting forward through 2032, this study translates macro momentum into actionable intelligence for category managers, supply chain directors, and corporate strategists.
Canned Fruits Market
The market’s trajectory tells a clear story. Revenue has expanded steadily from USD 169.0 million in 2020 to an estimated USD 215.0 million in 2025, reflecting resilient demand across both mature and emerging channels. The forecast period extends this upward path, with the market expected to reach USD 229.08 million in 2026, USD 245.6 million by 2028, and ultimately USD 283.94 million by 2032. A compound annual growth rate of 4.2% underscores the category’s structural stability, but also its competitive intensity. Sustained expansion at this pace rarely rewards passive positioning. Companies that understand the underlying demand architecture, pricing mechanics, and geographic orchestration of supply will be best equipped to capture margin while competitors chase volume.
This report is designed as a strategic toolkit, not a static snapshot. It maps the operational realities that shape the category today and equips leadership teams with the data they need to allocate resources, calibrate pricing, and time market entries with precision.
What the Report Delivers: An Operational Roadmap
PW Consulting’s analysis is structured around the practical questions that decision-makers face when planning for the 2026 to 2032 horizon. The report begins by anchoring every forecast in a verified historical dataset, allowing readers to trace how the market evolved through periods of raw material volatility, shifting retail behavior, and regulatory change before modeling the years ahead.
Readers will find:
- A full revenue timeline from 2020 to 2032, presented in USD millions, with inflection points identified so that teams can understand not just where the market is heading, but when shifts are likely to occur.
- A breakdown of the market by type, highlighting the divergent dynamics between light tuna and white tuna segments, including how product positioning, premiumization, and formulation innovation are reshaping category economics.
- An application-level view that separates household consumption from foodservice demand, enabling brand owners and foodservice operators to align their growth strategies with the channel most relevant to their business model.
- A regional architecture that isolates the distinct growth profiles, consumption patterns, and supply dependencies across major geographic zones without getting lost in fragmented tactical detail.
- A competitive landscape assessment covering the companies that define market behavior, including their strategic positioning, geographic reach, and recent operational moves.
- Regulatory and trade intelligence that integrates tariff adjustments, quota procedures, bilateral trade developments, and raw material cost pressures into a single, coherent read on risk and opportunity.
The report’s value lies in connecting these layers. Revenue figures alone do not tell a strategist whether a category is defensible, whether a pricing action will hold, or whether a new product line will land in a saturated channel. By integrating type, application, region, and competitive behavior into one analytical frame, the study provides a basis for scenario planning, portfolio decisions, and channel-specific investment choices.
The Competitive Arena: Ten Players Defining Market Behavior
The canned tuna category is characterized by high concentration and differentiated strategic playbooks. Market leadership is not distributed evenly, and the report captures that reality by profiling the firms whose decisions shape pricing, private label dynamics, export orientation, and premium positioning. Stakeholders evaluating partnerships, competitive threats, or channel expansion will find these companies among the most important reference points.
Several major US-based packers and distributors continue to anchor the North American retail environment. Starkist remains a central force in chunk light, albacore, and flavored variants, with a broad consumer footprint. Bumble Bee Foods competes directly with a strong branded presence in chunk light and value-added options. Tri-Union Seafoods operates across multiple recognizable brands and private label channels, including Genova, Van Camp’s, and Chicken of the Sea, giving it a distinctive role in both branded and value-oriented retail segments. American Tuna and Safe Catch have carved out more differentiated plays in the sustainability and production-quality space, with American Tuna focusing on sustainably sourced, pole-and-line caught albacore and Safe Catch emphasizing hand-packed, slow-cooked processing. These specialized positions matter because they influence price elasticity, consumer trust, and the boundaries of category innovation.
Canned Tuna Market
Outside the United States, the competitive map widens into export-oriented manufacturing and premium positioning. Golden Prize Canning Co., Ltd. in Thailand represents a significant production capability for canned and pouched tuna, particularly in export and private label channels. Frinsa Group in Spain brings European manufacturing depth and a dual strategy of private label and own-brand tuna products. Tonnino in Italy has built recognition around premium canned tuna fillets, an orientation that aligns with growing consumer interest in quality and presentation. KTC Canned Foodstuff Manufactory in Vietnam adds another export-focused manufacturing node, reflecting the region’s continued relevance in global seafood value chains.
Recent market activity reinforces how quickly operational events can reshape competitive perceptions. In January 2026, Tri-Union Seafoods disclosed that a third-party distributor inadvertently released quarantined product associated with a February 2025 recall of select Genova Yellowfin Tuna cans due to a manufacturing defect with potential Clostridium botulinum risk. Beyond its immediate operational implications, an event of this nature can influence retailer confidence, shelf access, and brand recovery strategies across the broader category. At the same time, Capital Food International pursued an aggressive global exposure strategy in May 2026, appearing at Gulfood Dubai, The Saudi Food Show in Riyadh, the TÜYAP Fair Center in Istanbul, and Foodex Japan, showcasing premium canned tuna and seafood to international buyers. These kinds of moves matter because they signal where companies are betting on demand growth, channel expansion, and geographic diversification.
Market Dynamics: Regulation, Raw Materials, and Trade Realignment
Pricing and availability in canned tuna are highly sensitive to forces that extend well beyond the shelf. In 2025, fluctuating raw material prices, particularly for skipjack tuna, continued to pressure profit margins for processors and canners. This dynamic is central to forecasting because input cost volatility interacts with tariff structures, export pricing, and private label negotiations in ways that can compress or expand category profitability without any change in end-consumer demand.
Trade policy and regulatory frameworks are now equally important variables. In January 2026, U.S. Customs and Border Protection issued Quota Bulletin 26-212, establishing a tariff rate quota for canned tuna, not in oil, for 2026, with opening-moment procedures set for January 2, 2026, under HTSUS Chapter 16. The timing and mechanics of tariff rate quotas can influence sourcing decisions, landed cost calculations, and the relative attractiveness of different supply routes. At the same time, a draft EU-Indonesia free trade agreement has drawn attention for its potential impact on access and pricing, including a provision for 800 tonnes of canned tuna duty-free and the full removal of tariffs on tuna fillets and whole tuna. Trade arrangements like these can reshape the economics of export-oriented manufacturers and alter the competitive balance between sourcing regions.
On the pricing side, Thai canned tuna export prices to the US are expected to rise to approximately USD 6,500 per ton after accounting for new reciprocal tariffs, according to independent research published in mid-2025. Even when not stated as a headline forecast, tariff-driven cost escalation can cascade into retail pricing, private label renegotiation, and margin planning. For companies operating across multiple regions, the strategic question is not simply whether costs rise, but which channels, formulations, and geographies can absorb those costs without sacrificing volume.
Why This Research Matters for 2026 Decision-Making
A 4.2% CAGR may appear modest in isolation, but in a category shaped by concentrated competition, input cost volatility, and evolving trade policy, the real strategic challenge is differentiation under constraint. Companies are not competing only on volume; they are competing on margin durability, channel fit, sourcing resilience, and brand trust. In that environment, broad market data is necessary but not sufficient. Decision-makers need to understand how the components of the market interact, where sensitivity is highest, and which competitive moves are likely to affect their own operating context.
The PW Consulting report is built for that level of analysis. It supports a range of corporate use cases: assessing whether a household-focused growth strategy is more defensible than a foodservice-oriented one, identifying where type-based differentiation can support premium pricing, evaluating exposure to trade and tariff shifts, and benchmarking a company’s position against the firms that most directly influence category behavior. Executives planning product launches, pricing adjustments, supply contracts, or market entry will find the historical baseline useful for stress-testing assumptions, while the forecast structure helps translate those assumptions into a forward plan.
The report also functions as an early-warning framework. Regulatory changes, recall events, trade show positioning, and raw material fluctuations are not isolated news items; they are signals that can affect procurement timing, shelf negotiations, export planning, and portfolio prioritization. By integrating these developments into the market narrative, the study helps teams move from reactive monitoring to proactive planning.
Aligning Strategy with the Next Phase of Growth
The canned tuna market’s path from 2026 to 2032 is unlikely to be defined by a single breakthrough or a single constraint. It will be shaped by how companies manage the tension between steady demand growth and operational pressure. That makes strategic clarity essential. Firms that understand the balance between light tuna and white tuna economics, the distinct behavior of household consumption versus foodservice demand, and the regional differences in supply and consumption will be better positioned to allocate capital efficiently.
Equally important, they will be better positioned to read competitive signals. Whether a manufacturer is pursuing private label scale, premium fillet positioning, sustainability claims, or export expansion, each strategy carries different risks and different margin implications. The competitive profiles and recent industry developments included in this research provide context for interpreting those strategies in real time.
This report is structured to give leaders the breadth and depth required to make those calls with confidence. The full study contains the detailed breakdown, structural analysis, and forward estimates needed to support specific strategic plans. Readers who require granular commercial intelligence for investment decisions, pricing strategy, sourcing configuration, or competitive positioning are encouraged to access the complete report for the full range of data and analysis.
Access the Full Intelligence Suite
The canned tuna category will reward firms that plan with precision, monitor the right signals, and act before a shift becomes obvious to the whole market. PW Consulting’s Canned Tuna Market research is designed to support exactly that kind of leadership. The complete version of the report provides the detailed segmentation, regional and application-level structure, competitive mapping, and forward forecasts necessary to translate market momentum into concrete corporate decisions.
For procurement leaders, brand strategists, investment teams, and market development executives preparing for the 2026 to 2032 planning cycle, the full report offers the depth needed to move beyond general trends and into actionable market intelligence.
For detailed analysis of this topic, please visit the official page: Canned Tuna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


