



PW Consulting: Aluminum Electrolytic Capacitor Market to Hit $8,020M by 2032, CAGR 3%

Strategic Intelligence for the Aluminum Electrolytic Capacitors Market: Navigating the 2026 Landscape
The global aluminum electrolytic capacitors market stands at a critical inflection point as industries transition from legacy power architectures to high-efficiency, miniaturized electronic systems. At PW Consulting, we recognize that capacitor selection is no longer a procurement formality but a strategic lever influencing product reliability, supply chain resilience, and long-term margin structures. Our latest market research offers a comprehensive, decision-grade blueprint tailored for executives, product engineers, and supply chain strategists operating in 2026 and beyond.
This introductory overview outlines the methodological rigor, structural depth, and strategic applicability embedded within the full report. While macro-trends are presented here to establish baseline context, granular segmentation data, proprietary forecasting models, and competitive benchmarking matrices remain exclusive to our published deliverables. The objective is clear: equip leadership teams with the analytical framework necessary to anticipate disruption, optimize sourcing strategies, and capture sustainable growth in a consolidating component landscape.
Macro Trajectory and Structural Market Dynamics
Over the past half-decade, the aluminum electrolytic capacitors market has demonstrated steady expansion, driven by sustained demand across consumer electronics, automotive electrification, industrial automation, and telecommunications infrastructure. Historical revenue trends through 2025 reflect a mature but resilient ecosystem, with global market valuation progressing from mid-2020 levels to approximately $6.5 billion by 2025. This trajectory underscores the component's enduring relevance despite persistent substitution pressures from ceramic and film alternatives in high-frequency applications.
Looking forward, the forecast horizon extends through 2032, with market size projected to exceed $8.0 billion by the terminal year. The annualized growth rate across this period stabilizes at a 3.0% compound trajectory, reflecting a balanced interplay between volume expansion in emerging applications and price normalization in legacy supply chains. This moderate but consistent growth profile signals a market that has matured past speculative volatility, now entering a phase defined by efficiency-driven procurement, material cost optimization, and strategic capacity allocation.
Several structural forces will dictate the pace and distribution of future demand. First, the ongoing electrification of vehicle platforms continues to elevate requirements for high-reliability, long-life electrolytic solutions in auxiliary power distribution, battery management circuits, and motor drive filtering. Second, telecommunications infrastructure upgrades—particularly in 5G baseband units, remote radio heads, and edge computing power supplies—sustain steady consumption of both radial and surface-mount variants. Third, industrial automation and renewable energy conversion systems are driving renewed engineering focus on electrolytic capacitors capable of enduring elevated ripple currents, extended thermal cycling, and prolonged operational lifespans without degradation.
Material constraints remain an equally decisive variable. The etched foil supply chain, dominated by a tightly controlled oligopoly, has historically experienced lead time compression during demand surges, with high-purity foil procurement cycles extending to twenty-four weeks in peak scenarios. This bottleneck introduces critical upstream risk for manufacturers reliant on standardized foil grades, particularly as automotive and industrial specifiers demand tighter tolerance envelopes and lower ESR profiles. The 3-micron manufacturing threshold currently represents a technological and capacity constraint that will shape supplier selection criteria and pricing negotiations throughout the forecast window.
Consolidation dynamics further complicate the competitive landscape. The top three players command approximately 40% of aggregate market share, while the top five collectively account for roughly half of global revenue. This concentration reflects decades of vertical integration, proprietary electrolyte formulation expertise, and entrenched design-in relationships across power supply and consumer electronics OEMs. Yet, the remaining market share is fragmented across specialized regional players, polymer-focused innovators, and hybrid-technology adopters, creating both partnership opportunities and competitive pressure points for incumbents seeking to defend margin structures.
Comprehensive Report Architecture and Operational Utility
PW Consulting's Aluminum Electrolytic Capacitors Market report is structured to translate macro-level intelligence into actionable decision pathways. The deliverable is organized across multiple analytical layers, each calibrated to address specific executive functions, from portfolio strategy to procurement risk mitigation.
- Historical Baseline and Forecast Modeling: The report anchors its projections on a five-year historical dataset spanning 2020 through 2025, establishing revenue baselines, cyclical demand patterns, and technology adoption curves. These foundations feed into a forward-looking forecast extending through 2032, utilizing scenario-weighted modeling that accounts for material price volatility, capacity expansion timelines, and application-specific substitution risks.
- Segmentation by Product Architecture: A detailed breakdown by capacitor configuration examines radial leaded, surface mount, axial leaded, and other specialized formats. The analysis evaluates form-factor migration trends, mounting reliability considerations, thermal dissipation characteristics, and design-in preferences across power supply and consumer electronics applications, enabling engineering teams to align component selection with long-term manufacturing and assembly strategies.
- Application-Driven Demand Mapping: The report isolates consumption patterns across consumer electronics, automotive systems, industrial machinery, telecommunications hardware, and energy and power infrastructure. Each application vertical is evaluated through the lens of reliability thresholds, voltage and capacitance requirements, thermal stress profiles, and procurement cycles, providing procurement leaders with sector-specific sourcing frameworks and risk assessments.
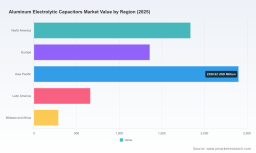
- Regional Market Dynamics: Geographic analysis covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The report evaluates regional capacity distribution, import dependency structures, local manufacturing incentives, logistics constraints, and end-market growth trajectories, enabling multinational stakeholders to optimize regional supply footprints and mitigate geopolitical or trade-related disruption risks.
- Competitive Intelligence and Strategic Positioning: The report delivers a multi-dimensional competitive assessment, mapping incumbent portfolios, technology roadmaps, regional footprint strategies, and partnership ecosystems. Rather than relying on superficial revenue rankings, the analysis evaluates design-win momentum, polymer and hybrid technology adoption rates, automotive qualification pipelines, and supply chain flexibility as indicators of future market share transfer.
- Material and Supply Chain Risk Assessment: Upstream vulnerability analysis examines etched foil production constraints, electrolyte formulation dependencies, polymer precursor availability, and lead-time sensitivity across high-reliability grades. The report integrates raw material market signals to help procurement and engineering teams anticipate pricing fluctuations, secure qualification pipelines, and diversify supplier bases ahead of demand surges.
Each section is cross-referenced with executive decision matrices, allowing readers to isolate the data streams most relevant to their functional mandates. The report avoids generic market commentary, prioritizing instead granular trend interpretation, scenario-based forecasting, and supplier evaluation frameworks designed for immediate operational deployment.
Competitive Landscape: Strategic Positioning and Innovation Vectors
The aluminum electrolytic capacitors market features a concentrated group of established manufacturers whose technological roadmaps and regional supply footprints directly influence pricing dynamics, qualification timelines, and end-market availability. Several core players define the current competitive architecture, each pursuing distinct specialization pathways that shape their strategic relevance in 2026 and beyond.
Japan remains the epicenter of electrolytic capacitor innovation, with multiple firms leveraging decades of electrolyte chemistry expertise, manufacturing precision, and automotive qualification capabilities. Leading manufacturers have expanded their portfolios to include polymer and solid variants optimized for power supplies and consumer electronics, while simultaneously advancing high-reliability grades for industrial and automotive use cases. Specialist producers continue to refine polymer-type architectures for consumer applications, emphasizing extended lifespan, lower impedance, and enhanced ripple current tolerance. Others have positioned themselves around general electronics reliability, leveraging legacy design-in relationships and volume production efficiency to maintain competitive parity in mainstream segments.
Worldwide Miniature Aluminum Electrolytic Capacitors Market
Across the Pacific, North American and European entities have strengthened their positioning through targeted technology acquisitions, polymer and organic variant development, and long-life series engineering. Major manufacturers operating under broader component conglomerates have integrated aluminum electrolytic offerings into broader passive component portfolios, utilizing organic polymer variants to address power electronics applications where thermal stability and longevity are paramount. European producers have emphasized long-life application suitability through dedicated series engineering, catering to industrial control, telecommunications, and medical-grade power supplies where failure tolerance is exceptionally low. Meanwhile, Taiwanese ownership structures have enabled global market expansion through acquired manufacturing platforms, aligning regional production capacity with international distribution networks and cross-market qualification strategies.
Recent industry activity underscores the pace of technological refinement. At NEPCON Japan 2026, notable participant initiatives highlighted precision manufacturing advancements and material qualification protocols for surface-mount aluminum electrolytic capacitors. Emphasis was placed on inline inspection methodologies, collaborative validation frameworks for long-life performance, and low ESR automotive-grade component development. These developments signal a market-wide shift toward process-controlled manufacturing, tighter tolerance verification, and application-specific qualification pathways that directly impact supplier selection criteria for automotive and industrial OEMs.
The competitive environment is further shaped by consolidation pressures and vertical integration strategies. Firms that control or secure stable access to high-purity etched foil, proprietary electrolyte formulations, and advanced winding and impregnation capabilities maintain structural advantages in cost efficiency and volume scalability. Conversely, manufacturers without secured upstream positioning face heightened exposure to lead-time volatility, pricing compression, and qualification bottlenecks during peak demand cycles. For procurement leaders and product strategists, evaluating competitor positioning requires more than revenue comparison; it demands scrutiny of technology roadmaps, automotive certification pipelines, polymer adoption trajectories, and regional supply flexibility.
Strategic Decision Implications for 2026
For executives navigating the aluminum electrolytic capacitors market in 2026, strategic decision-making must balance short-term procurement stability with long-term technology positioning. The moderate but consistent growth trajectory suggests a market that rewards disciplined supplier diversification, application-specific qualification planning, and proactive material risk management. Organizations that treat capacitor sourcing as a static purchasing function risk exposing product roadmaps to lead-time shocks, specification mismatches, and margin erosion as upstream constraints intensify.
Aluminum Electrolytic Capacitors Market
Several priority actions emerge from the broader market context. Product engineering teams should evaluate surface-mount and polymer variant integration pathways where design constraints allow, particularly for applications demanding lower ESR, extended thermal endurance, or compact form factors. Procurement leaders should establish dual-sourcing frameworks that account for regional capacity distribution, automotive qualification status, and upstream foil availability, rather than defaulting to single-vendor dependency in high-volume programs. Supply chain strategists should incorporate raw material lead-time sensitivity into inventory planning models, particularly for high-reliability automotive and industrial grades where qualification cycles are lengthy and substitution options are constrained.
Additionally, market participants should monitor technology crossover risk. While aluminum electrolytic capacitors retain clear advantages in high-capacitance, cost-effective energy storage and ripple filtering, ceramic and film alternatives continue to encroach on specific high-frequency and compact-power applications. Understanding the precise threshold at which substitution becomes economically or technologically viable requires application-level analysis that generic market commentary cannot provide. Our full report delivers the segmented modeling, competitive benchmarking, and scenario-weighted forecasts necessary to evaluate these crossover dynamics with precision.
Access the Full Strategic Intelligence
The overview presented here establishes the macro trajectory, structural dynamics, and competitive realities shaping the aluminum electrolytic capacitors market through 2032. However, the decision-grade granularity required for portfolio planning, supplier qualification, pricing strategy, and regional supply optimization resides within the complete PW Consulting research deliverable. Detailed segmentation valuations, regional demand distributions, application-specific revenue allocations, concentration thresholds, and proprietary competitive matrices are intentionally reserved for the full publication to preserve analytical exclusivity and ensure that subscribing organizations receive uncompromised strategic advantage.
Accessing the complete report enables executives and engineering leaders to convert macro awareness into targeted action: aligning component selection with application reliability thresholds, securing upstream material pathways ahead of demand tightening, evaluating competitor technology roadmaps with precision, and positioning procurement strategies to withstand lead-time volatility and pricing compression. In a market where material bottlenecks, consolidation dynamics, and automotive qualification pipelines increasingly dictate competitive outcomes, comprehensive intelligence is not a supplementary resource—it is a strategic imperative.
For organizations operating in consumer electronics, automotive systems, industrial automation, telecommunications infrastructure, or energy and power conversion, the 2026 market landscape rewards those who prepare with discipline. PW Consulting's full market research delivers the structured intelligence, scenario modeling, and competitor evaluation frameworks necessary to navigate the next phase of industry evolution with confidence.
For detailed analysis of this topic, please visit the official page: Aluminum Electrolytic Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


