



PW Consulting: Railroad Tie Market Hits $488.65M in 2025, Poised to Reach $655.95M by 2032 at 4.23% CAGR

Navigating the 2026 Railroad Tie Landscape: Strategic Intelligence for Infrastructure Leaders
The global railroad infrastructure sector stands at a critical inflection point as we enter 2026. Operators, suppliers, and investors alike are confronted with a complex matrix of aging assets, evolving environmental regulations, and shifting material preferences that will define capital allocation decisions for the next decade. Understanding the underlying market mechanics is no longer a passive exercise—it is a strategic imperative. Our latest comprehensive study on the Railroad Tie Market delivers the granular intelligence required to navigate this terrain with confidence.
Worldwide Composite Railroad Tie Market
This report is designed not merely as a statistical overview, but as a decision-support framework for executives who must balance operational reliability with long-term sustainability. By synthesizing historical performance data with forward-looking projections, the analysis equips stakeholders with the clarity needed to anticipate supply chain disruptions, evaluate competitive positioning, and align procurement strategies with emerging regulatory mandates. The insights presented here are drawn from rigorous primary research and validated industry datasets, ensuring that every recommendation rests on a foundation of verifiable market reality.
Macro Market Trajectory: Growth Anchored in Infrastructure Renewal
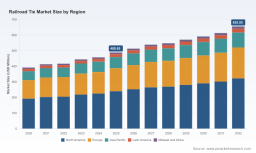
The railroad tie market has demonstrated consistent resilience over the past half-decade, driven by sustained capital expenditure on rail network maintenance and expansion. From a baseline valuation of approximately USD 392 million in 2020, the sector has advanced through a series of incremental yet meaningful increments, reaching an estimated USD 458 million by 2024 and climbing to roughly USD 489 million in 2025. This trajectory reflects a compound annual growth rate of 4.23 percent across the forecast horizon extending through 2032, positioning the market to surpass the USD 655 million threshold by the end of the projection period.
Such growth is not accidental. It is intrinsically linked to the ongoing modernization of rail infrastructure across multiple geographies, where aging wooden sleepers are gradually being replaced or supplemented by longer-lasting alternatives. The steady upward curve underscores a market that is maturing rather than experiencing volatile spikes, offering planners a predictable environment for budgetary forecasting. However, the aggregate figures only tell part of the story. Beneath the headline numbers lie nuanced shifts in material adoption, regional procurement patterns, and application-specific demand drivers that require deeper excavation to inform precise strategic moves.
Decoding Market Structure: Segment Dynamics and Material Shifts
Material Preferences in Transition
The composition of the railroad tie market reveals a clear hierarchy of material adoption, yet the edges of this hierarchy are where the most strategic opportunities reside. Traditional wooden ties continue to command a substantial share of overall revenue, reflecting their entrenched role in legacy networks and the sheer scale of ongoing replacement cycles. Concrete alternatives have carved out a significant and growing footprint, particularly in heavy-haul and high-speed corridors where durability and load-bearing capacity are non-negotiable. Steel and emerging composite solutions occupy more specialized niches, but their relevance is expanding as operators seek to mitigate decay-related maintenance costs and comply with increasingly stringent environmental standards.
What makes this material landscape particularly compelling for 2026 decision-makers is the pace at which performance expectations are evolving. Field data and industry benchmarks indicate that conventional wooden crossties typically deliver between eight and twelve years of service life in high-decay environments. By contrast, advanced composite formulations are now demonstrating operational lifespans exceeding fifty years under comparable conditions. This differential is not merely a technical footnote—it translates directly into total cost of ownership, track availability metrics, and long-term asset planning. Procurement teams that understand the cost-benefit calculus across these material categories will be better positioned to negotiate favorable terms and justify capital expenditures to internal stakeholders.
Application and Regional Nuances
Demand generation within the railroad tie ecosystem is heavily influenced by the operational profile of the end-user. Mainline passenger and freight train operations remain the dominant application driver, absorbing the bulk of annual production output. Subway and urban transit networks represent a secondary but strategically important demand channel, where space constraints, noise considerations, and rapid deployment requirements shape material selection. Beyond these core segments, specialized industrial and temporary track applications contribute incremental volume while introducing distinct specification requirements.
Geographically, the market exhibits pronounced concentration patterns that reflect historical infrastructure investment cycles, regulatory environments, and local sourcing capabilities. North America continues to represent the largest revenue contributor, underpinned by extensive Class I railroad networks and ongoing maintenance programs. Europe follows as a mature market with strong emphasis on high-speed rail modernization and environmental compliance. The Asia Pacific region, while currently smaller in absolute terms, presents dynamic growth potential tied to expanding rail corridors and urban transit development. Latin America and the Middle East/Africa markets, though more modest in scale, offer targeted opportunities for suppliers that can navigate localized logistics and specification requirements. Detailed regional and application breakdowns are mapped comprehensively within the full report to enable precise market-entry and expansion planning.
Competitive Landscape: Incumbents, Innovators, and Strategic Moves
Established Players and Supply Chain Anchors
The competitive architecture of the railroad tie market is characterized by a mix of large-scale manufacturers, specialized treatment providers, and national distributors. Firms such as Koppers Inc. and Stella-Jones Inc. have long anchored the North American supply chain, leveraging extensive sawmill sourcing networks and pressure-treatment capabilities to serve Class I, regional, and short-line railroads. Their scale and established relationships provide a baseline of supply reliability that network operators depend upon for routine replacement programs.
On the concrete and composite side, Vossloh AG has built a global reputation for prestressed concrete ties and synthetic sleepers tailored to heavy-haul and high-speed applications. L.B. Foster Company, through its concrete product subsidiary, holds a significant share of the North American concrete tie supply, reinforcing the material's growing relevance in mainline infrastructure. Gross & Janes Corporation and Nisus Corporation contribute specialized pressure-treated wood solutions, with the latter emphasizing copper naphthenate formulations designed to extend service life in demanding field conditions. These companies illustrate how incumbent players are adapting their portfolios to address both traditional performance expectations and emerging longevity requirements.
Innovation Entrants and Sustainability-Driven Investment
A distinct cohort of composite-focused manufacturers is reshaping the competitive perimeter by targeting the intersection of durability and environmental stewardship. TieTek LLC, operating under Axion International, specializes in composite ties manufactured from recycled materials, offering sustainable alternatives that reduce reliance on virgin timber and creosote-based treatments. Evertrak has similarly positioned itself in the recycled-plastic and fiberglass composite space, with its flagship models engineered for extended lifespans in high-decay zones. IntegriCo Composites Inc. expands this segment further by producing composite railroad ties from recycled feedstocks across dedicated manufacturing facilities.
Railroad Tie Market
Strategic capital flows are reinforcing this innovation axis. In early 2025, Sumitomo Corporation of Americas announced a strategic investment and formalized partnership with Evertrak to support production scalability and expand sustainable composite tie manufacturing for North American railroads. Such moves signal growing institutional confidence in composite technologies and suggest that financing environments are increasingly favorable for manufacturers that can demonstrate both performance superiority and circular-economy alignment. Additionally, broad-line suppliers such as A&K Railroad Materials, Inc. and POHL Railroad Materials Corporation LLC continue to play essential roles in distribution and sourcing, maintaining comprehensive catalogs of new and used ties that support diverse procurement needs across the network.
Market Concentration and Competitive Implications
The competitive dynamics of the railroad tie market are further contextualized by its concentration profile. With the top three firms accounting for approximately 21.5 percent of market revenue and the top five reaching roughly 24.8 percent, the sector exhibits a moderately fragmented structure. This configuration carries strategic implications: while no single entity dominates outright, established players benefit from scale advantages in treatment capacity, distribution networks, and long-term contracting leverage. Meanwhile, niche innovators can pursue differentiation through material performance, sustainability credentials, and specialized application targeting. For buyers, this balance means that supplier diversification, qualification processes, and performance benchmarking are essential to securing both cost competitiveness and supply resilience.
Regulatory and Operational Currents Shaping 2026 Strategy
Performance Standards and Environmental Compliance
Regulatory evolution is becoming a decisive force in material specification and disposal practices. In August 2025, the U.S. Federal Railroad Administration developed performance-based specifications for concrete railroad tie freeze-thaw durability, a move designed to ensure track longevity and tighten manufacturing process control. This specification framework directly influences procurement standards, quality assurance protocols, and supplier qualification criteria for concrete tie programs across North American networks.
Environmental considerations are simultaneously reshaping the end-of-life landscape for treated wood ties. The U.S. Department of Transportation's Federal Railroad Administration issued a request for information in 2023 examining potential uses and options for the disposal or repurposing of used creosote-treated railroad ties, reflecting broader concerns about hazardous substance management. At the state level, New Hampshire's Department of Environmental Services implemented requirements in September 2025 mandating proper disposal options for creosote-treated ties to prevent environmental release. These regulatory threads collectively push operators and suppliers toward more transparent disposal pathways, extended service life solutions, and alternative materials that reduce long-term environmental liability.
Raw Material Capacity and Supply Realism
On the supply side, industry capacity data provides important context for procurement planning. Railroad crossties account for the majority of North American wood tie production capacity, which exceeds 24 million units annually, while current industry output stands at just over 19 million ties. This gap between nameplate capacity and realized output highlights both latent production potential and the operational constraints—labor availability, raw material logistics, treatment facility throughput—that influence actual delivery timelines. For network planners, understanding this capacity dynamic is essential when forecasting replacement schedules, negotiating supply agreements, and modeling cost trajectories under varying operational scenarios.
Strategic Takeaways for 2026 Decision-Makers
The railroad tie market in 2026 rewards organizations that approach procurement and investment through a multi-dimensional lens. Several strategic priorities emerge from the current landscape:
- Align material selection with total cost of ownership rather than upfront unit pricing, factoring in service life differentials, maintenance frequency, and disposal compliance costs.
- Evaluate supplier portfolios for both scale reliability and innovation capability, recognizing that established treatment and manufacturing networks remain critical while composite and sustainability-focused entrants are gaining traction.
- Incorporate regulatory developments into specification frameworks early, particularly performance-based durability standards and environmental disposal mandates that will influence eligibility, reporting, and liability exposure.
- Monitor capacity utilization and regional sourcing dynamics to anticipate lead-time variability and identify opportunities for dual-sourcing or localized supply partnerships.
- Leverage strategic investment activity as a signal of where institutional capital is converging, using partnership and funding announcements to inform competitive benchmarking and technology adoption roadmaps.
These considerations are not isolated tactics; they form an integrated approach to navigating a market where material performance, regulatory pressure, and supply chain realism intersect. Organizations that embed these priorities into their planning cycles will be better equipped to manage risk, capture efficiency gains, and position their rail infrastructure assets for long-term operational excellence.
Accessing the Full Strategic Intelligence
The insights summarized here represent a high-level orientation to the railroad tie market's structure, dynamics, and strategic levers. Yet the depth required for enterprise-level decision-making extends well beyond aggregate trends. The complete report delivers detailed segment-level revenue trajectories, application-specific demand breakdowns, regional procurement analyses, and granular competitive profiling that enable precise market-entry assessments, supplier negotiations, and capital planning. It also maps the interplay between regulatory timelines and material adoption curves, offering scenario-based frameworks that help leaders stress-test procurement strategies against evolving compliance requirements and performance expectations.
For executives and strategy teams preparing for 2026 and the forecast window through 2032, the full study provides the empirical foundation necessary to convert market awareness into actionable advantage. To access the complete dataset, competitive deep-dives, and operational recommendation frameworks, we invite you to explore the full report through our official publication channel. There, you will find the detailed tables, methodology notes, and scenario analyses that transform these strategic themes into executable intelligence tailored to your organization's specific rail infrastructure objectives.
For detailed analysis of this topic, please visit the official page: Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


