



PW Consulting: Multi-Functional Cooking Food Processors Hit $3.38B in 2025, 5.88% CAGR to 2032

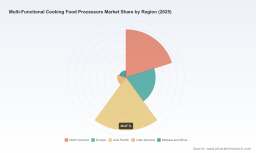
Navigating the Multi-Functional Cooking Food Processors Market: Strategic Insights for 2026 Decision-Making
The modern kitchen has evolved from a simple preparation space into a hub of technological integration, where efficiency, versatility, and smart functionality converge. As household consumers and commercial operators alike seek to streamline food preparation workflows, the multi-functional cooking food processor segment has emerged as a critical battleground for appliance manufacturers. This article serves as a strategic preview of the latest PW Consulting market study, designed to equip executives, product managers, and investment analysts with the analytical frameworks needed to navigate the 2026–2032 forecast period. While this overview establishes the macro trajectories and competitive undercurrents shaping the sector, the complete intelligence—including granular segmentation breakdowns, pricing elasticity models, and supplier-tier mapping—resides within the full report.
The Macro Trajectory: A Decade of Measured Expansion
The multi-functional cooking food processor market has demonstrated consistent, compounding growth over the past five years, reflecting a structural shift rather than a transient consumer trend. Historical revenue data from 2020 through 2025 reveals a steady upward curve, as the global market expanded from approximately 2,538 million USD to a projected 3,378 million USD at the close of the base year. This trajectory has been underpinned by broadening appliance adoption, rising disposable incomes in emerging economies, and an increasing consumer preference for space-efficient, multi-tasking kitchen equipment.
Looking forward, the forecast period extending through 2032 indicates sustained momentum. The market is projected to breach the 3,500 million USD threshold in 2026 and accelerate toward the 5,000 million USD mark by the end of the decade. This expansion is anchored by a forecast compound annual growth rate of 5.88 percent, a figure that signals healthy, above-inflation demand across both mature and developing regions. For corporate strategists, this CAGR is not merely a statistical projection; it represents a window of opportunity for product portfolio optimization, supply chain reconfiguration, and targeted geographic penetration. The years ahead will reward firms that can balance volume growth with margin preservation, particularly as input costs and regulatory compliance requirements continue to reshape manufacturing economics.
Market Architecture and Structural Dynamics
Understanding the architecture of this market requires moving beyond headline revenue figures and examining the underlying demand drivers. The industry is characterized by a moderate degree of concentration, with the top three participants collectively commanding roughly 48.5 percent of total industry revenue, while the top five firms extend their combined share to approximately 52.0 percent. This concentration profile suggests a market that is neither fragmented nor monopolistic, but rather one where established incumbents maintain strong brand equity while leaving ample room for niche innovators and regional specialists to capture value through differentiated features or localized distribution networks.
Product design philosophy has increasingly shifted toward all-in-one functionality. The integration of guided smart cooking, precision blending, automated chopping, steaming, and slow-cooking capabilities into single units has fundamentally altered purchasing behavior. Industry utilization data indicates that multi-functional processors achieve an average household utilization rate exceeding 65 percent, a metric that underscores the tangible value proposition of consolidated appliance ecosystems. Consumers are no longer buying isolated tools; they are investing in kitchen workstations that reduce countertop clutter, minimize accessory swaps, and streamline recipe execution. This behavioral shift has direct implications for product engineering roadmaps, warranty cost structures, and after-sales service expectations.
Capacity segmentation remains a critical dimension of consumer and commercial decision-making. The market accommodates a spectrum of volume requirements, ranging from compact units designed for everyday household chopping and mixing, to mid-tier configurations that balance batch flexibility with storage footprint, and finally to larger-capacity systems tailored for high-volume meal preparation. Each tier serves distinct use cases, and the strategic allocation of research and development resources across these capacity bands will determine which manufacturers can effectively capture cross-segment demand without diluting brand positioning.
Strategic Imperatives for 2026 Enterprise Decision-Making
As organizations plan their 2026 product launches, capacity expansions, and market-entry initiatives, several strategic imperatives emerge from the broader market context. First, the convergence of hardware engineering and software-guided culinary workflows demands cross-functional collaboration between mechanical design teams, embedded systems developers, and recipe content creators. Firms that treat smart cooking guidance as a premium differentiator rather than a marketing afterthought will likely secure stronger customer retention and higher average selling prices.
Second, pricing architecture must be calibrated against evolving consumer willingness to pay. Premium multi-functional processors from leading innovators command retail prices that sit 40 to 50 percent above basic models, a premium justified by integrated electronics, precision engineering, and extended functionality. However, this pricing gap also creates a two-tier market dynamic. Mass-market consumers continue to seek reliable, compact units that deliver core chopping, shredding, and mixing capabilities at accessible price points, while enthusiast and premium segments prioritize advanced dicing meshes, wider feed chutes, and guided programming. Successful portfolio strategies will require clear tiering, distinct feature roadmaps, and disciplined channel management to prevent cannibalization.
Multi-Functional Cooking Food Processors Market
Third, compliance and certification have transitioned from back-office obligations to competitive advantages. In the European Union, mandatory CE marking verification remains a prerequisite for retail listing, and leading manufacturers have aligned their products with EU Low Voltage and EMC directives to ensure consumer safety and electromagnetic compatibility. Simultaneously, household kitchen appliances in key export markets are increasingly evaluated against NSF International food-contact material standards. Companies that proactively embed compliance into their design cycles reduce time-to-market friction, minimize regulatory risk, and strengthen retailer confidence. For 2026 planning, compliance readiness should be treated as a strategic enabler rather than a procedural checkpoint.
Competitive Landscape: Incumbents, Innovation Pace, and Differentiators
The competitive field is anchored by a diverse set of multinational appliance manufacturers, each leveraging distinct brand heritage, engineering philosophies, and distribution strengths. Vorwerk, headquartered in Germany, continues to lead the premium segment with its Thermomix lineage, including the TM6 and the recently introduced TM7. The TM7's global rollout in early 2025 reinforced Vorwerk's emphasis on guided smart cooking, blending, chopping, steaming, and slow-cooking within a single integrated device. This holistic approach has cultivated a dedicated user base and positioned the brand as a reference point for smart culinary ecosystems.
Cuisinart, based in the United States, maintains a strong presence through customizable capacity options, including the Custom 14-Cup and Pro Classic 7-Cup configurations. Its product architecture emphasizes chopping, slicing, shredding, and mixing versatility, appealing to consumers who value modular flexibility and recognizable brand reliability. Breville, an Australian manufacturer, has pursued a performance-oriented strategy with its Sous Chef 16 and Sous Chef 9 lines, and in mid-2026 expanded its lineup with the Paradice 9 and Paradice 16 models. These updates introduced wide dicing meshes and extended feed chutes, reflecting a continued focus on precision dicing and throughput efficiency.
KitchenAid contributes to the competitive mosaic through its KFP series, which targets versatile chopping, mixing, and food preparation tasks with a strong emphasis on brand familiarity and kitchen integration. Ninja, also American, has capitalized on everyday utility with its Professional Plus and related models, emphasizing accessible chopping, shredding, and mixing performance for routine household use. Magimix, from France, caters to users seeking professional-grade chopping, slicing, and dough handling, often positioning its 14-Cup configurations as durable, high-performance workhorses. Hamilton Beach addresses the value-conscious segment with compact, easy-assembly designs such as its 12-Cup Stack & Snap line, prioritizing daily food prep convenience and straightforward operation. TAURUS Group, headquartered in Spain, extends its reach through versatile attachments that serve both household and light commercial applications, while Tefal rounds out the competitive field with processors that support chopping, mixing, and general preparation functions.
This competitive diversity creates both opportunities and risks. On one hand, the breadth of design philosophies allows consumers to align purchases with specific kitchen constraints, culinary habits, and budget parameters. On the other hand, it intensifies the need for clear value communication, consistent quality control, and differentiated after-sales support. Firms that invest in user education, recipe ecosystems, and service network reliability will be better positioned to defend market share as feature parity increases across mid-tier segments.
Regulatory, Labor, and Consumer Habit Pressures Shaping the Next Cycle
Beyond product design and competitive positioning, several macro-level pressures will influence market behavior throughout the forecast period. Regulatory compliance remains a persistent operational consideration, particularly for manufacturers exporting across multiple jurisdictions. The requirement for CE marking verification prior to retail listing in the EU, coupled with NSF International food-contact material certifications for household kitchen appliances, establishes a baseline of safety and material integrity that retailers and consumers increasingly expect. Companies that treat these standards as strategic safeguards rather than administrative hurdles will experience fewer supply chain disruptions and faster market access.
Labor cost dynamics and premium pricing structures also warrant attention. As integrated electronics, precision engineering, and smart cooking guidance become more prevalent in premium models, manufacturing complexity rises. This complexity is reflected in retail pricing, with premium units commanding a significant premium over basic alternatives. For 2026 planning, manufacturers must evaluate whether the cost of advanced feature integration can be offset by higher margin capture, reduced return rates, or expanded service revenue streams. Simultaneously, mass-market segments will continue to pressure supply chain efficiency, requiring leaner component sourcing and more scalable assembly processes.
Consumer habit data further reinforces the strategic importance of utilization and satisfaction. The observed average household utilization rate above 65 percent indicates that multi-functional processors are not merely occasional-use gadgets but central components of daily kitchen routines. This pattern suggests that product reliability, ease of cleaning, attachment durability, and software consistency will heavily influence repeat purchase behavior and word-of-mouth advocacy. Brands that prioritize post-purchase experience—through intuitive interfaces, clear maintenance guidance, and responsive warranty support—will likely see stronger lifetime value metrics.
Inside the PW Consulting Market Study: What Decision-Makers Will Find
The complete PW Consulting Multi-Functional Cooking Food Processors Market study is structured to translate macro trends into actionable intelligence. The report opens with a detailed historical reconstruction covering the 2020–2025 period, establishing baseline demand patterns, regional growth rhythms, and capacity-tier performance. From there, the analysis extends through the full 2026–2032 forecast horizon, providing forward-looking revenue trajectories, structural inflection points, and scenario-based sensitivity considerations.
The segmentation framework examines market behavior across multiple dimensions without reducing complexity to oversimplified ratios. Readers will find granular analysis of regional demand characteristics, product capacity preferences, and application-driven usage patterns, all contextualized within broader macroeconomic and consumer behavior trends. The competitive landscape section goes beyond company profiling to evaluate strategic positioning, feature differentiation, pricing architecture, and recent product launch cadence. Regulatory and compliance dynamics are mapped to specific market entry requirements, while labor cost and premium pricing pressures are analyzed in relation to margin sustainability and portfolio tiering.
Importantly, the study integrates real-world product development milestones, including recent launch activity and model updates, to illustrate how incumbents are adapting to shifting consumer expectations. These case-level observations are paired with industry habit data, utilization patterns, and certification requirements to create a multidimensional view of market evolution. The report also provides strategic recommendations for product planning, channel optimization, compliance readiness, and competitive response, enabling executives to align 2026 initiatives with measurable market opportunities.
Kitchen Food Garbage Processors Market
Conclusion: Turning Market Intelligence into 2026 Advantage
The multi-functional cooking food processor market is entering a phase where growth is no longer guaranteed by broad appliance adoption alone. Sustained expansion will depend on product differentiation, compliance agility, pricing discipline, and a deep understanding of how consumers actually use these devices in daily routines. The forecast CAGR of 5.88 percent and the projected revenue progression toward 5,039 million USD by 2032 outline a promising trajectory, but capturing share within that trajectory requires more than top-line optimism.
This article has outlined the strategic contours of the market: the concentration dynamics, the premium-versus-mass segmentation tension, the regulatory and certification expectations, and the competitive diversity that defines the sector. Yet the full depth of the analysis—segment-level revenue splits, application-specific demand drivers, regional growth nuances, and detailed competitor benchmarking—remains within the complete PW Consulting report. For executives preparing 2026 product launches, supply chain adjustments, or market-entry strategies, the full study provides the structured intelligence needed to move from awareness to action. The next step is to access the complete market intelligence and translate these macro insights into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Multi-Functional Cooking Food Processors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


