



PW Consulting: Padlock Market Reaches $2B in 2025, 5.9% CAGR ≈ $3.1B by 2032

Strategic Insights: The Padlock Market Trajectory and Decision Framework for 2026
The global security hardware landscape is undergoing a structural transformation, and nowhere is this more evident than in the padlock market. As organizations recalibrate their physical security postures in response to evolving regulatory environments, supply chain volatility, and rising threat vectors, the padlock sector has emerged as a critical barometer of industrial resilience and commercial confidence. This article serves as a strategic preview of our latest comprehensive market research, designed to equip executives, procurement leaders, and security architects with the analytical rigor required to navigate the forecast period from 2026 through 2032.
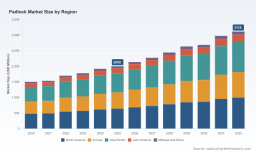
Over the past half-decade, the market has demonstrated a consistent upward trajectory, recovering from the contractionary pressures of the early 2020s and establishing a robust growth foundation. Total market revenue reached approximately USD 2.137 billion in 2026, reflecting a compound annual growth rate of 5.9 percent across the forecast horizon. This expansion is not merely a function of post-pandemic normalization; it is driven by foundational shifts in how businesses and institutions approach asset protection, regulatory compliance, and operational continuity. Understanding these underlying currents is essential for any organization seeking to optimize capital allocation, mitigate supply chain exposure, and align security procurement with long-term strategic objectives.
Macroeconomic Foundations and Growth Catalysts
The revenue progression from 2020 through 2025 tells a story of adaptive resilience. After starting at roughly USD 1.502 billion in 2020, the market expanded steadily, surpassing the USD 2.0 billion threshold by 2025. This growth has been underpinned by sustained demand across commercial security deployments, residential protection upgrades, and industrial applications where lockout/tagout protocols and heavy-duty access control remain non-negotiable. The forecast period extending to 2032 projects a market valuation approaching USD 3.116 billion, signaling that the sector has moved beyond cyclical recovery into a phase of structural expansion.
Padlock Market
Several interlocking factors are accelerating this trajectory. First, the modernization of physical security infrastructure in mid-market commercial real estate and logistics facilities is creating consistent replacement and upgrade cycles. Second, residential security spending has matured beyond basic deterrent models toward integrated, higher-tolerance hardware that complements smart home ecosystems. Third, industrial and institutional buyers are increasingly standardizing on certified, auditable locking solutions that satisfy insurance requirements and occupational safety mandates. These demand drivers are compounding, and they interact with macroeconomic variables that our research quantifies through scenario-based modeling and sensitivity analysis.
Regulatory and Supply Chain Dynamics Shaping Procurement Strategy
The padlock market does not operate in a vacuum. Recent regulatory interventions have introduced new cost structures and compliance considerations that directly influence manufacturing economics and downstream pricing. The Department of Commerce initiated the Section 232 Steel and Aluminum Inclusions Process in April 2025, with determinations issued within a 60-day window. This action has had immediate implications for raw material inputs, particularly for steel-bodied and laminated padlocks prevalent in construction, industrial, and municipal applications. Subsequent expansions to the tariff list in August 2025 added hundreds of product categories to the steel and aluminum duty framework, raising component costs and reinforcing the need for strategic sourcing flexibility.
Lock Market
Simultaneously, the Harmonized Tariff Schedule underwent revision in 2026, with updated classifications for imported padlocks affecting duty calculations for manufacturers supplying North American and broader US channels. These classification adjustments require procurement teams to reassess landed cost models, evaluate alternative supplier geographies, and consider inventory timing strategies that account for duty volatility. Our research maps these regulatory touchpoints against pricing elasticity and supply chain reconfiguration scenarios, providing decision-makers with a structured view of how policy shifts translate into operational risk and opportunity.
On the standards side, the CEN classification framework continues to serve as the authoritative reference for security ratings across global markets. Manufacturers such as ABUS maintain active alignment with BS EN12320 testing protocols, which define low, medium, and high security tiers. Commercial insurers, facility managers, and government procurement offices increasingly reference these ratings during vendor selection, making certification status a strategic differentiator rather than a passive compliance checkbox. Understanding which manufacturers have sustained validated ratings, and how those ratings map to end-use risk profiles, is a recurring theme throughout our analysis.
Competitive Architecture: incumbents, specialists, and the certification moat
The competitive landscape is characterized by a mix of globally scaled manufacturers, family-owned specialists, and regional players that compete on distinct value propositions. Concentration metrics indicate that the top three firms command approximately 55 percent of market revenue, while the top five collectively hold around 62 percent. This level of concentration suggests that scale advantages in distribution, certification portfolios, and OEM integration are meaningful, yet ample room remains for differentiated players to capture niche demand through specialized product architectures and relationship-driven channels.
Within this architecture, several manufacturers have established recognizable positions. Master Lock Company LLC operates a broad portfolio spanning combination, laminated, high-security, lockout/tagout, and smart-connected models, serving home, commercial, and industrial channels with a globally recognized distribution footprint. Wilson Bohannan Lock Company LLC, a seventh-generation family enterprise, has built its reputation on solid brass construction, high-security interchangeable core designs, and door-key compatible configurations tailored for utility, industrial, military, and government deployments. ABUS August Bremicker Söhne KG maintains a strong European and global presence in premium padlock segments, with particular relevance in commercial, industrial, and safety applications where certified security ratings carry weight.
In the North American manufacturing base, Pacific Lock Company has drawn attention through its focus on government-standard field service hardware and medium-to-low security padlocks for military and Department of Defense applications. Its recent achievement of Department of Defense approval for the PL951 high-security padlock, following successful certification under MIL-DTL-43607J, positioned it as the first and only US manufacturer certified to all three military padlock grades. This milestone illustrates how certification depth can function as a competitive moat, particularly in segments where procurement specifications are stringent and substitution is limited. Wilson Bohannan and other US-based specialists similarly emphasize interchangeable cores, custom OEM solutions, and utility-grade durability, expanding the menu of options available to buyers who require traceable supply chains and configurable hardware.
Asian manufacturers contribute additional capacity and product diversity. SINOX, for example, produces heavy-duty key and combination padlocks targeting school, gym, toolbox, club, and industrial locker environments, with resettable and key override features that address practical operational needs. Federal Lock Company and other regional producers supply padlocks tailored to security and industrial requirements, broadening the supplier base for cost-sensitive and application-specific deployments. Meanwhile, Brady Corporation reinforces the lockout/tagout safety segment, providing safety padlocks and employee protection solutions that intersect physical security with occupational health compliance. These varied profiles underscore a market where segmentation by material, mechanism, security tier, and end-use application creates multiple distinct playing fields rather than a single commoditized arena.
Report Scope: Operational Intelligence for Procurement and Strategy Teams
Our research is structured to move beyond headline figures and deliver actionable intelligence across the dimensions that matter most to enterprise decision-making. The report opens with a detailed market sizing framework that traces historical revenue performance and projects forward through the forecast period, enabling readers to benchmark their own growth assumptions and identify divergence points between macro trends and segment-level behavior. Revenue models are expressed in millions of USD and are accompanied by scenario analysis that accounts for regulatory cost impacts, material price volatility, and demand elasticity across application categories.
A central component of the study is the segmentation architecture, which disaggregates revenue by type, application, and geographic region. This framework is designed to help procurement and product strategy teams understand where value concentrates, which sub-segments exhibit higher growth momentum, and how regional demand patterns interact with manufacturing and logistics footprints. The analysis also examines material composition trends, including the relative positioning of steel, brass, and other body constructions, alongside mechanism differentiation that ranges from traditional keyed systems to rotating disc cylinder technologies and smart-connected variants. These structural insights are paired with qualitative assessment of how certification status, insurance alignment, and OEM integration influence share dynamics.
The competitive profiling section extends beyond descriptive summaries. Each key enterprise is evaluated across manufacturing capability, certification portfolios, channel reach, and recent strategic moves that signal shifting priorities. The report captures notable developments such as military-grade certification achievements, trade show participation that signals market expansion intent, and product-line extensions that address emerging use cases. By contextualizing these events within broader industry cycles, the analysis helps readers distinguish between one-off announcements and structural shifts that warrant attention in sourcing and partnership decisions.
In addition, the study integrates a regulatory and standards watch module that tracks tariff classifications, trade policy adjustments, and testing standards that affect compliance and cost. This module is intended for teams that need to anticipate changes before they impact landed costs or vendor eligibility. The report also includes a framework for evaluating supplier risk, covering concentration exposure, geographic dependency, and the implications of raw material tariff regimes for steel and aluminum-intensive product lines. Together, these components form a decision-support toolkit rather than a static market snapshot.
Strategic Implications for 2026 and Beyond
For executives navigating 2026, the padlock market presents a clear mandate: treat physical security hardware as a strategic input rather than a commoditized purchase. Several implications follow directly from the data and dynamics outlined in our research.
- Certification alignment is a procurement accelerator. Buyers whose specifications reference recognized security ratings and military or industrial certifications can streamline vendor qualification, reduce substitution risk, and strengthen audit readiness. Manufacturers with validated certifications across multiple tiers are better positioned to support regulated environments and insurance-driven compliance requirements.
- Material cost volatility demands sourcing diversification. Recent tariff developments around steel and aluminum content have reshaped cost structures for laminated and steel-bodied padlocks. Organizations should evaluate multi-source strategies, alternative material configurations where operationally acceptable, and inventory planning that accounts for duty cycles and classification updates.
- Segment strategy should match risk profile to product architecture. Commercial security, residential protection, and industrial applications each impose distinct performance, durability, and compliance expectations. A portfolio approach that aligns product selection with end-use risk, rather than defaulting to uniform specifications, yields better total cost of ownership and fewer downstream failures.
- Competitive concentration creates both stability and opportunity. While a concentrated top tier provides established distribution and certification depth, specialized manufacturers continue to compete effectively through customization, OEM integration, and niche certification portfolios. Evaluating both scale players and specialists enables buyers to balance reliability with flexibility.
- Standards and classification monitoring should be institutionalized. Changes to tariff schedules, testing standards, and security rating frameworks can alter vendor eligibility and landed costs. Embedding regulatory surveillance into procurement workflows reduces surprise and supports more resilient contracting terms.
The market is not merely growing; it is evolving in ways that reward organizations who can read the interplay between regulation, material economics, certification, and application-specific demand. Our research is designed to make that interplay legible, providing the analytical scaffolding needed to convert market intelligence into procurement strategy, capital planning, and risk mitigation.
Accessing the Full Intelligence Package
This article has outlined the strategic contours of the padlock market and highlighted the decision frameworks that our latest research brings into focus. The complete study goes further, delivering the granular segmentation detail, competitive benchmarking, scenario models, and regulatory tracking that enterprise teams require to move from awareness to action. Core figures, segment-level revenue splits, regional demand patterns, and application-specific growth breakdowns are available in the full report, alongside detailed profiles of the manufacturers shaping the competitive landscape and an expanded view of the regulatory developments influencing cost and compliance.
For decision-makers ready to translate market dynamics into concrete sourcing, pricing, and portfolio choices, the full research package provides the depth and specificity needed to sharpen strategy across the 2026 to 2032 horizon. We invite you to access the complete report to explore the segmentation architecture, competitive analysis, and scenario frameworks that underpin the insights summarized here.
For detailed analysis of this topic, please visit the official page: Padlock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


