



PW Consulting: Retail Shelving Systems Market Hits $2.64B in 2025, Projects 9.2% CAGR to 2032

Strategic Shelf Space: Navigating the 2026 Retail Shelving Systems Market
The physical storefront remains a critical battleground for consumer brands, even as digital channels expand. While e-commerce captures headlines, the in-store experience continues to drive impulse purchases and brand loyalty, making the infrastructure behind the merchandise more vital than ever. At the center of this infrastructure lies the retail shelving system. It is no longer mere storage; it is a strategic tool for inventory management, visual merchandising, and customer flow optimization. As we move through 2026, understanding the trajectory of this market is essential for stakeholders looking to capitalize on evolving retail dynamics.
This article serves as a strategic overview based on our latest comprehensive research into the Retail Shelving Systems Market. It highlights the macro-economic shifts, competitive pressures, and structural trends defining the industry. However, to maintain the integrity of our proprietary analysis and provide actionable precision for your specific business case, detailed segmentation data and granular forecast figures are reserved for the full report. The following insights are designed to contextualize the opportunity and demonstrate why deep-dive intelligence is necessary for informed capital allocation in the coming years.
Market Trajectory and Economic Context
The retail shelving systems sector has demonstrated remarkable resilience and growth over the past half-decade. Analyzing the historical performance from 2020 through 2025 reveals a consistent upward trend, driven by store expansions, renovations, and the replacement of legacy fixtures with more efficient, modular solutions. The industry has successfully navigated supply chain disruptions and material cost volatility, emerging with a strengthened value proposition centered on durability and flexibility.
Looking ahead, the forecast period from 2026 to 2032 indicates sustained momentum. Our analysis projects a compound annual growth rate (CAGR) of 9.2% throughout this horizon. This growth is not merely a function of inflation or nominal price increases but reflects genuine demand expansion across multiple retail verticals. The total market revenue is expected to scale significantly, crossing substantial thresholds by the end of the decade. For enterprise planners, this trajectory suggests that shelving systems should be viewed as a growth-adjacent investment rather than a maintenance cost. The increasing value of the total addressable market implies greater competition for shelf space, higher standards for fixture quality, and a premium on systems that can adapt to changing planograms without costly retrofits.
It is important to note that while the aggregate numbers paint a picture of robust health, the distribution of this value varies by deployment type, application, and geography. Understanding where the highest value density lies requires a nuanced look at how different retail formats are prioritizing their physical infrastructure. For instance, the shift towards high-density merchandising in certain sectors contrasts with the open, experiential setups preferred in others. Our full research delineates these splits with precision, allowing clients to benchmark their regional or segment-specific performance against the broader market reality.
Operational Dynamics and Segmentation Insights
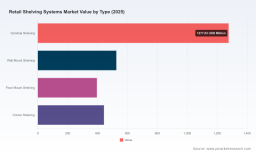
The market is structurally divided by system type, application, and geographic region, each presenting unique challenges and opportunities. In terms of system architecture, gondola shelving continues to dominate the landscape due to its versatility and standardized integration into grid layouts. However, wall-mount and floor-mount solutions are seeing renewed interest in specialty stores and spaces where perimeter optimization is critical. Corner shelving also represents a significant portion of the mix, addressing the inefficiencies of traditional straight-run aisles in varied store footprints.
By application, supermarkets and hypermarkets remain the heavyweights, consuming the largest share of system deployments due to their high SKU counts and volume-driven models. Yet, apparel stores and specialty retail segments are increasingly investing in higher-specification fixtures that support brand elevation and interactive displays. The distinction here is crucial: a supermarket requires durability and ease of restocking, whereas a specialty boutique may prioritize aesthetics and modularity to facilitate seasonal theme changes. These differing needs drive distinct purchasing behaviors and vendor relationships.
Geographically, the market reflects mature infrastructure in North America and Europe, where replacement cycles and upgrades drive demand. Meanwhile, Asia Pacific and other emerging regions offer growth potential tied to modern retail expansion and the formalization of grocery sectors. Each region carries its own regulatory, logistical, and cultural nuances that impact product specification and deployment speed. A one-size-fits-all strategy is rarely effective. Our detailed regional analysis provides the granularity needed to assess market entry barriers, competitive intensity, and localized demand drivers without relying on broad generalizations.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of established legacy manufacturers and agile specialists. The top tier of the market exhibits moderate concentration, with the top three players holding a significant share, and the top five expanding that footprint further. This concentration suggests that scale advantages in manufacturing, distribution, and R&D are becoming increasingly important. However, the presence of numerous specialized competitors indicates that niche expertise and customization capabilities still command loyalty and pricing power.
Several key companies define the current strategic landscape. Lozier Corporation, based in Omaha, Nebraska, stands as a leading manufacturer of modular gondola shelving systems and custom retail fixtures. With over 70 years of vertically integrated production, they serve grocery, pharmacy, and general merchandise retailers, emphasizing supply chain control and consistent quality. Their longevity suggests a strong capability in managing large-scale deployments and adhering to stringent retailer specifications.
Madix Inc., headquartered in Terrell, Texas, focuses on custom-configurable retail display fixtures and shelving systems. Their offering emphasizes sustainability and broad accessory integration, targeting supermarket and convenience store applications. In an era where environmental compliance and waste reduction are becoming procurement criteria, Madix positions itself as a forward-thinking partner for retailers looking to align their physical infrastructure with corporate sustainability goals.
Uniweb Inc., located in Corona, California, has been manufacturing high-density pharmacy and retail shelving since 1970. Their specialization in steel construction for pharmacies and general merchandise highlights a focus on durability and space optimization in high-value product categories. For retailers dealing with sensitive or high-theft items, the structural integrity and security features of such systems are paramount.
Retail Shelving Systems Market
Continental Store Fixture Group operates out of Canada, providing commercial-grade retail shelving and modular fixtures for grocery, pharmacy, hardware, and specialty retail across Canada and the US. Their value proposition includes in-stock inventory and CAD-based store planning, which reduces lead times and streamlines the design process for store planners. Speed to market is a critical differentiator in an industry where store openings and remodels are often scheduled tightly.
DGS Retail, based in Chicago, Illinois, has been a manufacturer and supplier since 1979, offering gondola and display solutions for various retail formats. Their long history implies a deep understanding of evolving retail trends and the ability to adapt product lines to changing consumer behaviors. Similarly, Shelving Depot serves as a provider of retail store shelving solutions across multiple industries, with an emphasis on quality and customization, catering to clients who need flexible specifications without sacrificing structural standards.
Gershel Brothers, located in Philadelphia, Pennsylvania, supplies new and used store fixtures, including gondola shelving and display accessories. Their inclusion of used fixtures introduces a cost-optimization angle to the market, appealing to budget-conscious retailers or those seeking temporary setups. STM Display Sales Inc. acts as a one-stop source for retail merchandising fixtures and store design, leveraging over 30 years of experience to offer integrated solutions that go beyond just hardware.
Worldwide Boltless Shelving Market
LA Darling, based in Albert Lea, Minnesota, manufactures retail merchandising and display systems, including gondola shelving. Following their post-2020 merger integration, they have focused on delivering custom solutions, suggesting a strategic move towards higher-value, tailored offerings rather than commoditized products. Trion Industries and Storflex Fixture Corporation round out the landscape with focuses on display and shelving integration and durable retail fixtures emphasizing quality and efficiency, respectively. These players ensure that the market remains dynamic, with continuous pressure on innovation and cost-effectiveness.
Industry Dynamics and Decision Drivers
The industry is currently influenced by several macro and micro dynamics that planners must account for. First, the emphasis on omnichannel fulfillment is reshaping store layouts. Stores are increasingly serving as fulfillment centers for online orders, requiring shelving systems that can accommodate pick zones, secure storage, and efficient retrieval processes without compromising the customer experience. This dual-use requirement adds complexity to fixture selection and layout planning.
Second, sustainability and material sourcing are moving from nice-to-have to mandatory. Retailers are under pressure to reduce their carbon footprint and waste. This influences the materials used in shelving systems, the longevity of the fixtures, and the ease of recycling or refurbishing old units. Suppliers who can provide certified sustainable materials or take-back programs may gain a competitive edge in procurement negotiations.
Third, labor constraints and operational efficiency are driving demand for systems that are easier to assemble, adjust, and maintain. As labor costs rise and availability fluctuates, fixtures that reduce setup time or allow for quick planogram changes without specialized tools become more valuable. Automation compatibility is also an emerging consideration, as some retailers begin to integrate technology for inventory tracking and shelf monitoring directly into their fixture systems.
Finally, the post-pandemic retail landscape has accelerated the need for hygiene-conscious and flexible designs. Aisles may need to be reconfigured more frequently, and surfaces may need to meet higher sanitation standards. The market players who have adapted their designs to these new realities are better positioned to capture share in the current cycle.
The Strategic Value of Comprehensive Intelligence
While the trends outlined above provide a high-level view, making specific investment or procurement decisions requires a depth of data that only a structured market research report can deliver. Strategic decisions regarding vendor selection, regional expansion, or product development hinge on precise figures regarding market size by segment, growth rates by application, and concentration metrics that reveal competitive vulnerability.
For example, knowing the aggregate market size is useful, but understanding the exact revenue contribution of gondola shelving versus wall-mount systems in the supermarket segment allows for targeted product development. Similarly, recognizing that North America holds a significant revenue share is a starting point, but analyzing the growth rate differential between North America and Asia Pacific informs where to allocate marketing resources or sales force expansion.
The consolidation metrics, such as the CR3 and CR5 percentages, offer insight into the bargaining power of suppliers and the potential for partnership or acquisition opportunities. A market with moderate concentration may leave room for disruptive entrants or niche players to thrive, whereas a highly concentrated market might suggest a need for differentiation through service or technology rather than price.
Our full report dissects these elements with rigorous methodology, providing historical data from 2020 to 2025 as a baseline and detailed forecasts through 2032. It maps the competitive profiles of key companies, analyzing their strengths, weaknesses, and strategic moves. It also includes qualitative assessments of industry drivers, restraints, and opportunities that quantitative data alone cannot capture.
Conclusion and Call to Action
The Retail Shelving Systems Market in 2026 is not merely a supplier market; it is a strategic enabler for the broader retail ecosystem. With a projected CAGR of 9.2% and a total market value trajectory that underscores its importance, the sector offers significant opportunities for those who can navigate its complexities. The key lies in moving beyond general observations to data-backed strategies that align with specific business objectives.
Whether you are a manufacturer looking to optimize your product mix, a retailer planning a network-wide fixture upgrade, or an investor assessing the viability of market entry, the granularity of your intelligence will determine the quality of your outcomes. General trends can guide direction, but precise segmentation, regional analysis, and competitive profiling are required to execute effectively.
We invite you to access the full market research report to unlock the complete dataset and strategic analysis. The full document provides the detailed breakdowns, proprietary forecasts, and actionable recommendations necessary to turn market intelligence into competitive advantage. Do not rely on aggregate figures alone when the nuances of segmentation and regional dynamics can define the success of your initiative. Explore the full report to secure the comprehensive insights needed for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Retail Shelving Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


