



PW Consulting: Medical Device Market Hits $572.31B in 2025, Projected to Reach $889.27B by 2032 at 6.98% CAGR

Navigating the Next Wave: Strategic Intelligence for the 2026 Medical Device Landscape
The global medical device industry stands at a critical inflection point. Between 2020 and 2025, the market expanded from approximately USD 424.76 billion to USD 572.31 billion, demonstrating resilience despite supply chain disruptions, regulatory recalibrations, and shifting reimbursement frameworks. As we enter the 2026-2032 forecast period, the trajectory points toward sustained expansion, with a projected compound annual growth rate of 6.98 percent. By 2032, the global market is expected to approach USD 889.27 billion. For executive teams, investors, and strategic planners, these headline figures represent more than macroeconomic momentum. They signal structural shifts in how devices are developed, regulated, distributed, and adopted across care settings.
At PW Consulting, we have synthesized years of historical tracking, primary research, and forward-looking scenario modeling into a comprehensive Medical Device Market intelligence report. This publication is designed not as a static data dump, but as a decision architecture tool. The following overview outlines the strategic value embedded in the analysis, the operational depth covered, the competitive forces reshaping the sector, and the regulatory and reimbursement currents that will define execution risk in 2026 and beyond.
Why 2026 Demands a Structured Intelligence Framework
The current operating environment is defined by simultaneous pressures and opportunities. On the regulatory front, compliance expectations have tightened across major markets. The FDA's Quality Management System Regulation became fully effective in early 2026, replacing legacy requirements and formally aligning U.S. expectations with ISO 13485:2016. This transition is not merely administrative; it reshapes documentation workflows, supplier qualification processes, and post-market surveillance architectures for manufacturers operating at scale. Across the Atlantic, the European Union's EUDAMED transition deadline for new medical device products has introduced additional registration, traceability, and transparency obligations under the MDR and IVDR frameworks. Companies that treat these milestones as isolated compliance checkboxes risk underestimating the operational redesign required to maintain market access.
Reimbursement dynamics are equally consequential. The CPT 2026 code set, effective January 1, added 288 new codes, including provisions for remote patient monitoring and leg revascularization procedures. These updates expand the billing vocabulary for clinically advanced interventions, but they also require manufacturers and providers to align product positioning, clinical evidence packages, and coding strategies with evolving payer expectations. In parallel, FDA 510(k) review times averaged 140 to 175 days in 2025, with a significant majority of submissions exceeding the 90-day target. For product teams, this reality compounds time-to-market planning, cash flow forecasting, and portfolio sequencing decisions.
Medical Device Market
These forces do not operate in isolation. They interact with capital allocation choices, hospital procurement cycles, and the growing cost burden of advanced clinical infrastructure. Systems such as surgical navigation platforms now represent significant capital commitments for provider organizations, influencing adoption pacing and vendor selection criteria. In this environment, executives need a structured view of where growth is concentrated, how segments are evolving, and which strategic levers will differentiate performers from laggards.
What the Report Delivers: Operational Depth for Cross-Functional Teams
The Medical Device Market report is structured to support multiple functional perspectives without sacrificing analytical rigor. Rather than offering a single aggregated view, the study disaggregates the market across dimensions that matter for strategy, forecasting, and resource allocation. The segmentation architecture includes product categories, end-user settings, and regional distribution, allowing readers to isolate the drivers most relevant to their portfolios.
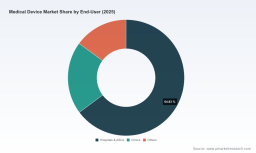
For commercial and market access leaders, the report maps the end-user landscape across hospitals and ambulatory surgery centers, clinics, and other care environments. This breakdown is essential for understanding purchase dynamics, procurement cycles, and the differing adoption curves that characterize large institutional buyers versus smaller outpatient settings. For product and R&D stakeholders, the type-based segmentation illuminates where innovation activity is concentrated, how clinical needs are translating into commercial categories, and which segments are attracting incremental investment.
The regional analysis provides a geographic lens on demand patterns, market maturity, and distributional variance across major territories. Rather than treating geography as a static backdrop, the report uses it to frame localization strategy, pricing architecture, regulatory pathway planning, and partnership considerations. The inclusion of a detailed forecast window through 2032 enables scenario planning that accounts for both baseline growth trajectories and potential disruption points.
Beyond segmentation, the publication integrates competitive intelligence, recent regulatory and industry developments, and contextual factors that shape execution. This combination allows strategy teams to translate high-level market size and growth metrics into actionable implications for channel design, launch sequencing, pricing strategy, and partnership evaluation.
Key Structural Themes Explored
- How product-category growth rates diverge across the forecast horizon and what that implies for portfolio prioritization
- The evolving role of hospitals and ambulatory settings as the dominant demand centers, alongside the growing relevance of clinics and specialized care environments
- Regional demand distribution and its implications for market entry, expansion pacing, and localization of commercial operations
- The relationship between regulatory transitions, reimbursement expansion, and the commercial viability of advanced device categories
- Capital intensity considerations that influence provider adoption and vendor competitiveness in high-investment clinical segments
Competitive Landscape: Concentration, Differentiation, and Strategic Posture
The medical device sector remains characterized by a concentrated yet diverse competitive field. Analysis of market concentration indicates that the top three players account for approximately 37.45 percent of total revenue, while the top five capture roughly 50.23 percent. This structure suggests a market where scale advantages, brand trust, and installed-base dynamics matter significantly, yet where specialized innovators and category leaders can still command meaningful positions through clinical differentiation and targeted commercial execution.
Several established corporations anchor the competitive core. Abbott Laboratories continues to build on its diagnostic device expertise, including blood glucose monitoring and molecular diagnostics. Medtronic maintains a broad footprint across implantable cardiac devices, insulin pumps, and neurostimulation systems. Johnson & Johnson operates across orthopedics, interventional cardiology, and minimally invasive surgical tools, while Becton, Dickinson and Company maintains a strong position in syringes, catheters, and vascular access systems. Stryker Corporation is closely associated with orthopedic implants, surgical robotics, and neurotechnology, and GE Healthcare remains a central force in medical imaging equipment and ultrasound systems. Baxter International Inc. contributes significant scale in infusion systems, dialysis machines, and hemodialysis solutions, while Boston Scientific advances in cardiac rhythm management, endoscopy, and neuromodulation. Siemens Healthineers and Danaher Corporation extend the competitive field through imaging, laboratory diagnostics, and biopharma-adjacent tool sets. Edwards Lifesciences remains focused on heart valve replacement and repair, and Zimmer Biomet Holdings continues to strengthen its joint reconstruction and musculoskeletal offerings.
Medical Textiles Market
Beyond the largest incumbents, a broad set of specialized players shapes category-level competition. Terumo Corporation advances cardiovascular and endovascular devices; Smith & Nephew competes in advanced wound care and orthopedics; Intuitive Surgical is closely identified with robotic-assisted surgery systems; and 3M maintains a diversified presence in infection prevention, wound care, and sterilization products. B. Braun, Alcon, Cardinal Health, and AmerisourceBergen add further depth across infusion therapy, ophthalmic instruments, distribution, and supply chain services. Hologic focuses on diagnostic imaging and women's health devices, Carestream Health on medical imaging and radiography systems, and ResMed on sleep apnea devices and respiratory therapy. Dexcom has become a defining name in continuous glucose monitoring, while Nipro Corporation, Biomerieux, Sonova Holding, Straumann, QuidelOrtho, Envista, and Carl Zeiss Meditec each anchor important niches ranging from dialysis and injectables to in vitro diagnostics, audiology, dental implants, point-of-care diagnostics, and ophthalmic systems.
This competitive mosaic matters because market leadership is not uniform across categories. The report examines how companies position themselves relative to category growth, regulatory complexity, reimbursement exposure, and technological change. Rather than presenting a simple ranking, the analysis considers the strategic logic behind portfolio focus, geographic reach, and innovation intensity. Recent developments reinforce this dynamic view of competition. For example, Bright Uro received FDA 510(k) clearance in mid-2026 for its Glean Abdominal Sensor, expanding multi-channel urodynamic capabilities for wireless ambulatory studies in lower urinary tract dysfunction. At the same time, the Medical Device Manufacturers Association hosted an FDA Forum with more than 125 attendees, where senior FDA officials addressed regulatory topics including biocompatibility, cybersecurity, and AI. The FDA also scheduled a hybrid regulatory education conference later in the year to discuss innovative strategies for medical devices, drugs, and biologics. These events illustrate a sector where regulatory engagement, technological novelty, and clinical differentiation are increasingly intertwined.
Regulatory, Reimbursement, and Infrastructure Dynamics
Strategic planning in 2026 cannot rely on product performance alone. The environment is being reshaped by overlapping regulatory harmonization, reimbursement expansion, and infrastructure cost realities. The full effectiveness of the FDA's QMSR marks a structural shift toward ISO-aligned quality systems, which affects documentation, supplier management, and audit readiness across the device lifecycle. In Europe, EUDAMED transition requirements for new products add another layer of registration and transparency obligations that influence launch timing and market access planning.
Reimbursement developments are expanding the procedural and service vocabulary that supports device adoption. The addition of new CPT codes for remote patient monitoring and leg revascularization procedures reflects broader trends toward continuous care models and minimally invasive intervention. These changes can improve the commercial feasibility of technologies that align with evolving care pathways, but they also require manufacturers to maintain robust evidence generation, coding alignment, and payer engagement strategies.
At the provider level, capital intensity remains a practical constraint. Advanced surgical navigation systems can represent significant investments for hospitals, with costs that influence procurement timing, service contracts, and total cost of ownership calculations. As providers evaluate technology purchases, the value proposition increasingly depends on workflow integration, training support, sterilization and maintenance considerations, and demonstrable clinical and operational outcomes. For manufacturers, this means commercialization strategies must address not only product performance but also the economic and operational realities of the purchasing organization.
Regulatory review timelines further shape planning assumptions. With FDA 510(k) review times averaging well above the 90-day target in 2025, product teams and executive sponsors need realistic expectations for submission cycles, supplemental filings, and post-clearance execution. Integrating these operational realities into forecast models and launch plans is essential for avoiding over-optimistic timing assumptions.
Translating Market Intelligence into 2026 Decision Advantage
The overarching value of this report lies in its ability to connect macroeconomic growth signals with the operational decisions that determine competitive outcomes. The market's projected expansion from roughly USD 613.56 billion in 2026 to nearly USD 889.27 billion by 2032 is not a uniform ascent. It is distributed unevenly across product categories, care settings, and regions, and it is mediated by regulatory timing, reimbursement clarity, and provider capital behavior. Executives who understand these distributions can make better-informed choices about where to invest, how to sequence launches, which partnerships to pursue, and where to strengthen compliance and market access capabilities.
For portfolio strategy teams, the segmentation and forecast framework supports prioritization decisions by highlighting where demand trajectories are strongest and where competitive density is likely to intensify. For commercial leaders, the end-user and regional analysis informs channel design, pricing strategy, and go-to-market localization. For regulatory and quality functions, the contextual updates on QMSR, EUDAMED, and 510(k) review dynamics provide a practical backdrop for resource planning and risk management. For corporate development and investor relations teams, the competitive concentration data and company-level profiles offer a structured basis for benchmarking, partnership screening, and market positioning narratives.
The report also emphasizes the importance of monitoring near-term signals that can alter longer-term assumptions. Recent regulatory education initiatives, FDA engagement forums, and clearance activity point to an environment where innovation and oversight are evolving together. Companies that build processes to interpret these signals quickly will be better positioned to adjust development roadmaps, update market access strategies, and align internal timelines with external realities.
Conclusion: From Insight to Execution
The medical device market is entering a phase where growth is substantial but increasingly conditional on strategic precision. The broad expansion reflected in the forecast period is real, yet its value accrues to organizations that can interpret segment-level dynamics, navigate regulatory and reimbursement change, and align commercial execution with the economic constraints of provider buyers. PW Consulting's Medical Device Market report is designed to give decision-makers that interpretive edge.
To explore the full segmentation detail, regional breakdowns, competitive profiles, and forecast scenarios, we invite you to access the complete report on our website. The comprehensive intelligence package provides the depth required to translate market momentum into disciplined, high-conviction strategy for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


