



PW Consulting: Alkyl Catalyst Market Hits $125.28M in 2025, Poised for $155.69M by 2032 (3.1% CAGR)

Strategic Intelligence for 2026: Navigating the Alkylation Catalysts Market
In an era where refining margins and environmental mandates intersect, the alkylation catalysts market represents a critical nexus for petrochemical and downstream fuel producers. As global energy transitions accelerate and regulatory frameworks tighten, decision-makers require more than surface-level estimates. They need forward-looking intelligence that maps technological shifts, competitive maneuvers, and demand trajectories with surgical precision. Our latest market research on alkylation catalysts delivers exactly that, positioning corporate strategy teams, procurement leaders, and R&D directors to act decisively throughout the 2026–2032 forecast horizon.
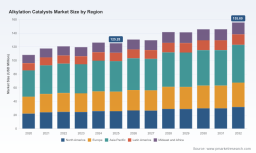
The global alkylation catalysts market reached an estimated 125.28 million USD in 2025, reflecting a nuanced trajectory from its 2020 baseline of 108.15 million USD. Looking ahead, our analysis projects steady expansion, with the market anticipated to reach approximately 130.67 million USD in 2026 and continue its upward path toward 155.69 million USD by 2032. This translates to a compound annual growth rate of 3.1 percent over the forecast period, underscoring a market defined not by explosive volatility but by measured, regulation-driven adoption and incremental process optimization. For enterprises planning capital allocation, technology roadmaps, or supply chain restructuring, understanding the velocity and direction of this growth is non-negotiable.
Why This Research Matters for 2026 Decision-Making
The 2026 operating environment will test refining and petrochemical organizations on multiple fronts simultaneously. Stricter environmental regulations are intensifying pressure to replace legacy hydrofluoric acid and sulfuric acid processes with solid acid zeolite alternatives that reduce hazardous emissions and align with evolving gasoline blending limits. At the same time, macro trends toward HF-free alkylation are accelerating, driven by incident avoidance mandates from OSHA and EPA standards and reinforced by ISO 9001:2015 and API certification requirements that now govern catalyst suppliers across global refinery networks. These dynamics reshape procurement criteria, technology licensing strategies, and long-term capacity planning.
Our report was engineered to translate these macro forces into actionable intelligence. It does not simply chart historical revenue lines; it isolates the structural drivers that will determine competitive outcomes over the next seven years. Readers will gain clarity on how shifting refinery configurations, regional regulatory pacing, and catalyst formulation innovations converge to create both risk and opportunity. The study maps demand pathways across key application segments, evaluates the performance and commercial readiness of competing catalyst architectures, and dissects the strategic positioning of leading technology providers. By embedding 2026-specific regulatory updates, including forthcoming REACH and TSCA standard revisions that mandate lower sulfur catalysts, the analysis equips executives with the foresight required to anticipate compliance costs, retrofit timelines, and procurement lead times before they become operational bottlenecks.
Inside the Report: Practical Intelligence for Strategy and Operations
This publication is structured as a decision-support toolkit rather than a static market snapshot. Each section is designed to answer the practical questions that arise in boardrooms, engineering reviews, and procurement committees. The report provides a comprehensive evaluation of catalyst types, dissecting performance characteristics, lifecycle economics, and compatibility with existing alkylation units. It examines application pathways across ethylbenzene and cumene production, alkane upgrading, and emerging specialty uses, drawing clear connections between catalyst selection and downstream product specifications. Regional demand patterns are contextualized through the lens of refining capacity expansion, regulatory adoption curves, and infrastructure readiness, allowing readers to identify where growth will materialize and what supply chain implications follow.
Beyond market sizing, the study delivers a competitor intelligence framework that evaluates how major players differentiate their technology portfolios, shape licensing strategies, and respond to evolving compliance landscapes. Each profiled organization is assessed on its core catalyst offerings, recent technology milestones, and strategic posture within the broader alkylation value chain. The report also incorporates an in-depth analysis of recent commercial developments, including new product launches, process innovation milestones, capacity expansions, and operational technology upgrades that have reshaped competitive dynamics in the past year. By linking these events to broader market forces, the research reveals how technology roadmaps and corporate execution are influencing the pace of adoption across the industry.
Readers will also find structured assessments of market concentration, technology licensing trends, and supply-side constraints that directly affect pricing negotiations, vendor selection, and long-term contract strategies. The report integrates qualitative insights on certification requirements, safety standards, and environmental compliance pathways, ensuring that procurement and engineering teams can align catalyst specifications with both operational and regulatory objectives. All findings are presented with sufficient granularity to support scenario planning, while deliberately preserving the highest-resolution data for stakeholders who require definitive commercial intelligence.
The Competitive Landscape: Leaders Defining the Next Generation of Alkylation Technology
The alkylation catalysts market is characterized by a concentrated set of technology leaders whose proprietary processes and catalyst formulations heavily influence industry standards. Honeywell UOP stands at the forefront with its ISOALKY ionic liquid catalyst and established HF and sulfuric acid alkylation processes, delivering high-octane alkylate performance tailored for complex refinery configurations. Its recently commissioned EcoZeal low-temperature catalyst in Belgium demonstrated the viability of modular alkylation systems operating at reduced thermal loads, while subsequent pilot testing validated an 18 percent energy consumption reduction—a development that signals the growing commercial relevance of low-temperature catalyst architectures.
Chemical Catalyst Market
ExxonMobil continues to shape the competitive field through its EMRE technology and zeolite catalyst portfolio designed for sulfuric acid alkylation, emphasizing reliability and integration with existing refinery infrastructure. Albemarle Corporation has carved a distinct position with its AlkyClean process and AlkyStar catalyst, which deliver sulfur-free, high-octane gasoline outputs aligned with tightening emissions standards. In 2025, Albemarle introduced a new environmentally friendly zeolite catalyst specifically engineered for high-octane gasoline production, and simultaneously implemented real-time catalyst analytics across four facilities, achieving a 9 percent improvement in operational uptime. These initiatives illustrate how data-driven catalyst management is becoming a competitive differentiator.
Sinopec has expanded its influence through silica-modified zeolites and zeolite catalysts optimized for commercial alkylation units, scaling up its modified catalyst formulations for broader refinery deployment. Meanwhile, Zeolyst International provides specialized solutions through its ATA-41 and broader zeolite series, supporting trans-alkylation and paraffin isomerization applications where selectivity and catalyst longevity are paramount. Together, these organizations reflect a market where technological differentiation, process integration, and compliance readiness determine market share trajectories. With a combined concentration that highlights the dominance of a handful of major technology providers, the landscape rewards organizations that can align their procurement and licensing strategies with the most resilient and forward-compatible catalyst architectures.
Market Dynamics: Regulation, Technology, and the Push Toward Safer Refining
The alkylation catalysts market is being reshaped by a convergence of regulatory, environmental, and technological forces that collectively redefine what refineries demand from catalyst suppliers. Stricter environmental regulations are accelerating the shift toward solid acid zeolites, which reduce hazardous emissions from alkylation units and align with increasingly stringent gasoline blending limits. This transition is not incremental; it represents a structural reorientation of catalyst procurement priorities, with safety, emissions performance, and regulatory compliance now competing alongside cost and throughput in vendor selection criteria.
The push toward HF-free alkylation has gained significant momentum as organizations seek to mitigate operational risk under OSHA and EPA incident avoidance mandates. Supply chain and engineering teams are increasingly prioritizing catalyst systems that minimize hazardous material handling, reduce worker exposure, and simplify permitting processes. Certification frameworks such as ISO 9001:2015 and API standards have further elevated the bar for catalyst suppliers, ensuring that product consistency, traceability, and quality management systems meet the rigorous expectations of global refinery operators.
Looking toward 2026, updates to REACH and TSCA standards will introduce additional compliance layers by mandating lower sulfur catalysts to meet evolving gasoline specifications. These regulatory milestones will influence not only catalyst formulation but also procurement cycles, validation timelines, and retrofit planning. Organizations that understand the sequencing of these requirements will be better positioned to negotiate long-term supply agreements, manage inventory buffers, and coordinate engineering readiness for catalyst transitions. The market is therefore moving toward a model where regulatory foresight and technology selection are inseparable components of operational strategy.
Alkylation Catalysts Market
Positioning Your Organization for the 2026–2032 Horizon
Navigating the alkylation catalysts market successfully requires a clear understanding of how regulatory timelines, catalyst technology evolution, and competitive behavior intersect. The 3.1 percent CAGR projected through 2032 suggests a market where incremental gains are secured through operational efficiency, compliance readiness, and strategic alignment with technology leaders who can deliver durable performance improvements. Enterprises that integrate market intelligence into their capital planning, vendor negotiations, and process modernization roadmaps will be best equipped to protect margins and capture value as the industry transitions toward safer, cleaner, and more efficient alkylation architectures.
Our full market research report provides the detailed segmentation analysis, competitive benchmarking, regulatory impact modeling, and forward-looking scenario frameworks necessary to make these decisions with confidence. To access the complete dataset, detailed segmentation breakdowns, and comprehensive strategic recommendations, visit the source page for the full report and equip your team with the intelligence needed to lead in the evolving alkylation catalysts landscape.
For detailed analysis of this topic, please visit the official page: Alkylation Catalysts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


