



PW Consulting: USV Market Hits $1.125B in 2025, Projected 12.45% CAGR to $2.556B by 2032

Navigating the Autonomous Horizon: Strategic Imperatives in the 2026 USV Market
Executive Summary
The maritime domain is undergoing a profound transformation, shifting from crewed dominance to a hybrid ecosystem where Unmanned Surface Vehicles (USVs) play a pivotal role in defense, commercial efficiency, and scientific exploration. As we move through 2026, the strategic importance of understanding this market cannot be overstated. PW Consulting's latest comprehensive study on the Unmanned Surface Vehicles Market offers a critical roadmap for stakeholders aiming to navigate this rapidly evolving landscape. This report is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, product development, and partnership strategies in an environment defined by technological acceleration and geopolitical tension.
The transition from experimental prototypes to operational deployment is now complete. The market has matured beyond the proof-of-concept phase, entering a period of sustained growth driven by tangible operational requirements. For enterprise leaders, defense contractors, and investment firms, the window to establish market position is narrowing. This analysis serves as the introduction to our full market intelligence package, highlighting the macro-economic trajectories and competitive forces that will define the next seven years.
Market Trajectory: From Niche to Mainstream
Historical Growth and Future Outlook
The USV market has demonstrated exceptional resilience and expansion over the past half-decade. Our analysis tracks revenue performance from 2020 through the base year of 2025, revealing a consistent upward trajectory that outperforms many adjacent technology sectors. In 2020, the global market revenue stood at USD 520.0 Million. By 2025, this figure had more than doubled, reaching USD 1125.0 Million. This growth underscores the rapid adoption rates across both governmental and commercial sectors, validated by sustained investment streams.
Unmanned Surface Vehicles (USV) Market
Looking forward, the forecast period from 2026 to 2032 suggests that this momentum is not only maintained but accelerated. The market is projected to reach USD 1225.21 Million in 2026 immediately, climbing steadily to USD 2556.18 Million by 2032. This trajectory indicates a Compound Annual Growth Rate (CAGR) of 12.45 percent over the forecast period. Such growth rates signal a maturing industry where standardized platforms are beginning to replace bespoke solutions, allowing for scalability and broader market penetration.
Value Chain and Economic Drivers
The economic expansion is underpinned by several key drivers. Operational cost reductions in maritime surveillance, increased risk tolerance in hazardous zones, and the strategic necessity of distributed maritime operations are primary catalysts. Furthermore, technological advancements in sensor fusion and autonomous navigation are reducing the barrier to entry for commercial entities. The revenue unit across all analyses is tracked in USD Million, providing a standardized benchmark for comparing investment potential against other defense and maritime technology sectors.
Underwater Drone Market
Investors and strategists must note that the growth is not linear. There are inflection points associated with regulatory approvals and technological breakthroughs. The period between 2024 and 2025 saw a significant jump in valuation, suggesting a tipping point in market acceptance. As we enter the forecast period, the focus shifts from capability demonstration to reliability and endurance. The market size projections for 2027 through 2032 reflect the cumulative effect of new entrants and the expansion of existing product lines into broader operational domains.
Segmentation and Functional Deployment
To understand where the value lies, one must look at how the market is structured. Our report dissects the industry across three primary dimensions: Type, Application, and Region. While specific quantitative breakdowns are reserved for the full dataset to preserve proprietary depth, the qualitative structure reveals where innovation is concentrated.
Classification by Vehicle Type
The market is categorized by the level of autonomy and control mechanisms employed. The segments include Autonomous Surface Vehicles, Remotely Operated Surface Vehicles, and Hybrid Surface Vehicles. Autonomous systems are gaining significant traction due to advancements in AI-driven decision-making, allowing for prolonged missions without direct human intervention. Remotely Operated systems remain critical for tasks requiring precise human oversight, particularly in complex littoral environments. Hybrid systems offer a flexible middle ground, adapting to mission requirements dynamically. Understanding the adoption rates and technological maturity within each of these types is essential for manufacturers deciding where to focus R&D resources.
Application Verticals
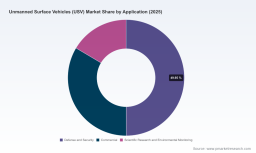
Deployment scenarios drive demand. The primary applications analyzed include Defense and Security, Commercial operations, and Scientific Research and Environmental Monitoring. Defense and Security remains a dominant force, driven by naval modernization programs and border security needs. However, the Commercial segment is expanding rapidly, encompassing sectors such as offshore energy inspection, hydrographic surveying, and logistics support. Scientific Research continues to be a steady growth area, leveraging USVs for oceanographic data collection that was previously cost-prohibitive or too dangerous for crewed vessels. Each vertical presents unique procurement cycles and regulatory hurdles that are detailed extensively in the full report.
Regional Distribution
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Regional dynamics are heavily influenced by local defense spending, maritime trade volumes, and environmental regulations. North America and Europe currently show strong adoption rates linked to established defense budgets and advanced maritime industries. Meanwhile, the Asia Pacific region represents a high-growth frontier, driven by increasing naval capabilities and commercial shipping expansion. A localized strategy is required for each region, as regulatory frameworks and operational requirements vary significantly.
Competitive Landscape and Strategic Positioning
Market Concentration and Key Players
The USV market exhibits a moderate to high level of concentration, indicative of an industry where barriers to entry include significant R&D investment and certification hurdles. Our analysis indicates that the top three companies hold a substantial market share, with the top five firms controlling a significant majority of the industry revenue. This concentration suggests that partnerships, acquisitions, or niche specialization are viable strategies for new entrants looking to gain foothold without competing directly on volume.
Several key enterprises define the current competitive landscape. Teledyne Marine, based in Redondo Beach, California, maintains a strong focus on specific offerings tailored to the USV sector, leveraging their broader sensor and instrumentation capabilities. Maritime Robotics, headquartered in Norway, is recognized for its robust autonomous solutions designed for harsh maritime environments. OceanAlpha, located in Zhuhai, China, represents the growing manufacturing capacity and innovation coming from the Asian market, focusing on cost-effective unmanned platforms.
In the United States, Saildrone, headquartered in Richmond, California, has become synonymous with long-endurance solar-powered vessels, pushing the boundaries of persistence in data collection. Textron Systems, based in Boston, Massachusetts, is a major defense contractor contributing significant engineering resources and proven military-grade platforms. L3Harris Technologies, also in Florida, brings extensive integration capabilities for communication and payload systems. Sea Machines, another Boston-based firm, is notable for its focus on autonomous control systems that can be retrofitted onto existing vessels, lowering the barrier for commercial adoption.
European defense and technology firms also play a critical role. Elbit Systems, based in Haifa, Israel, contributes advanced defense electronics and unmanned capabilities. Exail Technologies, in Paris, France, focuses on specialized naval technologies and robotics. Kongsberg Gruppen, in Kongens Lyngby, Norway, is a longstanding leader in maritime autonomy and precision systems. These companies are not just vendors; they are setting the standards for interoperability and reliability.
Recent Developments and Strategic Moves
The competitive landscape is dynamic, with recent developments highlighting the shift towards operational deployment. In May 2026, the US Navy selected seven companies to advance Medium Unmanned Surface Vessel (MUSV) designs to the at-sea prototype evaluation and testing phase. This selection process is a critical filter, separating conceptual designs from those ready for integration into naval operations.
Furthering this momentum, HII advanced its Romulus USV design into the MUSV prototype phase for Navy evaluation in February 2026. This move signals a commitment to scalable unmanned logistics and combat support. Meanwhile, Textron Systems was awarded a contract in June 2026 to deploy multiple Tsunami USVs for Navy FLEX exercises and SOUTHCOM operations, demonstrating the immediate utility of these systems in real-world scenarios.
Historical context also validates the technology. In November 2025, a US Navy-sponsored Lightfish solar-powered USV completed the fastest transatlantic crossing in over two months. This achievement underscores the viability of renewable energy integration for extended range missions, a key consideration for long-duration autonomous operations.
Industry Dynamics and Technological Enablers
Propulsion and Material Science
The physical capabilities of USVs are being enhanced by breakthroughs in raw materials and energy storage. In 2024, Lithium-iron-phosphate batteries delivered 25 percent higher energy density. This improvement enables smaller USV craft to carry reserves for complex sensor operation at extended range, directly impacting mission profiles and payload capacity. This technological leap allows designers to optimize hull sizes without sacrificing endurance, a critical factor for commercial viability.
Furthermore, hull construction materials are standardized around high-performance options. USV hulls primarily use aluminum and composite materials, including fiberglass and carbon fiber. These materials are selected for their high strength-to-weight ratios, corrosion resistance, and reduced maintenance needs. The choice of material affects not only the operational lifespan but also the total cost of ownership, making material science a key consideration in procurement decisions.
Regulatory and Operational Requirements
Regulatory frameworks are tightening alongside technological capabilities. The US Navy currently requires operational demonstrations of not less than 720 continuous hours without any form of repair or maintenance on the main propulsion system, electrical generation, and distribution systems for large USV programs. This stringent requirement sets a high bar for reliability and influences vendor selection heavily. It implies that software autonomy is only half the battle; hardware durability and energy management are equally critical.
Compliance with these standards requires rigorous testing protocols and quality assurance processes. Companies that can demonstrate adherence to these operational tempos will gain a competitive advantage in defense contracting. For commercial entities, similar reliability standards are emerging as insurance and liability concerns come into play. The intersection of regulation and technology creates a moat for established players who have the resources to meet these demanding specifications.
Strategic Value for 2026 Decision-Making
Why This Research Matters Now
The data presented in our full market study provides more than just hindsight; it offers foresight. The convergence of defense modernization, commercial automation, and environmental monitoring needs creates a unique investment environment. However, the complexity of the supply chain, the nuance of regulatory compliance, and the velocity of technological change make intuition insufficient for strategic planning. Accessing detailed segmentation data, competitor profiling, and scenario analysis is essential.
Our report provides the granularity needed to answer specific questions: Which application vertical offers the highest margin potential? How do regional tariffs impact material costs? What is the adoption curve for hybrid versus fully autonomous systems? These insights are critical for positioning products and services effectively.
Actionable Intelligence
Stakeholders utilizing this research can expect to gain clarity on market entry barriers, partnership opportunities, and risk mitigation strategies. The analysis of key companies and recent contract awards provides a benchmark for assessing competitive strength. Understanding the material and energy trends allows for better product planning and supply chain management. Ultimately, the goal is to move from reactive adaptation to proactive strategy.
The market is moving toward a future where unmanned systems are integral to maritime operations. Those who understand the trajectory today will define the standards of tomorrow. PW Consulting's USV Market study is designed to equip leaders with the intelligence required to make those defining decisions with confidence.
For detailed segmentation data, comprehensive competitor financial analysis, and region-specific forecasts, we invite you to access the full report. The insights within go beyond the macro trends to provide the specific intelligence necessary for tactical execution in the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Unmanned Surface Vehicles (USV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


