



PW Consulting Projects Penicillin API Market to Reach $385M by 2032, Growing at 5.6% CAGR from $280M in 2025

Beyond the Blister Pack: The Strategic Battlefield for Penicillin Active Pharmaceutical Ingredients
The state of global healthcare supply chains is often measured in headlines about finished drugs reaching pharmacy shelves. Yet the true vulnerability and opportunity in the antibiotic sector lie upstream, in the manufacture of the active pharmaceutical ingredients that make those medicines possible. Penicillin APIs remain among the most critical yet geopolitically exposed building blocks in modern medicine. For executives, procurement leaders, and strategy teams navigating the post-pandemic regulatory environment, the decisions made in 2026 will define competitive positioning through the end of the decade.
This article previews our latest market research, designed to give decision-makers a clear view of where the market is heading, which structural forces are shaping it, and where strategic leverage can be gained. The full intelligence, including granular segmentation, company-level capacity maps, and scenario modeling, is available in our published report. Here, we outline the strategic contours that every stakeholder should understand before committing capital, capacity, or supplier relationships.
A Market Defined by Steady Growth and Hidden Complexity
On the surface, the penicillin API market presents a picture of disciplined expansion. Between 2020 and 2025, global revenue climbed from roughly 212.5 million USD to 280.0 million USD, reflecting both the enduring clinical relevance of beta-lactam antibiotics and the gradual recovery of supply chains from earlier disruptions. The forward trajectory through 2032 points to continued momentum, with the market expected to surpass 385.0 million USD by the close of the forecast window. The projected compound annual growth rate of 5.6 percent over this period is neither explosive nor negligible; it is the kind of steady, policy- and demand-driven expansion that rewards companies who move early on capacity, compliance, and supplier diversification.
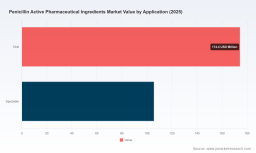
However, aggregate figures only tell part of the story. Beneath the headline numbers lies a market shaped by distinct product families, delivery formats, and regional production realities that determine margin profiles, supply resilience, and regulatory exposure. The bulk of commercial activity centers on established molecules such as amoxicillin, ampicillin, and penicillin G potassium, supplemented by a broader category of derivatives and specialty intermediates. Demand patterns also diverge sharply across administration routes, with oral formulations commanding the larger share of volume while injectable products sustain a significant and clinically essential footprint. Understanding how these structural elements interact with regional manufacturing capacity is the first step toward building a strategy that can withstand price pressure, regulatory shifts, and geopolitical shocks.
Why 2026 Is a Decision Year for Penicillin API Strategy
The years ahead will not simply be a continuation of past trends. Several intersecting forces make 2026 a pivotal moment for anyone operating in or adjacent to this market. First, the balance between cost efficiency and supply security has fundamentally changed. Organizations that once optimized purely for unit price are now weighing single-source dependency against resilience, particularly where national governments are signaling expectations around domestic or allied-region production of critical medicines.
Second, capital is flowing back into antibiotic API infrastructure, but selectively. Recent facility launches and expansions illustrate how firms are positioning themselves to capture growth while also responding to regulatory and policy tailwinds in specific geographies. At the same time, these investments create capacity additions that may reshape pricing dynamics and competitive intensity over the forecast period. Companies that understand the timing, scale, and certification status of these assets will be better placed to negotiate supply agreements, plan their own production roadmaps, and anticipate shifts in the competitive hierarchy.
Third, raw material and environmental cost structures are exerting renewed pressure on profitability. Changes in export tax treatment on fermentation feedstocks, for example, have raised production costs for some manufacturers, compressing margins that were already tight in a price-sensitive commodity-adjacent market. In parallel, environmental compliance and operating permits have become strategic variables rather than mere administrative hurdles, influencing which plants can run at full capacity and which face interruptions. A 2026 decision framework must therefore integrate cost volatility, regulatory timing, and capacity reliability into a single view, rather than treating them as separate tactical concerns.
The Concentration of Power and the Fragmentation of Risk
Market structure is a central theme for strategy. The penicillin API landscape displays moderate concentration at the top, with the largest players accounting for a significant but not dominant share of global revenue, while the remaining balance is distributed across a wide field of regional and specialized producers. This configuration matters because it shapes bargaining dynamics, switching costs, and the ability of buyers to diversify without sacrificing quality or regulatory compliance.
At one end of the spectrum are fully integrated, high-capacity facilities with strong regulatory credentials and explicit commitments to maintaining production in specific regions. These assets serve as anchor points in the supply chain, offering continuity for customers who prioritize stability and traceability. Elsewhere, particularly in Asia, multiple large-scale producers supply bulk penicillin G potassium and related intermediates to global generic manufacturers, leveraging scale, active regulatory filings, and export-oriented operations. Their presence lowers barriers to access but also introduces concentration risk in feedstock sourcing and downstream dependency.
The strategic implication is nuanced. A market with meaningful concentration can offer efficiency and established quality systems, yet it can also create exposure if policy, environmental events, or operational disruptions affect key sites. Conversely, a more fragmented supplier base can improve diversification but requires stronger quality governance and qualification programs. In 2026, the winning strategies will be those that map this landscape not just by company names, but by capacity, certification status, geographic footprint, and the real-world reliability of each node under stress.
Recent Signals Shaping the Competitive Landscape
Several recent developments underscore how quickly the ground can shift. In Europe, Sandoz completed the final phase of a major investment at its Kundl facility, adding meaningful capacity for penicillin API and finished-dose production while reinforcing its public commitment to safeguard EU-based manufacturing. This move is strategically significant not only because of the capacity added, but because it signals a deliberate choice to maintain a European anchor in a category where production has otherwise migrated toward lower-cost regions.
Penicillin Active Pharmaceutical Ingredients Market
In India, high-profile facility investments and restarts have drawn attention to the country's ambition to expand domestic API capability. A flagship penicillin G production site was inaugurated with national-level visibility and subsequently resumed operations after regulatory approvals following an earlier disruption. Combined with India's broader incentive frameworks, these actions point to a long-term push to reduce import dependency for critical intermediates. Yet they also illustrate the practical realities of capacity ramp-up, environmental permitting, and the time required to achieve stable, certified output at scale.
Beyond individual corporate moves, the supply chain itself reveals structural vulnerabilities that no executive should overlook. Dependence patterns remain pronounced in several directions: downstream generic drug markets in some regions remain heavily reliant on imported penicillin APIs, and leading formulation producers in other markets continue to source the majority of their intermediates from a single upstream origin. These dependencies create efficiency today but elevate risk in a scenario where trade policy, pricing, or operational continuity changes unexpectedly. This is precisely the kind of blind spot that rigorous market intelligence is designed to illuminate before it becomes a crisis.
What Our Research Delivers for Executive Decision-Making
Our full market research is built to translate complex supply chain and competitive dynamics into actionable intelligence. Rather than stopping at high-level totals, the report unpacks the market in ways that support procurement strategy, capacity planning, regulatory risk assessment, and competitive positioning. The following elements are central to the analysis:
Worldwide Penicillin Market
- Forward-looking revenue trajectories across the forecast window, framed to support scenario planning rather than single-point estimates, with explicit attention to the rate and shape of growth as policy and capacity evolve.
- A structured view of product and formulation segments, allowing readers to understand where volume and value concentrate, how mature categories differ from higher-value derivatives, and what that implies for sourcing and differentiation.
- Regional production and demand context that connects manufacturing footprints to regulatory environments, feedstock access, and import-dependency patterns without reducing the picture to simplistic rankings.
- Company profiles and recent operational developments for the key players shaping supply, including fully integrated European producers, large-scale Asian exporters, and specialized international suppliers, with emphasis on capacity, certifications, and strategic intent.
- Market concentration analysis that clarifies the balance between consolidated leadership and broader supplier fragmentation, helping buyers and investors gauge negotiation leverage and resilience options.
- Supply chain and cost dynamics that bring into focus raw material policy changes, environmental permitting risk, and the interplay between upstream intermediates and downstream formulation requirements.
The objective is not simply to describe the market but to enable better decisions. Procurement leaders can use the analysis to evaluate diversification options and qualification pipelines. Executives planning capacity or partnership strategies can benchmark their timing against announced investments and regulatory milestones. Competitive intelligence teams can map where consolidation pressure is likely to intensify and where niche positioning may remain viable. This breadth of practical utility is what distinguishes a strategic study from a conventional data summary.
How to Use This Intelligence in 2026
The most valuable use of this research is not passive reading but active scenario building. We recommend that teams approach the findings with three questions in mind. First, where are the single points of failure in your current supply base, and which alternative nodes are credible from a regulatory, quality, and capacity standpoint? Second, how will announced capacity additions and regional policy commitments alter the bargaining environment over the next two to three years? Third, what cost and margin assumptions remain robust if feedstock economics, environmental compliance, or import-dependency patterns shift further than currently anticipated?
These questions cannot be answered by headlines or isolated statistics. They require a detailed view of how regional dynamics, product categories, supplier capabilities, and regulatory realities interact across the forecast period. That is the level of analysis our report provides, and it is the level at which serious strategic choices are made.
Access the Full Strategic View
The penicillin API market is expanding, but its real significance lies in the strategic choices it forces upon participants: how to balance cost and continuity, how to interpret capacity investments in context, and how to prepare for a supply environment where policy and operational risk are as important as unit price. Our newly released market research offers the depth and structure required to make those choices with confidence.
To explore the complete segmentation, competitive profiles, regional supply dynamics, and forward scenarios that underpin this analysis, please access the full report. The detailed intelligence inside is designed for practitioners who need more than a summary—they need a decision-ready map of the market through 2032.
For detailed analysis of this topic, please visit the official page: Penicillin Active Pharmaceutical Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


