



PW Consulting: Embedded Computing Market Hits $215M in 2025, Projects 7.02% CAGR Through 2032

Navigating the Next Wave: Strategic Intelligence for the Merchant Embedded Computing Market (2026–2032)
The global landscape for merchant embedded computing is undergoing a structural transformation. As industries accelerate digitalization and edge intelligence becomes embedded in everyday operations, the demand for specialized, robust, and standards-compliant computing platforms has moved from niche infrastructure to strategic enterprise priority. Our latest market research, The Merchant Embedded Computing Market, delivers a comprehensive, data-grounded forecast designed to equip executives, procurement leaders, and technology strategists with the actionable intelligence required to make confident decisions throughout 2026 and beyond.
Drawing on historical performance data from 2020 through 2025 and extending through a detailed forecast period to 2032, this study maps the trajectory of a market that is expanding at a measured yet sustained pace. The analysis is built on rigorous primary and secondary research, cross-validated industry modeling, and transparent methodological frameworks. The result is a strategic reference that goes beyond surface-level projections to uncover the operational, competitive, and regulatory forces shaping procurement cycles, product roadmaps, and market entry decisions.
A Market Poised for Sustained Expansion
Historical data reveals a market that navigated volatility with resilience. After reaching a baseline of approximately 163.15 million USD in 2020, the sector demonstrated consistent growth momentum, peaking at 215.0 million USD by 2025. This trajectory reflects more than cyclical upturns; it signals a fundamental shift in how enterprises deploy computing at the edge, particularly where reliability, real-time processing, and integration with digital payment or industrial automation ecosystems are non-negotiable.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to reach 344.8 million USD by the close of the decade. The compound annual growth rate of 7.02 percent underscores a steady, compounding trajectory rather than speculative spikes. For enterprise decision-makers, this growth profile presents a clear strategic implication: merchant embedded computing is no longer a supplementary technology layer. It is becoming a foundational component of operational architecture, particularly for organizations scaling IoT deployments, modernizing factory automation, and integrating secure transaction platforms.
Decoding the Report’s Architecture: From Macro Trends to Tactical Playbooks
This research is structured to serve multiple strategic functions. Rather than offering a single aggregated view, the report dissects market dynamics across applied dimensions that matter to procurement, R&D, and competitive positioning teams. The analytical architecture includes:
- Historical baseline and forward modeling: A granular reconstruction of market performance from 2020 through 2025, paired with a decade-long forecast extending to 2032, allows stakeholders to benchmark current investments against projected trajectories.
- Technology and product-type evaluation: The study maps the competitive and functional relevance of segment categories, highlighting where innovation cycles are accelerating, where integration complexity persists, and which platforms are attracting the highest enterprise demand.
- Application-driven demand mapping: The report disaggregates adoption across high-impact verticals, revealing where merchant embedded computing platforms are resolving latency, reliability, and compliance bottlenecks, and where emerging use cases are reshaping procurement criteria.
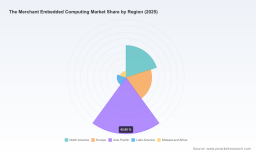
- Regional demand dynamics: Geographic analysis identifies where infrastructure investment, industrial digitization, and regulatory environments are creating localized pull factors, helping multinational teams align supply strategies with regional procurement realities.
- Competitive positioning and company profiling: Detailed assessments of market participants include operational footprints, product portfolios, and strategic focus areas, providing context for partnership selection, benchmarking, and market entry planning.
- Industry context and constraint analysis: The research incorporates real-world friction points, from certification requirements and interoperability gaps to workforce and component cost pressures, ensuring that strategic planning reflects on-the-ground realities.
By integrating these dimensions into a unified analytical framework, the report enables decision-makers to move from broad market awareness to precise allocation strategies. The emphasis is on clarity, comparability, and operational relevance, ensuring that every section translates into a decision-enabling insight.
The Merchant Embedded Computing Market
Competitive Landscape: Who Is Shaping the Next Cycle?
The merchant embedded computing market is defined by a diverse mix of established industrial suppliers, edge-computing specialists, and defense-grade technology integrators. Market concentration data indicates a moderately fragmented environment, with the top three players holding a combined share of 24.6 percent and the top five reaching 26.2 percent. This distribution suggests that while incumbents maintain strong positioning, differentiation through application-specific engineering, certification readiness, and edge AI integration remains a viable path for competitive advantage.
Several companies stand out for their strategic alignment with the market’s evolving demands:
Embedded Computer Market
- Advantech Co., Ltd. continues to anchor its portfolio around industrial-grade merchant embedded computing platforms and systems, with a clear focus on digital payment solutions and rugged applications. Its January 2025 announcement of a new line of AI-enabled embedded systems for industrial automation, delivering 20 percent faster processing speeds, signals a deliberate push toward higher-throughput edge intelligence.
- ADLINK Technology Inc. has positioned itself at the intersection of edge processing and real-time industrial automation. Its November 2025 launch of the i-MX95 Modules for Edge AI Systems reflects an emphasis on enhancing edge computing capabilities in commercial and industrial environments, reinforcing the broader industry shift toward localized inference and faster decision cycles.
- Kontron AG delivers commercial off-the-shelf embedded computing solutions designed for merchant and industrial use cases, emphasizing rapid deployment and integration flexibility.
- Curtiss-Wright Corporation supplies rugged merchant embedded computing systems tailored for mission-critical and payment applications, where reliability under demanding conditions is a defining procurement criterion.
- Mercury Systems, Inc. manufactures high-performance merchant embedded computing boards and modules for defense and industrial integration, bringing ruggedized performance and specialized engineering to sectors with stringent operational requirements.
- ARBO R Technology Corporation provides compact merchant embedded computing solutions tailored for edge and payment systems, addressing the need for space-efficient, high-density deployments.
- AAEON Technology Inc. sells fanless and rugged merchant embedded computing platforms for industrial and commercial deployments, aligning product design with thermal management and environmental resilience demands.
- Avalue Technology Inc. offers ready-to-integrate merchant embedded computing systems for digital payment and automation applications, reducing time-to-deployment for enterprises seeking streamlined integration paths.
- IEI Integration Corp. delivers specialized merchant embedded computing hardware for payment and edge computing platforms, reflecting a focused approach to transaction-adjacent and edge processing workloads.
- DFI Inc. manufactures merchant embedded computing solutions integrated into retail and industrial devices, underscoring the convergence of embedded platforms with end-device ecosystems.
The competitive picture is not static. Recent product launches illustrate a market where edge AI capabilities, processing speed, and ruggedization are becoming baseline expectations rather than differentiators. Companies that can harmonize performance with compliance readiness, interoperability, and integration ease are likely to capture disproportionate value as procurement teams prioritize total cost of ownership and deployment certainty over raw specification comparisons.
Market Dynamics and Operating Realities in 2026
Strategic planning for merchant embedded computing cannot rely on growth projections alone. Several industry dynamics are actively reshaping procurement criteria, product design, and deployment economics:
- Regulatory and certification pressure: The EU AI Act and CE marking requirements under the EU Green Deal are tightening energy-efficiency and safety-certification standards for embedded systems. Simultaneously, PCI DSS compliance is required for all merchant embedded computing platforms integrated into digital payment solutions. These requirements are elevating the importance of pre-certified platforms, documented compliance trails, and engineering partnerships with demonstrated regulatory fluency.
- Cost and supply constraints: Rising chip costs and a shortage of skilled professionals have impacted a significant share of SMEs operating in the merchant embedded computing sector. For larger enterprises, this environment increases the value of supply chain resilience, component availability guarantees, and design-in support that reduces integration risk.
- Standardization and interoperability gaps: Limited standardization and interoperability among embedded computing systems continues to pose a major challenge. Enterprises seeking to scale deployments across sites or integrate with legacy equipment must account for integration friction, custom bridging costs, and long-term maintenance implications.
- Application concentration and demand signals: Industrial and factory automation applications represent close to 36 percent of total demand for merchant embedded computing platforms, reinforcing the centrality of operational technology environments in market growth. This concentration also highlights where performance, durability, and real-time processing requirements are most acute.
Together, these dynamics create a more demanding procurement environment. Enterprise buyers are increasingly evaluating platforms not only on technical capability, but on compliance readiness, integration predictability, lifecycle support, and alignment with regional regulatory frameworks. The companies that succeed in this environment will be those that can reduce deployment uncertainty while delivering performance that matches mission-critical expectations.
Why This Research Matters for 2026 Decision-Making
The merchant embedded computing market is entering a phase where strategic foresight directly affects competitive positioning. Growth is steady, but the path to capturing value is becoming more nuanced. Procurement leaders must navigate certification requirements, component cost volatility, interoperability constraints, and a competitive field where product launches increasingly emphasize edge AI and higher-throughput processing. In this environment, high-level market awareness is insufficient. Decision-makers need structured, scenario-ready intelligence that connects market size and growth trajectory to application demand, regional dynamics, technology evolution, and competitor behavior.
This research is designed to fill that gap. By grounding its analysis in verified historical data, transparent forecasting methodology, and detailed competitive and regulatory context, the report provides a practical foundation for:
- Aligning capital allocation and procurement cycles with credible growth trajectories rather than optimistic assumptions.
- Evaluating product portfolios and integration strategies against application-specific demand concentration and deployment constraints.
- Anticipating regulatory and certification impacts on platform selection, particularly in payment-adjacent and energy-sensitive environments.
- Mapping competitive positioning to identify where incumbents hold scale advantages and where emerging capabilities may reshape procurement preferences.
- Structuring partnership, sourcing, and market-entry decisions around interoperability, lifecycle support, and regional demand realities.
Access the Full Strategic Blueprint
The merchant embedded computing market is expanding with discipline, but the complexity beneath the headline numbers is where strategic advantage is won or lost. From technology-type differentiation and application-driven demand patterns to regional deployment dynamics and competitive maneuvers, the full report provides the depth required to make informed, forward-looking decisions in 2026 and across the forecast horizon to 2032.
To move from directional awareness to execution-ready intelligence, we invite you to access the complete study. The full market research includes detailed segmentation analysis, comprehensive company profiling, scenario-driven forecasts, and operational context that equips enterprises to translate market growth into concrete strategic action.
For detailed analysis of this topic, please visit the official page: The Merchant Embedded Computing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


