



PW Consulting: Precision Tubes Market Reaches $24.39 Billion in 2025, Projected to Hit $32.25 Billion by 2032

Precision Tubes Market 2026: Navigating Growth, Consolidation, and Strategic Differentiation
The global precision tubes market stands at a pivotal inflection point as industrial supply chains recalibrate around performance, traceability, and speed-to-delivery. As we enter the 2026 decision cycle, organizations across aerospace, automotive, energy, medical, and mechanical engineering sectors are confronting a landscape defined by steady structural expansion, concentrated competitive positioning, and an accelerating premium on specialized manufacturing capabilities. Our latest research, Precision Tubes Market, distills a comprehensive view of this evolution, mapping historical trajectories, forward-looking demand signals, and the operational levers that will separate resilient players from those caught in margin compression.
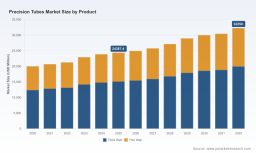
This market has demonstrated consistent compounding growth over the past half-decade, with total revenue progressing from a baseline in 2020 to an estimated valuation approaching the mid-twenty-four-thousand-million-dollar range by 2025. The forecast horizon extending through 2032 projects a compound annual growth rate of 4.2 percent, pointing toward a market size that surpasses thirty-two-thousand-million-dollar milestones in the early 2030s. These figures reflect more than incremental expansion; they encode a broader industrial narrative in which tighter tolerances, alloy specialization, and application-critical reliability are increasingly non-negotiable. For executives planning capacity, procurement, and partnership strategies in 2026, the directional signal is unambiguous: demand is durable, but the value migration is tilting decisively toward precision, certification, and differentiated service models.
The strategic weight of this research lies not in headline magnitudes alone, but in the way these trajectories intersect with procurement cycles, capital allocation windows, and risk management frameworks. Organizations that treat the precision tubes category as a commoditized input risk overlooking the structural shift toward engineered solutions, where lead-time guarantees, material traceability, and regulatory alignment directly influence winning margins. Our analysis translates the macro arc into decision-ready context, helping leadership teams separate temporary pricing noise from durable demand drivers and identify where to invest, consolidate, or re-skill for the years ahead.
Structural Demand Drivers Across End-Use Verticals
Demand for precision tubes is being reshaped by application-specific performance requirements rather than generic volume growth. In automotive systems, the convergence of powertrain evolution, lightweighting objectives, and chassis and safety integration continues to place pressure on component suppliers to deliver predictable tolerances at scale. Energy infrastructure remains a steady anchor, where high-integrity tubing supports operational continuity and long-service-life expectations in demanding environments. Mechanical engineering applications blend broad industrial usage with specialized fabricated components, while medical device manufacturing represents a high-value niche where material biocompatibility, dimensional consistency, and process validation carry disproportionate weight.
These end-use forces are not uniform in cadence. Some segments are being pulled by regulatory and safety mandates, others by product innovation cycles, and others by replacement and maintenance demand in mature installed bases. Our report unpacks how these heterogeneous drivers interact with the broader market, helping readers understand where growth is cyclical, where it is structural, and where apparent softness may mask a shift in requirement complexity rather than a decline in volume.
Product Architecture and Manufacturing Complexity
The precision tubes category spans a spectrum of product architectures, with thick-wall and thin-wall solutions occupying distinct technical and commercial positions. Thick-wall tubes are often associated with structural integrity, pressure containment, and high-stress industrial uses, while thin-wall variants align with weight-sensitive applications, intricate fabrication, and specialized alloy requirements. The relevant distinction for 2026 is not simply geometry, but the manufacturing precision, inspection rigor, and finishing capability that determine whether a supplier can reliably meet mission-critical specifications at acceptable lead times.
Underlying these product forms is a processing chain that begins with steel strip and proceeds through multiple stages, including acid pickling and cold rolling to achieve closer dimensional tolerances. This dependence on tightly controlled feedstock and processing discipline means that raw material availability, processing consistency, and yield management have become strategic variables rather than operational backdrops. Suppliers that can integrate material control, machining precision, and finishing flexibility are better positioned to absorb volatility and preserve margin integrity.
Competitive Landscape: Concentration, Capability, and Recent Signals
The market remains moderately consolidated, with a limited number of established players accounting for a meaningful share of industry revenue. This concentration suggests that large-scale equivalence in product capability is less important than differentiated positioning in alloy expertise, dimensional reliability, and customer-facing service programs. The competitive frontier is increasingly defined by how effectively firms combine precision manufacturing with certification, responsiveness, and installed-base trust.
Polystyrene Tubes Market
Several leading participants illustrate the breadth of strategic postures now shaping the field. Superior Tube Co., based in Collegeville, Pennsylvania, specializes in small-diameter, thin-wall seamless and welded precision tubes in stainless steel, nickel, titanium, and zirconium alloys for mission-critical aerospace, defense, and medical applications. Fine Tubes, headquartered in Plymouth, United Kingdom, manufactures high-precision seamless and welded tubes in stainless steel, titanium, and nickel alloys to exacting specifications for critical applications, and supports time-sensitive requirements through a dedicated Express Program for faster delivery. Pennar Industries Limited, operating from Hyderabad, India, produces ERW, CDW, and stainless precision tubes in round, square, rectangular, and profiled forms, with capacity scaled to support automotive, boiler, general engineering, and structural uses under conforming standards. Mannesmann Precision Tubes GmbH, based in Dortmund, Germany, offers seamless, drawn, welded and drawn, and size-rolled precision steel tubes across various shapes for automotive safety, driveline, engine, chassis, and industrial applications. Precision Tube Company, located in New Market, Virginia, has manufactured non-ferrous cold-drawn seamless tubes and pipes since 1932, covering copper, aluminum, brass, bronze, nickel silver, and cupro-nickel in diameters from 0.010 inches to 3.625 inches, alongside fabrication services including bending and forming. AMETEK Specialty Metal Products, also headquartered in Collegeville, Pennsylvania, operates as a global leader in precision metal tubing for critical aerospace, space, defense, and medical applications, and recently strengthened tube segment operations through leadership appointments and expanded processing capabilities.
Recent developments reinforce the direction of travel. In late 2025, Fine Tubes achieved Merit Status across all Nadcap Approvals, a milestone with direct relevance for customers in regulated sectors where audit readiness and process credibility are gatekeeping requirements. That same period saw the company report major water savings through the implementation of submetering systems, reflecting a broader operational emphasis on resource efficiency and sustainability metrics that increasingly influence supplier evaluations. In early 2026, Fine Tubes introduced its Express Program, enabling delivery of high-precision tubes in approximately ten weeks, a capability that directly addresses the premium many engineering buyers place on schedule certainty. At the corporate level, AMETEK Specialty Metal Products expanded tube processing capabilities through the acquisition-related integration of Coining into its specialty metal products operations in 2025, while appointing a new Business Segment Controller for its precision tube businesses to advance financial performance and control processes. Separately, Amari Precision Tubes exhibited at Tube Düsseldorf in April 2026, signaling continued engagement with the industrial exhibition circuit as a platform for visibility, partnership development, and technology demonstration.
These moves should be read as more than isolated news items. They reflect converging priorities: certification depth, environmental performance, lead-time compression, processing expansion, and financial control discipline. In a market where top-tier players command a meaningful share of revenue, such capabilities are often the practical differentiators that determine procurement preference, pricing power, and resilience in constrained supply conditions.
Regional Demand Patterns and Strategic Implications
The geography of precision tube demand is uneven, shaped by the location of end-use manufacturing clusters, industrial infrastructure investment, and regional supply chain preferences. Different regions reflect distinct mixes of automotive production, energy activity, mechanical engineering demand, and medical device manufacturing, which in turn influence the type of tube specifications most frequently required. Our analysis places this regional variation in context without reducing it to simplistic rankings, allowing readers to focus on how local demand profiles interact with global sourcing strategies, tariff exposure, logistics cost, and supplier proximity requirements.
Precision Tubes Market
For multinational procurement teams, regional divergence is not only a sourcing consideration; it is a risk and flexibility variable. Diversifying qualified suppliers, understanding regional certification and standards expectations, and aligning inventory strategy to regional lead-time realities can materially improve supply assurance. The report explores these dynamics in a manner designed to support scenario planning rather than static allocation models.
What the Report Delivers for 2026 Decision-Making
Precision Tubes Market is structured to support actionable decisions across strategy, procurement, sales, and operations. It connects historical performance with forward-looking projections, while embedding market structure, competitive behavior, and operational realities into a single decision framework. The objective is to give leadership teams a basis for prioritizing investments, qualifying suppliers, and anticipating shifts in buyer expectations before they become apparent in transactional data.
- Macro revenue trajectory and growth rate context across the historical period and forecast horizon, framed for capacity, portfolio, and market-entry planning
- Product-side perspective on thick-wall and thin-wall positioning, including the manufacturing and quality implications that influence buyer selection
- End-use demand context across automotive, energy, mechanical engineering, medical, and other segments, with attention to structural versus cyclical forces
- Regional demand context that supports sourcing strategy, risk diversification, and market prioritization without overgeneralization
- Competitive landscape assessment centered on capability differentiation, concentration dynamics, and the strategic significance of certification, service speed, and processing breadth
- Recent industry developments interpreted as signals of where value, compliance, and operational advantage are being created
- Practical guidance for interpreting pricing, lead-time, and qualification dynamics in a market where specification integrity and reliability increasingly determine commercial outcomes
Throughout the report, we maintain a disciplined focus on interpretation over enumeration. The goal is to help readers understand not only what the numbers imply, but how to act on them in procurement negotiations, plant planning, supplier qualification, and regional expansion decisions.
How to Use This Intelligence in 2026
Market intelligence is most valuable when it changes behavior, not just perspective. For 2026, we recommend that decision-makers use this research to pressure-test assumptions about category maturity, supplier resilience, and the commercial relevance of precision specifications. Organizations should examine whether their sourcing models adequately reward certification readiness, process control, and delivery reliability, or whether they remain overly exposed to price-driven competition in a segment where differentiation is increasingly technical and service-based.
At the same time, the forecast horizon through 2032 provides a longer runway for strategic planning. Even at a measured growth rate, the cumulative effect of expansion creates both opportunity and strain: opportunity for firms that can scale precision capability responsibly, and strain for those that must manage raw material volatility, skilled processing capacity, and tightening customer expectations simultaneously. Our analysis is designed to make those trade-offs visible early enough for deliberate action.
Conclusion: Precision as the Strategic Common Denominator
The precision tubes market is not entering 2026 as a static commodity arena. It is an engineered-market environment in which growth is real, competition is concentrated, and differentiation is increasingly defined by specification fidelity, certification depth, and responsive service. The macro trajectory supports continued expansion, but the commercial winners will be those who translate that trajectory into operational advantage: tighter control over material and processing variability, stronger alignment with regulated end-use requirements, and a credible ability to compress lead times without compromising integrity.
This report offers the context necessary to make those choices with confidence. For organizations seeking the full segmentation breakdown, regional and application detail, and the complete competitive intelligence package, the full Precision Tubes Market study provides the comprehensive dataset and interpretive framework needed to move from high-level insight to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Precision Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


