



PW Consulting Reports Aluminum Ladder Market Reaches USD 2.42 Billion in 2025, Projects 5.25% CAGR to 2032

Strategic Intelligence for the Aluminum Ladder Market: Navigating Growth, Compliance, and Supply Chain Volatility Through 2032
The global aluminum ladder market stands at a critical inflection point. As we transition from the base year of 2025 into the forecast horizon extending through 2032, industry stakeholders face a complex matrix of steady revenue expansion, intensifying regulatory scrutiny, and persistent raw material pressure. Our latest market research publication is designed not merely as a statistical repository, but as a strategic decision-making engine for executives, procurement leaders, product developers, and capital allocators who require forward-looking intelligence to secure competitive advantage.
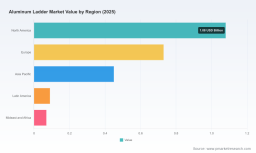
Over the historical window of 2020 through 2025, the market demonstrated remarkable resilience and structural maturation, evolving from a 1.87 billion USD valuation to 2.42 billion USD by the close of the base period. This trajectory underscores a sector that has successfully navigated post-pandemic supply chain recalibrations, shifting construction cycles, and the gradual normalization of industrial maintenance expenditures. Looking ahead, the compound annual growth rate of 5.25 percent projects the market toward a 3.46 billion USD endpoint by 2032. While these headline figures provide essential macro context, the true strategic value of our analysis lies beneath the surface: in the granular segmentation dynamics, competitive maneuvering, regulatory friction points, and material cost sensitivities that will dictate margin preservation and market share acquisition for the next seven years.
Aluminum Ladder Market
The Strategic Architecture of the 2026 Decision Cycle
Corporate planning cycles for 2026 demand more than retrospective trend extrapolation. They require scenario-ready intelligence that accounts for the asymmetric forces currently reshaping the aluminum ladder ecosystem. Procurement managers must weigh fluctuating feedstock economics against contractual pricing strategies. Product strategists need to understand how safety certification evolution is altering feature prioritization and manufacturing compliance costs. Regional growth managers require clarity on where demand density is concentrating and where capacity expansion is most urgently warranted.
Our report dissects these interlocking variables through a structured analytical framework. The historical performance review traces the market’s evolution from 2020, mapping inflection points where demand elasticity shifted, where regional supply constraints triggered pricing recalibration, and where substitution threats from alternative materials gained or lost traction. The forecast architecture then projects these dynamics forward, isolating the structural drivers that will sustain growth momentum through 2032 while identifying the potential headwinds that could compress profitability if left unaddressed.
Crucially, the research does not treat market size as an abstract number. It contextualizes revenue progression within the operational realities of capacity utilization, inventory turnover, lead-time optimization, and channel distribution efficiency. Decision-makers who engage with this analysis will be equipped to answer foundational strategic questions: Where should manufacturing capacity be allocated to maximize return on invested capital? Which product configurations align with the fastest-growing end-user requirements? How should pricing architectures be structured to absorb raw material volatility without eroding customer loyalty?
Report Content Overview: Translating Data into Operational Playbooks
The publication is engineered for immediate applicability across functional teams. Rather than presenting isolated metrics, the analysis integrates quantitative modeling with qualitative assessment to produce actionable insights across multiple dimensions of market engagement.
At the core of the research is a comprehensive segmentation architecture that examines demand distribution across product configurations, end-user environments, and geographic corridors. The structural breakdown illuminates which ladder architectures are capturing disproportionate revenue share, which application verticals are driving incremental volume, and which regional markets are exhibiting the strongest expansion signals. The analysis deliberately avoids superficial aggregation, instead revealing the underlying demand logic that explains why certain configurations outperform others in specific operational contexts.
The competitive profiling section maps the strategic positioning of incumbent manufacturers, emerging challengers, and niche specialists. Each profiled entity is evaluated against a consistent analytical rubric: product portfolio breadth, material specification standards, compliance certification footprint, geographic manufacturing presence, and recent strategic maneuvering. This approach enables readers to benchmark their own operational posture against industry leaders and identify whitespace opportunities where incumbents may be under-serving particular customer segments or geographies.
Supply chain and cost structure analysis forms another critical pillar of the research. The report integrates upstream material economics, energy cost exposure, transportation logistics constraints, and procurement risk indicators into a cohesive narrative that explains how margin structures are likely to evolve. This dimension is particularly vital for organizations that rely on aluminum-intensive product lines, as the intersection of raw material price fluctuations, energy-driven smelting economics, and export policy shifts can materially alter cost-of-goods-sold trajectories.
The regulatory and compliance module examines the evolving safety standards landscape, focusing on how certification requirements, load-capacity mandates, and inspection protocols are shaping product design constraints and market access barriers. For manufacturers operating across multiple jurisdictions, understanding the harmonization—or fragmentation—of compliance expectations is essential for scaling production efficiently while maintaining market legitimacy.
Competitive Landscape Analysis: Incumbents, Innovators, and Strategic Maneuvering
The aluminum ladder market is characterized by a moderately concentrated competitive structure, with the top three players commanding approximately 48.5 percent of industry revenue and the top five entities consolidating around 60.2 percent. This concentration pattern indicates a sector where scale advantages, brand equity, and compliance infrastructure create meaningful barriers to entry, yet where specialized manufacturers and regional players continue to secure defensible positions through product differentiation, material specialization, and customer intimacy.
Werner Co., headquartered in Chicago, Illinois, remains a dominant force in the professional-grade segment. Its portfolio emphasizes aluminum extension ladders and stepladders engineered for construction, maintenance, and industrial applications, with a comprehensive range of heights and load capacities designed to satisfy OSHA standards. Werner’s market posture reflects a commitment to specification reliability and occupational safety alignment, positioning its offerings as default infrastructure for job-site procurement and fleet standardization programs.
Louisville Ladder, based in Louisville, Kentucky, pursues a heavy-duty orientation that spans extension, attic, and fire-rated models tailored for professional and industrial deployment. The company’s strategic emphasis on durability and application-specific engineering has allowed it to maintain strong relationships with trade professionals and institutional buyers who prioritize lifecycle performance over initial acquisition cost.
Little Giant Ladder Systems, operating from Springville, Utah, has carved a distinctive position through multi-position and innovative aluminum configurations that offer versatile access solutions in professional environments. The company’s recent acquisition of a regional manufacturer specializing in eco-friendly aluminum alloys signals a deliberate expansion into sustainable material portfolios, aligning product innovation with the growing procurement emphasis on environmental performance metrics.
Alaco Ladder Company, located in Chino, California, distinguishes itself through heavy-duty and specialty aluminum ladders fabricated from aircraft-grade 6061-T6 alloy. Its product range encompasses stepladders, extension ladders, fire-rated models, and agricultural configurations, all engineered to meet OSHA and ANSI standards. This material specification strategy positions Alaco as a preferred supplier for applications where structural integrity under demanding load conditions is non-negotiable.
Metallic Ladder Manufacturing, based in Western New York, extends the competitive landscape into specialized industrial, maritime, utilities, and aircraft maintenance domains. Its aerospace-grade aluminum ladders, stairs, gangways, and work platforms address niche access requirements where conventional residential or light-commercial products are insufficient. This specialization creates a defensibility moat rooted in technical certification, application expertise, and customer-specific engineering support.
O’Keeffe’s Inc., manufacturing in Merced, California since 1939, offers commercial and industrial fixed aluminum ladders, platforms, crossovers, ramps, catwalks, and stairs. Its long operational history and USA-made positioning provide a trust premium in procurement environments where domestic manufacturing provenance, quality consistency, and institutional familiarity influence sourcing decisions.
Cotterman Company, with multiple locations across Michigan, focuses on rolling metal ladders and access systems serving industrial, commercial, and MRO markets. Its product orientation reflects an understanding of facility maintenance workflows, where mobility, durability, and integration with existing infrastructure determine adoption velocity.
On the international front, Hailo Werk and ZARGES GmbH, both headquartered in Germany, reinforce the European competitive axis. Hailo delivers professional-grade aluminum ladders, steps, and access equipment for industrial and commercial applications, while ZARGES emphasizes durable aluminum ladders and access systems for professional trade and industrial use. Their presence underscores the globalized nature of the competitive field and the importance of cross-border benchmarking for manufacturers evaluating export opportunities or import threats.
Precision Ladders, operating in the USA, supplies OSHA-compliant aluminum ladders and stairs targeting architects, engineers, and contractors in commercial and industrial settings. Its positioning illustrates how specification alignment with design professionals can create demand pull-through that bypasses traditional transactional purchasing channels.
ShangShuo Ladder, based in China, represents the export-oriented production model, offering professional aluminum telescopic, folding, and extension ladders with OEM customization capabilities for global distribution. Its business model highlights the dual dynamics of cost-competitive manufacturing and the growing demand for supplier flexibility in international procurement networks.
Recent Strategic Developments Shaping the 2026 Competitive Rhythm
The competitive rhythm has accelerated considerably in the first months of 2026, with several strategic actions signaling where industry leadership is being contested.
In March 2026, Werner Co. launched a new line of smart folding ladders featuring IoT-enabled safety sensors for load capacity and stability monitoring. This product introduction reflects a broader industry trajectory toward embedded monitoring technology, where real-time structural feedback and usage analytics are increasingly viewed as differentiators in fleet management, risk mitigation, and warranty optimization. The move signals that digital integration is no longer confined to high-tech sectors but is becoming a credible value proposition in essential access equipment.
In January 2026, Little Giant Ladder Systems completed the acquisition of a regional manufacturer specializing in eco-friendly aluminum alloys. This transaction directly enhances its sustainable product portfolio and suggests a strategic recognition that material provenance and environmental performance are transitioning from peripheral considerations to procurement criteria with tangible commercial consequences. The acquisition likely positions the company to respond more nimbly to customer demands for lower-carbon supply chains and recyclable material specifications.
In February 2026, Gorilla Ladders partnered with a safety certification body to develop standardized compliance certification for lightweight foldable aluminum ladders. This initiative addresses a market gap where the proliferation of compact, portable configurations has occasionally outpaced unified testing protocols. Standardization can reduce buyer uncertainty, streamline procurement comparisons, and create a certification moat that rewards manufacturers willing to invest in third-party validation.
In April 2026, Louisville Ladder expanded its manufacturing facility in Southeast Asia to meet demand in emerging markets and reduce lead times. This capacity move illustrates the geographic rebalancing that many established manufacturers are pursuing: serving growth corridors closer to end demand while mitigating long-haul logistics costs and currency exposure. The expansion also reflects confidence that emerging-market construction, maintenance, and industrial activity will sustain incremental volume growth that justifies proximity-based production.
Market Dynamics and Structural Risks: Material Economics, Compliance, and Geopolitical Friction
No strategic assessment of the aluminum ladder market is complete without confronting the structural vulnerabilities that can compress margins, interrupt supply continuity, or alter competitive accessibility. The 2026 operating environment requires executives to monitor several interlocking pressure points.
Raw material economics remain a primary concern. Average prices for U.S. imports of crude dry bauxite and metallurgical-grade material rose 4 percent and 9 percent respectively in 2025, reaching 31 dollars per ton and 595 dollars per ton. While these input cost movements do not translate one-to-one into finished ladder pricing, they establish a higher baseline for alloy procurement and exert upward pressure on manufacturing cost structures. Organizations that have not institutionalized raw material hedging, supplier diversification, or design-for-material-efficiency strategies may find their gross margins increasingly exposed.
The domestic primary aluminum landscape in the United States further complicates cost visibility. The sector operates with only six smelters, four of which are partially or fully curtailed due to high electricity prices and subsidized international competition. This structural concentration means that domestic aluminum availability can be sensitive to energy market fluctuations and trade dynamics, creating procurement uncertainty for manufacturers reliant on domestically sourced feedstock. Even when imports fill gaps, the price and availability of those imports can be influenced by international supply conditions and logistical bottlenecks.
Geopolitical developments in bauxite-exporting regions have added another layer of supply-side caution. Stricter controls on bauxite exports in Guinea have intensified concerns over tighter raw material supplies in the global aluminum sector. For ladder manufacturers and downstream alloy processors, this translates into a need for longer-term supply contracts, diversified sourcing geography, and scenario planning that accounts for potential export restriction escalation. The strategic implication is clear: resilience in material procurement is no longer a contingency exercise but a core operational capability.
Regulatory compliance continues to shape both product design and market access. OSHA standard 1926.1053 mandates that ladders shall not be loaded beyond the maximum intended load for which they were built, nor beyond their manufacturer’s rated capacity. While this requirement is foundational to occupational safety, it also reinforces the importance of accurate load-capacity labeling, consistent quality control, and documentation integrity. Manufacturers that treat compliance as a static checkbox rather than an embedded design constraint risk product recalls, liability exposure, and reputational damage. Conversely, those that integrate compliance transparency into their product positioning can use it as a trust signal in professional and institutional procurement environments.
Why This Research Matters for 2026 Executive Decision-Making
The strategic value of this market research lies in its capacity to convert complex, multi-variable market signals into coherent decision frameworks. For capital allocation teams, the analysis illuminates where capacity expansion, product line investment, and geographic entry are most likely to generate defensible returns. For product development leadership, it clarifies which configurations, material specifications, and compliance certifications are aligned with accelerating demand. For procurement and supply chain executives, it maps the cost-structure risks and sourcing strategies required to maintain margin stability amid raw material and energy volatility.
Ladder Market
The research also serves as a competitive early-warning system. By tracking recent product launches, acquisitions, certification partnerships, and manufacturing expansions, the report reveals where incumbents are reinforcing their positions and where gaps may be opening for agile entrants. Understanding these maneuvers enables organizations to anticipate competitor responses, adjust pricing architectures, and refine channel strategies before market shifts become fully-priced into competitive dynamics.
For organizations evaluating market entry or expansion, the segmentation insights provide a structured way to assess addressable demand without relying on blunt aggregate figures. The analysis identifies which application verticals are driving volume growth, which product architectures are capturing disproportionate share, and which regional corridors exhibit the strongest expansion signals. This level of clarity enables more precise go-to-market planning and resource allocation.
Accessing the Complete Strategic Intelligence
The narrative synthesized in this introduction represents only the observable surface of a far more detailed analytical structure. The full market research publication contains the segmented demand breakdowns, the competitive benchmarking matrices, the cost-structure sensitivity models, the regulatory compliance mapping, and the scenario-based forecast architectures that executives require to translate market intelligence into operational action.
To access the complete dataset, vendor profiles, regional demand narratives, and strategic recommendation frameworks, we invite decision-makers to visit the source research portal. There, the full Aluminum Ladder Market report provides the depth, granularity, and forward-looking modeling necessary to support confident 2026 planning and position your organization advantageously through 2032.
For detailed analysis of this topic, please visit the official page: Aluminum Ladder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


