



PW Consulting: USB Wall Socket Market Hits $406M in 2025, Forecasting 5.8% CAGR to $601M by 2032

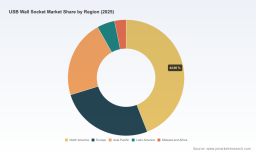
Strategic Intelligence for the Modern Power Infrastructure: Inside the 2026 USB Wall Socket Market
The built environment is undergoing a quiet but irreversible transformation. As devices become more power-hungry, form factors shrink, and safety codes evolve, the traditional wall receptacle is no longer just a passive conduit for electricity. It is becoming an intelligent, integrated charging hub. For manufacturers, distributors, specifiers, and investors operating in electrical infrastructure, understanding where this transition is headed is no longer optional. It is a prerequisite for capital allocation, product roadmapping, and competitive positioning.
Our newly released market research on the USB Wall Socket Market is designed to meet that imperative. This report is not a superficial snapshot. It is a decision-grade intelligence asset built to help industry leaders navigate the 2026 landscape with clarity, anticipate structural shifts before they materialize, and convert market complexity into actionable advantage.
The Macro Trajectory: What the Numbers Are Telling Us
Over the historical window from 2020 through 2025, the USB wall socket segment has demonstrated consistent expansion, reflecting the accelerating integration of built-in charging capabilities into residential, commercial, and specialized electrical installations. In 2020, the market operated at a baseline that would soon be tested by supply chain volatility, shifting demand patterns, and rapid product evolution. By 2025, that trajectory had matured into a substantially larger revenue base, a signal that USB-integrated receptacles have crossed from niche innovation to mainstream electrical specification.
Looking forward, the forecast period spanning 2026 through 2032 indicates a market that continues to scale with disciplined momentum. Our analysis projects a compound annual growth rate of 5.8 percent across the forecast horizon, measured in USD million. This isn't a story of speculative hype. It is a reflection of durable demand drivers: the proliferation of USB-C and high-power charging standards, the standardization of code-compliant built-in receptacles, and the ongoing substitution of adapters and power bricks with permanent wall-integrated solutions. The forecast contours reveal a market that is scaling predictably but not uniformly, with growth concentrating in product architectures and application environments where functional differentiation, regulatory compliance, and installer adoption align.
From a strategic perspective, the critical insight is not simply that the market is growing. It is that the composition of that growth is shifting. Product portfolios, certification pathways, regional deployment economics, and end-use case suitability are becoming the real differentiators. Companies that treat USB wall sockets as commoditized commodities will find themselves exposed to margin compression and specification displacement. Those that treat them as engineered infrastructure components with distinct performance, compliance, and total-cost profiles will be positioned to capture disproportionate value.
USB Wall Charger Market
The 2026 Inflection Point: Why This Research Matters Now
2026 is not an arbitrary forecast year. It is a practical inflection point where several concurrent forces are converging. Electrical codes and safety standards continue to tighten, placing greater emphasis on listed, tamper-resistant solutions that can satisfy both residential and commercial installation requirements. Installers and specification professionals are increasingly weighing not just unit price, but labor efficiency, code alignment, durability, and end-user charging performance. Meanwhile, product manufacturers are iterating rapidly across port configurations, charging protocols, form factors, and application-specific variants, creating a more fragmented but opportunity-rich competitive field.
This is precisely where a structured, evidence-driven market assessment becomes strategically valuable. In an environment where product announcements, catalog updates, and compliance positioning are accelerating, decision-makers need a coherent framework to separate signal from noise. Our report provides that framework. It helps leadership teams answer the questions that actually move the needle: where demand is structurally expanding, which product architectures are gaining specification traction, how regulatory and certification dynamics are reshaping procurement behavior, and what competitive responses are most likely to hold up over a multi-year planning horizon.
The value of this research is not in offering a single headline number. It is in connecting the macro trajectory to the operational realities of product strategy, channel positioning, and competitive response. That integration is what turns information into intelligence, and intelligence into decision-ready strategy.
What the Report Delivers: A Practical Roadmap for Decision-Makers
This market research is built for execution, not just orientation. It translates market sizing and forward estimates into a structured diagnostic that leadership teams can plug directly into planning processes. The report is organized to support a wide range of strategic functions, from product portfolio review and pricing strategy to market-entry evaluation and competitive benchmarking.
At its core, the report maps the market across the dimensions that matter most to commercial and operational strategy. It examines how product configurations are shaping demand patterns, how application environments are influencing specification behavior, and how regional deployment contexts create distinct opportunities and constraints. Rather than presenting isolated statistics, the analysis situates each dimension within the broader commercial logic of the market, allowing readers to understand why certain segments are expanding, where substitution risks are building, and what factors determine adoption velocity.
Equally important, the report provides a thorough competitive landscape assessment. USB wall sockets are no longer dominated by a single product philosophy or supply model. The field spans established electrical manufacturers with strong code-compliance and distributor relationships, specialized players targeting demanding environments, and modular-component producers shaping cost and customization dynamics. Understanding how these players position themselves across residential, commercial, and specialized applications is essential for any company evaluating its own competitive stance.
USB Wall Socket Market
The research also addresses the operational and regulatory forces that increasingly shape procurement and specification. Safety listing requirements, tamper-resistance expectations, manufacturing location dynamics, and material construction approaches are not peripheral concerns. They are becoming integral to product credibility, installer confidence, and purchasing decisions. By integrating these factors into the market narrative, the report gives readers a more realistic view of where commercial advantage is being created and defended.
Competitive Landscape: Who Shapes the Market and How
The USB wall socket market is defined by a diverse set of manufacturers, each bringing a distinct product philosophy, geographic footprint, and application emphasis. The competitive structure is concentrated enough that a relatively small group of players exerts meaningful influence over specification trends, yet broad enough that targeted differentiation can still create viable niches. Our analysis examines how these companies are competing across product architecture, compliance positioning, and end-use specialization.
Major electrical infrastructure names continue to anchor large portions of the market. Leviton Manufacturing Co., Inc., headquartered in Melville, New York, has positioned USB wall outlets around code-aligned, tamper-resistant designs for residential and commercial applications, with a notable emphasis on North American manufacturing to address both compliance expectations and cost dynamics associated with labor and material sourcing. Eaton Corporation PLC, based in Dublin, Ireland, has focused its USB receptacles and duplex outlet offerings on fast charging directly from standard wall outlets, aligning product presentation with evolving code considerations. Legrand North America, located in Westlake Village, California, has expanded its residential wiring device portfolio with USB and combination receptacles that span USB-A and USB-C charging ports. Schneider Electric USA, in Norwalk, Connecticut, has introduced USB charger and socket-outlet combinations that integrate 15A sockets with USB-A and USB-C ports, appealing to applications that require both traditional receptacle function and integrated charging.
At the same time, specialized and component-oriented manufacturers are carving out distinct positions. Scanstrut Ltd, from the United Kingdom, has pushed into rugged, waterproof marine and RV applications with dual USB-C sockets designed for demanding overland and mobile environments. Yih Sean Enterprise Co., Ltd., based in Taiwan, has focused on marine-grade double-port USB charger sockets with touch-button controls for boats and marine electronics. ELEGRP, operating from China, has emphasized tamper-resistant USB wall outlets with Type-A and Type-C ports for residential and commercial use. Bull Electric, in Shanghai, has built product lines around modular-style USB socket series and related power connectors oriented toward household and smart applications. CNC Electric, also based in China, has concentrated on modular USB socket products and low-voltage electrical components, leveraging integrated plastic and metal construction approaches.
This landscape matters because competition in USB wall sockets is no longer solely about port count or price. It is increasingly about where a product is qualified to be specified, how well it aligns with installation realities, and whether its design language fits the expectations of a given end-use environment. Companies that understand these competitive layers can better anticipate where share is vulnerable, where new entries are likely to gain traction, and how to structure product messaging for maximum specification impact.
Industry Dynamics: Regulation, Compliance, and the New Cost Logic
Several regulatory and operational dynamics are reshaping the USB wall socket market in ways that directly influence strategy. One of the most significant is the growing emphasis on compliance and safety listing. Across the market, products must meet UL listing expectations and tamper-resistance requirements to satisfy safety standards. This is not a superficial checkbox. It is increasingly a precondition for specification, procurement approval, and installer confidence. The practical effect is that regulatory readiness has become a competitive asset, and companies that integrate compliance into product development from the outset are better positioned to capture institutional demand.
At the same time, certification and code alignment are influencing product roadmaps. Several manufacturers are framing their USB receptacles in relation to evolving code expectations and updates relevant to electrical installations. This alignment is not just about avoiding noncompliance; it is about creating products that fit more smoothly into specification workflows and installation practices. In markets where contractors, distributors, and specification professionals must navigate changing standards, products that are presented as code-compatible and installer-friendly can gain disproportionate attention.
Cost structure is also being rethought. Manufacturing location and production model are increasingly part of the commercial conversation. Some leading suppliers are emphasizing North American production for select USB wall outlet lines to address code and compliance expectations while also affecting labor and material cost profiles relative to overseas production. That shift underscores a broader point: even in a globally traded electrical component category, local production economics, supply continuity, and regulatory positioning can create meaningful differentiation. For buyers and competitors alike, understanding where and how products are made is becoming part of evaluating total cost and risk.
Material construction and product modularity further complicate the landscape. Certain manufacturers are differentiating through integrated plastic and metal construction, modular socket architectures, and low-voltage component strategies that influence durability, customization potential, and manufacturing efficiency. These engineering choices may appear technical, but they have direct commercial consequences in terms of unit economics, specification fit, and end-user perception. The market is increasingly rewarding products whose construction and configuration choices support both performance credibility and installation practicality.
Where Strategy Meets the Forecast: What Leaders Should Do Next
The forward-looking shape of this market suggests several strategic priorities for companies operating in electrical infrastructure and built-environment product ecosystems. First, product strategy must be treated as a specification strategy. USB wall sockets are increasingly selected not only for what they do at the point of use, but for how well they fit code expectations, installation routines, distributor availability, and end-user charging demands. Companies that align product development with these specification drivers will be better positioned to secure repeat demand and defend share.
Second, competitive positioning should account for both breadth and specialization. Some players will continue to win through scale, compliance credibility, and broad residential and commercial distribution. Others will compete by targeting demanding applications, rugged environments, or modular component advantages. The strategic question for each organization is not whether to compete in a single way, but where its product, compliance, and channel strengths create the most defensible position in the forecast period.
Third, the regulatory and certification environment should be treated as a core competitive variable, not a background condition. As safety listing, tamper-resistance expectations, and code alignment remain central to market access, companies that invest early in compliant design and clear compliance communication will reduce friction in the specification and procurement process. Those that lag in this area face not only regulatory risk but also commercial friction that can slow adoption regardless of product appeal.
Finally, market growth should be interpreted as an invitation to segment strategically. The forecast indicates durable expansion, but durable expansion does not mean uniform opportunity. The strongest outcomes will likely accrue to organizations that understand which application environments, product architectures, and geographic or channel contexts are generating the most resilient demand, and that concentrate resources accordingly. In a market with meaningful concentration among leading players, disciplined targeting often outperforms unfocused breadth.
Access the Full Intelligence: The Case for Deeper Reading
This article is intended as a strategic preview, not a substitute for the full research. The USB Wall Socket Market report contains the granular segmentation, competitive detail, application context, and forward estimates required to support capital planning, portfolio decisions, and competitive response. The macro trajectory and 5.8 percent forecast CAGR establish the scale and direction of the opportunity. The deeper report explains how that opportunity breaks down across the dimensions that determine commercial execution.
For decision-makers evaluating product roadmaps, pricing architecture, market-entry options, or competitive positioning, the complete report provides the structured evidence needed to move from broad confidence to specific action. It is designed to support conversations with product teams, commercial leadership, and investment stakeholders who need more than directional insight. They need a defensible basis for where to commit, where to differentiate, and where to monitor for disruption.
The USB wall socket market is maturing into a more nuanced, more compliance-defined, and more application-sensitive category than it was even a few years ago. That maturation creates both risk and reward. Companies that understand the market's structure, its competitive logic, and the regulatory forces shaping it will be better prepared to convert forecast growth into durable advantage. We invite you to explore the full research to obtain the complete market intelligence necessary to act with confidence through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: USB Wall Socket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


