



PW Consulting: Global Aircraft Cleaning Chemicals Market to Hit USD 3,771.87 Million by 2032 at 4.3% CAGR

Navigating the Skies: Strategic Intelligence for the Aircraft Cleaning Chemicals Market in 2026
The aviation industry stands at a critical juncture where operational efficiency, regulatory compliance, and environmental stewardship are no longer siloed concerns. They are converging to define the future of aviation ground support. At the heart of this convergence lies the Aircraft Cleaning Chemicals Market, a sector that has evolved from a commoditized supply chain function into a strategic lever for cost optimization and environmental liability management. PW Consulting has meticulously compiled a comprehensive analysis of this sector, designed not merely to report numbers but to illuminate the path forward for enterprise decision-makers navigating the forecast period of 2026-2032. This article serves as a strategic preview of that intelligence, highlighting the macro trends and competitive forces that will define market success in the coming years.
The Macro Trajectory: A Decade of Resilient Expansion
The underlying growth narrative of the aircraft cleaning chemicals sector is robust, grounded in a historical recovery that has matured into a structured expansion. Analysis of data from 2020 through 2025 reveals a market that has successfully absorbed the shocks of global disruption and is now entering a phase of calculated growth. The trajectory indicates a shifting landscape where the total revenue landscape is poised to expand significantly. Starting from a base of approximately 2.2 billion USD in 2020, the market has demonstrated a consistent upward trend, reaching an estimated valuation in 2025.
Looking forward, the forecast period projects a compound annual growth rate of 4.3% through 2032. This is not merely a reflection of increased flight volumes; it is indicative of a deeper transformation in how aircraft are maintained. As the industry pivots toward higher utilization rates and tighter turnaround windows, the demand for high-efficiency, specialized cleaning formulations is accelerating. However, the distribution of this growth is far from uniform. It is being driven by nuanced shifts in product preferences, regional regulatory environments, and the specific operational demands of different aviation segments. Understanding where this growth concentrates—and where it lags—is essential for capital allocation and supply chain strategy.
Product and Application Dynamics: The Interior-Exterior Divergence
A deeper dive into the product architecture reveals a market bifurcated between interior and exterior solutions, each facing distinct demand drivers. The interior-based segment currently commands a slightly larger share of the global revenue, reflecting a heightened post-pandemic focus on cabin hygiene, air quality, and passenger safety. This segment is not just about aesthetics; it involves complex formulations that must meet stringent health standards while ensuring material compatibility with sensitive cabin interiors. Conversely, the exterior-based segment remains critical for aerodynamic efficiency and asset longevity. Factors such as fuel savings derived from clean aerodynamic surfaces and the prevention of corrosion on airframes continue to justify significant investment in exterior maintenance chemicals.
When analyzing application vectors, the distinction between civil aviation and other operational categories is stark. The civil aviation sector dominates the consumption landscape, driven by the sheer volume of passenger flights and the rigorous maintenance schedules of commercial fleets. However, niche applications, including commercial or cargo aviation and military operations, present specific opportunities that require tailored product specifications. The military segment, while smaller in volume, often demands specialized chemical formulations that adhere to unique defense standards, creating a high-barrier-to-entry subsegment for suppliers who can navigate these specific compliance protocols. The interplay between these segments suggests that a one-size-fits-all portfolio strategy is insufficient for capturing maximum market share in 2026 and beyond.
Regional Nuances and the Shift in Global Demand
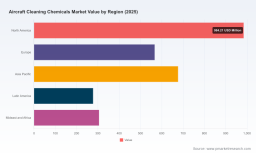
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America continues to represent a substantial portion of the global revenue, bolstered by a mature aviation infrastructure and high operational standards among legacy carriers and MRO providers. Europe, meanwhile, presents a complex dynamic shaped by aggressive sustainability mandates and the aforementioned regulatory shifts. The Asia Pacific region is emerging as a pivotal growth engine, driven by the rapid expansion of airline fleets in emerging markets and increased investment in MRO infrastructure.
Latin America and the Middle East and Africa, while representing smaller shares of the total global revenue, are regions of strategic interest for specific supply chain corridors and cost-optimization opportunities. The variation in demand across these regions underscores the importance of localized regulatory knowledge and supply chain agility. A supplier's ability to navigate the specific chemical registration, disposal regulations, and local content requirements in these diverse economies will be a primary determinant of market penetration success. The regional data suggests that while the global aggregate grows steadily, the regional narratives are diverging, requiring a granular approach to market entry and expansion.
Worldwide Aircraft Wash System Market
Competitive Landscape: Consolidation and Specialized Innovation
The competitive environment is characterized by a moderate level of concentration, with the top three companies accounting for approximately 29.7% of the market and the top five holding roughly 41.8%. This structure suggests a market that is not a pure oligopoly but one where established players hold significant sway, yet there is ample room for specialized competitors to carve out niches through innovation and OEM approvals.
Key players such as Arrow Solutions, based in the United Kingdom, have cemented their positions through rigorous compliance with aerospace standards. Arrow's portfolio, including aircraft-approved interior cleaners and exterior degreasers meeting AMS specifications, alongside a full aerospace and defence range, exemplifies the strategy of leveraging OEM approvals to secure long-term contracts. Similarly, Callington Haven Pty Ltd in Australia demonstrates the importance of global compliance frameworks. Their offerings, which span interior and exterior cleaners with explicit Boeing and Airbus compliance, highlight how adherence to original equipment manufacturer standards is a critical currency in this market.
DASIC International Ltd, also headquartered in the United Kingdom, focuses on specialized series like the Aerokleen range, targeting airframe and maintenance needs with specific gel and polishing products. This reflects a strategy of deep specialization within product lines. In the United States, Nuvite Chemical Compounds offers dry-wash systems and comprehensive care products for commercial carriers, FBOs, and MROs, indicating a strong alignment with operational efficiency and turnaround time reduction. Meanwhile, Rx Marine International from India represents the growing influence of emerging market suppliers, providing cost-competitive degreasers and cleaning chemicals for airlines and MROs. These companies collectively illustrate a market where competition is won not just on price, but on the ability to deliver certified, application-specific solutions that integrate seamlessly into maintenance workflows.
Regulatory Turbulence: The New Compliance Paradigm
The operating environment for aircraft cleaning chemicals is undergoing a seismic shift due to recent regulatory developments. In December 2025, the European Union Council formally approved the new Detergents and Surfactants Regulation (EU) 2026/405. While the council approval occurred in late 2025, the regulation itself was published on 2 March 2026, introducing a 3.5-year transition period for industry adaptation. This regulation simplifies compliance pathways for microbial and refill products, strengthens biodegradability standards, and introduces Digital Product Passport requirements. For manufacturers and suppliers, this means a fundamental change in how products are formulated, documented, and tracked throughout their lifecycle. The Digital Product Passport, in particular, demands a level of data transparency and supply chain visibility that will require significant investment in IT infrastructure and compliance management.
Simultaneously, a critical regulatory deadline looms on the global stage. Effective 22 January 2026, the approved uses for strontium chromate in the formulation of mixtures and aerospace maintenance applications are set to expire. This change, highlighted by Boeing Suppliers in January 2026, has profound implications for maintenance practices and chemical formulations that have historically relied on these compounds for corrosion inhibition. The industry must now pivot to alternative formulations that maintain performance standards without violating new restrictions. These regulatory dynamics are not static compliance hurdles; they are active market forces that are reshaping the competitive landscape by favoring suppliers who can rapidly innovate and adapt their portfolios to meet the new environmental and safety standards.
Strategic Value of the PW Consulting Analysis
Navigating this complex web of growth opportunities, competitive pressures, and regulatory shifts requires more than high-level summaries. The PW Consulting Aircraft Cleaning Chemicals Market research provides the granular intelligence necessary to make informed decisions in 2026. This report goes beyond the macro trends to deliver actionable insights on market sizing, segmentation dynamics, and competitive benchmarking. It offers a detailed examination of the supply chain, pricing structures, and the specific technical requirements that drive procurement decisions in civil, commercial, and military aviation sectors.
Decision-makers will gain access to a comprehensive view of how the 4.3% CAGR translates into specific regional and segment opportunities, allowing for targeted investment and resource allocation. The analysis dissects the competitive moves of key players, revealing the strategic implications of their product launches, OEM partnerships, and geographic expansions. Furthermore, the report provides a forward-looking assessment of how the EU Detergents and Surfactants Regulation and the strontium chromate expiration will impact formulation strategies, compliance costs, and market access over the forecast period. By integrating historical performance data from 2020-2025 with rigorous forecasts through 2032, this research equips organizations with the foresight needed to anticipate shifts in demand, mitigate regulatory risks, and identify emerging gaps in the market landscape.
For organizations seeking to optimize their position in the aircraft cleaning chemicals market, this research serves as an indispensable tool. It bridges the gap between abstract market data and operational reality, providing the depth of analysis required to validate strategic initiatives and uncover new avenues for growth. The full report contains the detailed segmentation data, regional breakdowns, and comprehensive company profiles necessary to execute a precise market strategy. We invite you to access the complete intelligence to ensure your organization is fully prepared to navigate the evolving skies of the aviation maintenance industry.
Aircraft Cleaning Chemicals Market
For detailed analysis of this topic, please visit the official page: Aircraft Cleaning Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


