



PW Consulting: Plastic Bag Market Hits $283M in 2025, Projected 3.5% CAGR Through 2032

Navigating the Plastic Bag Market in 2026: Strategic Imperatives for Sustainable Growth
The global plastic bag market stands at a critical inflection point. As regulatory frameworks tighten and consumer preferences evolve, industry stakeholders must reconcile structural demand with sustainability mandates. PW Consulting latest market research delivers a comprehensive, data-driven analysis of the plastic bag market from 2020 through 2032, providing executive teams with the strategic clarity required to navigate 2026 and beyond. This report is engineered not merely as a retrospective overview, but as a forward-looking decision architecture that maps growth trajectories, competitive pressures, and operational pivots across material innovation, regional expansion, and compliance readiness.
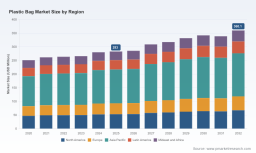
Our analysis draws on rigorous historical tracking and forward-looking modeling to establish a reliable baseline. The global market revenue reached approximately USD 283.00 million in 2025, reflecting a steady expansion from USD 251.00 million in 2020. Moving into the forecast window, the market is projected to cross USD 285.51 million in 2026 and accelerate toward USD 360.10 million by 2032, supported by a compound annual growth rate of 3.5 percent over the forecast period. These aggregate figures signal a market that remains fundamentally resilient, even as regulatory and environmental headwinds reshape traditional consumption patterns. The strategic question for leadership teams is no longer whether demand will persist, but how value will be reallocated across segments, geographies, and material classes.
Report Scope and Practical Utility
This study is structured to support cross-functional decision-making across strategy, procurement, product development, and regulatory affairs. Rather than offering static snapshots, the report embeds actionable frameworks that translate market intelligence into operational plans. The analysis spans the full value chain and is organized to help executives answer three core questions: where will volume and value concentrate, which stakeholder moves will redefine competitive positioning, and what compliance or material shifts must be priced into 2026 planning cycles.
Plastic Bag Market
Inside the report, readers will find:
- A longitudinal review of market performance from 2020 to 2025, establishing baseline momentum and structural change points.
- A detailed forecast model extending to 2032, with scenario sensitivities that account for regulatory acceleration, material substitution, and macroeconomic demand shifts.
- Deep-dive segmentation analysis across material types, application verticals, and regional markets, with emphasis on relative velocity rather than isolated snapshots.
- A competitive benchmarking module that maps incumbent positioning, product specialization, and strategic partnerships shaping near-term market dynamics.
- Regulatory tracking and compliance implications, including material mandates, recycling requirements, and single-use restrictions affecting retail, food service, and industrial channels.
- An operational playbook for navigating material transitions, supplier selection, and product portfolio adjustments in markets exposed to heightened policy scrutiny.
Every section is anchored in data but framed for action. The objective is to equip leadership teams with a defensible view of where competitive advantage will be won or lost, and which decisions made in 2026 will compound through the remainder of the decade.
Market Dynamics: Regulation, Recycling, and Regional Realignment
The 2026 landscape is being reshaped by a convergence of policy enforcement and circular-economy initiatives. In North America, California SB 1053 eliminates all single-use plastic carryout bags at retail beginning January 1, 2026, removing prior thickness-based exemptions and effectively closing loopholes that had allowed certain flexible formats to persist. The California Department of Resources Recycling and Recovery reinforced this shift with retail-facing bans on single-use carryout bags across most grocery and retail outlets, while New Jersey advanced its Plastic Ban Law prohibiting single-use carryout bags and polystyrene foam, accompanied by vendor lists for compliant reusable alternatives. In Asia, China continued executing its national single-use plastic control roadmap, phasing out non-degradable plastic bags and ultrathin variants across cities and markets through 2026. In Europe, the EU Packaging and Packaging Waste Regulation introduced mandates for fully recyclable packaging and minimum post-consumer recycled content for food packaging, intensifying pressure on flexible formats to meet design-for-recyclability standards.
These regulatory developments are not isolated compliance burdens; they are demand disruptors and portfolio stress tests. Retail and consumer-facing applications face the most immediate format transitions, while food and beverage channels must align packaging architecture with recyclability and recycled-content requirements. Industrial users, meanwhile, are evaluating how material specifications and procurement standards will adapt as downstream recycling infrastructure and feedstock availability evolve.
At the same time, practical recycling partnerships are gaining momentum as operational responses to film waste challenges. In March 2026, Scotts Miracle-Gro expanded its partnership with Trex to recycle plastic film waste from production operations into composite decking products. Shortly thereafter, in April 2026, Goodwill Industries of the Chesapeake repurposed millions of plastic bags collected at donation centers into composite decking through its collaboration with Trex Company. These initiatives illustrate a broader pattern: flexible film recovery is moving from pilot ideas to repeatable operational models, particularly where end-of-life pathways can be industrialized. For manufacturers and converters, such models create both opportunity and obligation, especially as brand owners and retailers seek verifiable circularity claims.
Geographically, the market continues to display uneven momentum. Asia Pacific remains a substantial demand center, supported by retail expansion, logistics growth, and broad-based packaging consumption. North America and Europe are defined less by raw volume expansion and more by format substitution, compliance-driven innovation, and consolidation around recyclable or reduced-waste solutions. Latin America and the Middle East and Africa present distinct growth vectors tied to retail modernization, import-driven supply chains, and localized packaging requirements. The report examines how these regional dynamics interact with material availability, conversion capacity, and competitive positioning, helping leaders prioritize where to invest, where to adapt, and where to defend share.
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The plastic bag market is characterized by a concentrated core of large-scale producers alongside a broad field of specialized manufacturers serving retail, foodservice, industrial, and custom packaging niches. Competitive advantage in 2026 will be determined not only by production capacity, but by portfolio flexibility, material expertise, compliance readiness, and the ability to align with downstream recycling and recovery ecosystems.
Among the leaders, Berry Global Group, Inc. maintains a global footprint in plastic packaging, with flexible plastic bags and films serving foodservice, grocery, and retail applications. Novolex Holdings, Inc. operates as a major North American producer of plastic shopping bags, foodservice bags, and specialty packaging, positioning itself across high-visibility retail and consumer channels. Amcor Plc brings globally integrated flexible packaging capabilities with relevance across food, beverage, and consumer products, while Sonoco Products Company contributes industrial and specialty plastics expertise through custom plastic bags and packaging solutions. ProAmpac LLC supports the market through flexible packaging production, including plastic shopping bags and liners via its Hymopac division, and TC Transcontinental Inc. adds scale in flexible packaging, including plastic bags and pouches.
In the specialty and regional segments, Bischof & Klein GmbH & Co. KG focuses on flexible plastic packaging and technical films for product protection, including bags and sacks, while RKW Group provides polyolefin film solutions and manufactures plastic sacks and bags, with active market engagement such as its presentation of comprehensive film solutions and plastic packaging at ProPak Asia 2026 in Bangkok. Reynolds Consumer Products Inc. remains prominent in consumer-facing formats through its Hefty brand plastic trash bags and consumer plastic bags. International Plastic Inc., Inteplast Group, Flair Flexible Packaging Corporation, and Universal Plastic Bag Manufacturing Co. provide a mix of retail shopping bags, poly bags, ziplock bags, custom flexible packaging, totes, and stock solutions, often serving customers that require rapid turnaround, customization, and broad SKU availability. AllState Plastics LLC extends into industrial, foodservice, and medical applications, broadening the use-case base beyond conventional retail formats.
The competitive field also includes players with growing relevance in sustainability-adjacent positioning. Dagöplast AS produces compostable, recycled, and green polyethylene bags, aligning product architecture with emerging environmental expectations. Thantawan Industry Plc. contributes Thai manufacturing capability in plastic bags and packaging products, reflecting the continued importance of Asia-based production and export dynamics. Together, these companies represent the breadth of the competitive landscape, from global integrators to regional specialists and sustainability-focused innovators.
Market concentration remains notable. The top three competitors account for approximately 62.0 percent of market revenue, while the top five represent around 75.0 percent. This concentration implies that scale advantages, distribution relationships, and portfolio breadth can exert persistent pressure on smaller or narrower players. At the same time, the presence of specialized manufacturers indicates that differentiation remains viable in custom formats, technical films, niche applications, and sustainability-oriented product lines. The report assesses how these competitive forces interact with regulatory shifts and material transitions, identifying which capabilities are likely to separate durable leaders from vulnerable incumbents.
Material and Application Considerations: Beyond Simple Volume Tracking
Material composition continues to shape the market structure. Polyethylene remains central to flexible bag manufacturing, supported by established conversion infrastructure and broad applicability across retail, food service, and industrial uses. Polypropylene contributes distinct performance characteristics and continues to hold meaningful share in applications where strength, clarity, or specific barrier attributes matter. Biodegradable formats occupy a strategically important but evolving position, influenced by regulatory expectations, consumer perception, composting infrastructure, and cost competitiveness. The report examines how these material streams interact with demand patterns, compliance pressure, and substitution risk, helping executives assess which formats warrant investment, which require contingency planning, and which may face mounting performance or policy constraints.
Application segmentation further clarifies where growth and disruption will be most pronounced. Retail and consumer channels remain a major demand base, but are also the most exposed to single-use restrictions and reusable alternatives. Food and beverage applications must navigate recyclability mandates and recycled-content requirements while preserving functional performance. Industrial applications offer a different risk-return profile, often with longer specification cycles and more customized requirements, but still subject to broader sustainability expectations and procurement standards. Rather than providing a fixed allocation snapshot, the report focuses on relative momentum, sensitivities, and the operational implications of shifting demand across these channels.
Plastic Cards Market
Why This Research Matters for 2026 Decision-Making
The plastic bag market is no longer a routine volume play. It is a sector in which regulatory timing, material innovation, recycling partnerships, and competitive concentration converge to redefine competitive positioning. Leaders who treat 2026 as a transitional year risk underinvesting in compliance readiness, misallocating product development resources, or missing the windows where regional and application-specific opportunities can be captured. Leaders who approach the market with a structured, evidence-based view can better align portfolios with durable demand, anticipate format substitution, and build supplier and customer relationships that survive policy and infrastructure changes.
This report is designed to support that level of decision-making. It integrates historical performance, forward forecasts, competitive benchmarking, and regulatory context into a coherent framework that can be translated into product planning, procurement strategy, market entry or expansion decisions, and risk mitigation. Most importantly, it identifies where the market is moving and what evidence-based actions will matter most in the next planning cycle.
For executives who need detailed segmentation trajectories, material-level growth differentials, regional demand dynamics, and company-specific competitive positioning, the full study provides the granular intelligence required to move from strategic direction to execution. The complete report, including detailed segmentation splits, competitive profiles, and forward-looking scenario analysis, is available through our official market research portal. We encourage leadership teams, strategy planners, and category decision-makers to access the full publication to align 2026 planning with the most current market evidence.
For detailed analysis of this topic, please visit the official page: Plastic Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


