



PW Consulting: Dunnage Air Bags Market to Hit $814.24M by 2032, 4.6% CAGR

The Strategic Pivot to Secure Logistics: Why the Dunnage Air Bags Market Defines Supply Chain Resilience in 2026
In an era where supply chain fragility is no longer a theoretical risk but a boardroom reality, the humble dunnage air bag has evolved from a commoditized accessory into a critical instrument of operational continuity. As logistics networks accelerate, modal shifts intensify, and regulatory frameworks tighten around cargo securement, enterprises must look beyond unit-price comparisons and grasp the structural forces reshaping this market. At PW Consulting, our latest foundational research on the Dunnage Air Bags Market is designed precisely for that mandate. Rather than offering a static snapshot, this study maps the competitive, regulatory, and material dynamics that will dictate procurement strategy, product specification, and market positioning through 2032.
The numbers already tell a story of steady, compounding expansion. From a base of roughly 594 million USD in 2025, the market is projected to cross the 622 million USD threshold in 2026 and steadily advance toward 814 million USD by the close of the decade. A five-year compound annual growth rate of 4.6 percent may appear disciplined at first glance, but when viewed against the backdrop of inflation, modal volatility, and sustainability mandates, it reflects an underlying demand trajectory that is both resilient and structurally reinforced. For executives accountable for freight optimization, loss prevention, and vendor consolidation, this is not a market to monitor passively. It is a market to architect into broader logistics strategy.
What the Report Delivers: An Operational Blueprint, Not Just a Statistical Overview
A market study earns its place on a strategist's desk only when it translates analysis into action. Our Dunnage Air Bags Market research is constructed around that principle. It begins with a rigorous historical reconstruction spanning 2020 through 2025, establishing the baseline behaviors of procurement cycles, regional demand migration, and material substitution. From that foundation, the forecast window extends through 2032, enabling scenario planning across moderate, accelerated, and constrained demand environments.
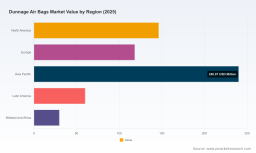
Beyond top-line sizing, the report dissects the segments that matter to procurement and product strategy: material architecture, application fields, and geographic distribution of demand. These breakdowns are framed not as isolated data silos but as interdependent variables. A shift toward higher-tensile synthetic constructions, for instance, does not occur in a vacuum; it intersects with carrier specifications, environmental exposure profiles, and total-cost-of-ownership calculations across truck, rail, and maritime transit.
The competitive architecture receives equal attention. The study profiles the enterprises actively shaping price, specification, and service expectations, examining how vertically integrated manufacturers, verification-driven specialists, and regional suppliers compete on different axes. Recent activity, including product introductions, standardization verifications, and performance certifications, is contextualized within broader industry momentum so that readers can distinguish temporary noise from durable competitive repositioning.
Crucially, the research is engineered for cross-functional use. Procurement teams gain clarity on specification trade-offs and supplier evaluation criteria. Operations leaders obtain a framework for aligning air bag selection with transit mode, load geometry, and turnover velocity. Strategy and corporate development professionals receive the structural map necessary to assess partnership opportunities, geographic entry logic, and category convergence trends. The objective is not to overwhelm with volume but to equip each function with the intelligence required to make defensible, forward-looking decisions.
Market Dynamics: Where Structural Forces Converge
Several forces are simultaneously compressing and reshaping the dunnage air bag landscape. At the material level, the industry is witnessing a gradual rebalancing between traditional paper-based constructions and synthetic alternatives. Poly-woven configurations, typically engineered from woven polypropylene fabric with laminated inner layers, have gained traction for their higher tensile strength and puncture resistance relative to kraft paper options. This is not merely a technical footnote; it is a procurement decision that reverberates across damage rates, handling durability, moisture exposure, and end-of-life considerations. Companies that treat material choice as a variable cost lever rather than a fixed specification are discovering that the right construction can lower downstream losses even when upfront pricing appears less favorable.
Regulatory and standardization pressure forms the second gravitational pull. In North American rail and intermodal environments, the Association of American Railroads continues to require that pneumatic dunnage products pass independent testing under its program, with verifications renewed on a three-year cycle. The current certification landscape, updated through late 2025, demonstrates that multiple polyethylene, polypropylene, and paper-based models remain active for rail car loading standards. For shippers and carriers, this cadence is not bureaucratic overhead; it is a signal of which products have survived rigorous, independent performance scrutiny. The implication for buyers is clear: verification status has become a proxy for risk management, and sourcing decisions increasingly hinge on whether a supplier's portfolio can demonstrate sustained compliance rather than one-time test success.
Airbag Market
Sustainability expectations now intersect with these technical and regulatory currents. Manufacturers are positioning recyclable constructions, reusable designs, and durable synthetic alternatives as answers to both performance and environmental criteria. The convergence is significant because it ties operational reliability to corporate reporting obligations. A dunnage solution that stabilizes cargo effectively while aligning with recyclable or reusable material goals can resolve two procurement pressures with one specification. Our research examines how these narratives are materializing across product lines and how buyers can evaluate them against verified performance rather than marketing language.
On the demand side, the tri-modal reality of road, rail, and maritime movement continues to shape application requirements. Trucking demands responsive void-filling and palletized freight stabilization at high throughput. Rail environments impose different load restraint and dimensional constraints, reinforced by formal verification expectations. Maritime and container transit add exposure variables that reward moisture-resistant and tear-resistant construction. Each pathway creates a distinct specification logic, and the most effective sourcing strategies are those that recognize these distinctions rather than forcing a single product architecture across incompatible operational contexts.
Competitive Landscape: Verification, Integration, and the Battle for Specification
The competitive field in this market is defined less by sheer scale than by differentiated capability. The leading participants compete on manufacturing integration, verification breadth, material specialization, and the ability to match product architecture to specific transit requirements. This is a landscape where trust is earned through testing, consistency, and service reliability, not through promotional claims.
Signode illustrates one distinct competitive posture. Headquartered in Chicago, the company has built its positioning around protective cargo securement systems that span kraft dunnage airbags, polywoven constructions, and broader airbag system offerings. Its emphasis on US assembly and recyclable kraft options, alongside moisture-resistant polywoven variants, signals a strategy that balances performance differentiation with regional manufacturing credibility. For buyers evaluating multi-modal securement portfolios, such breadth can simplify specification, but it also requires careful comparison of which product lines are optimized for which load conditions.
International Dunnage, based in Cleveland, exemplifies the vertically integrated, certification-centric model. Its ISO 9001-certified polywoven PP and paper dunnage bags are presented as AAR-verified across load application levels relevant to rail, truck, and container use. In a market where verification status increasingly functions as a procurement gate, this kind of documented compliance can become a decisive factor. Companies that can demonstrate repeatable manufacturing quality and multi-level verification are better positioned to serve shippers who must justify load securement choices to internal risk and compliance stakeholders.
AB Airbags has actively reinforced its standing through repeated verification activity. Its polyethylene and polypropylene dunnage bags, including TUFFY and S Series product lines, have moved through AAR verification cycles for rail-relevant applications, and its paper dunnage offerings have similarly appeared in verification records. For enterprises standardizing on rail car loading requirements, this cadence of re-verification is significant: it indicates sustained eligibility under the PPPPD program rather than a static, historical credential. The strategic takeaway is that competitive advantage here is maintained through operational discipline and recurring testing, not simply through initial market entry.
Halsted Bag's recent product activity reflects an intensifying focus on polypropylene inflatable dunnage as a durable, recyclable alternative to paper and vinyl for palletized freight stabilization. A new line launch in mid-2025 underscores how suppliers are pushing material narratives that address both performance and end-of-life considerations. For procurement teams, the practical question is whether such alternatives deliver measurable stabilization benefits under the specific load profiles, transit frequencies, and handling conditions they face.
The broader supplier ecosystem includes organizations such as Southern Packaging, Vestil Manufacturing, Ameson Pak, CargoTuff, Litco International, and US Cargo Control, each occupying slightly different positions across manufacturing, distribution, and application specialization. Southern Packaging emphasizes kraft and air dunnage options for truck, rail, container, and ocean transit. Vestil contributes inflatable bag series oriented toward rail, vessel, and intermodal shipments. Ameson Pak illustrates the expanding production capacity and PP woven focus emerging from Chinese manufacturing operations. CargoTuff and US Cargo Control address load securement and inflator ecosystem needs, while Litco International reinforces the presence of pneumatic dunnage verified under AAR standards.
What unites these players is a shared reality: the market remains relatively fragmented at the top. Concentration metrics indicate that the largest three firms account for roughly 20 percent of revenue, while the top five extend to about 28 percent. This dispersion means that buyers retain meaningful sourcing leverage, but it also means that supplier selection must be deliberate. In a fragmented landscape, the risk is not only overpaying for commoditized volume; it is also underestimating the operational consequences of choosing a product that lacks the verification, durability, or application fit required by a specific transit profile.
Why This Research Matters for 2026 Decision-Making
As organizations move through 2026, the decisions that matter most will be those that connect material selection, verification status, supplier reliability, and modal requirements into a unified sourcing logic. This is precisely where the PW Consulting study is intended to function: not as an isolated market read, but as a decision architecture. The report enables executives to answer several consequential questions.
First, it clarifies how demand is structurally distributed across material types, application settings, and geographic regions, allowing teams to test whether their current specification mix reflects real-world usage or legacy habit. Second, it frames recent competitive activity, including product launches and verification cycles, within a forward-looking context so that managers can separate transient marketing events from durable shifts in product readiness. Third, it maps the verification environment and standardization expectations that increasingly shape vendor qualification, enabling risk and compliance teams to align procurement criteria with documented performance rather than assumptions.
Just as importantly, the study provides the context needed to evaluate total value rather than sticker price. A lower-cost bag that underperforms in moisture exposure, puncture resistance, or repeatability can generate downstream losses that eclipse any initial savings. Conversely, a more robust construction or a supplier with stronger verification credentials may justify its position through reduced damage exposure, simplified compliance documentation, and improved consistency across load types. These are the trade-offs that separate reactive purchasing from strategic supply chain design.
For corporate development and market-entry planning, the research also delineates where competitive intensity is rising, where verification and material differentiation create barriers, and where regional demand patterns suggest opportunity or saturation. In a market expanding steadily but not explosively, the winners are rarely those who simply chase volume. They are the organizations that align product offerings, supplier relationships, and operational use cases with the specific contours of demand.
From Intelligence to Action
The dunnage air bag market is not defined by disruption in the sensational sense; it is defined by accumulation. Accumulation of cargo complexity, accumulation of regulatory expectations, accumulation of material science improvements, and accumulation of verification cycles that separate durable solutions from short-lived alternatives. In such an environment, the advantage belongs to enterprises that build procurement and logistics strategies on verified evidence rather than fragmented supplier claims.
Our attached research is intended to give your team that evidentiary foundation. It combines historical reconstruction, forward-looking sizing, segment-level analysis, competitive profiling, and regulatory context into a single operational reference. The complete breakdown, the detailed segment dynamics, the precise regional and application distributions, and the deep competitive assessments are reserved for the full report, because those are the layers where strategic precision is won or lost. If your 2026 decisions depend on cargo securement, supplier qualification, material specification, or market positioning, the source intelligence is where those choices become defensible.
Dunnage Air Bags Market
The trajectory is clear. The competitive field is active. The verification environment is tightening in practical, recurring ways. And the cost of specification mismatch is rising alongside the value of load stability. The organizations that recognize this now will not merely purchase dunnage air bags; they will integrate them into a deliberately engineered logistics posture. The full study exists to make that integration possible, and to ensure that your next sourcing and strategy decisions are built on the market as it is, not as it was.
For detailed analysis of this topic, please visit the official page: Dunnage Air Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


