



PW Consulting: Global Amino Acid Metabolism Disease Market to Reach $4.87B by 2032 with 7.2% CAGR

Navigating the Amino Acid Metabolism Disease Market: A Strategic Imperative for 2026 and Beyond
The landscape of rare metabolic disorders is undergoing a profound transformation. For pharmaceutical executives, investors, and healthcare strategists, the Worldwide Amino Acid Metabolism Disease Market represents a critical intersection of unmet medical need, evolving regulatory frameworks, and sustained commercial growth. As organizations calibrate their portfolios for the 2026 fiscal year and plan beyond, access to granular, forward-looking intelligence is no longer optional—it is a prerequisite for resilient decision-making.
Worldwide Amino Acid Based Formula Market
This article outlines the strategic rationale behind our newly released market research report and previews the analytical depth it offers. While we deliberately withhold precise segment-level figures and granular breakdowns to preserve the exclusive value of the full publication, we highlight the macroeconomic trajectory, competitive architecture, and regulatory currents that define this space today. Readers seeking comprehensive data tables, regional revenue mappings, and disease-specific forecasts are directed to the complete report.
Macro Trajectory: Sustained Expansion Anchored in Patient Demand and Pipeline Innovation
The global market for amino acid metabolism disease therapies has demonstrated consistent upward momentum over the past half-decade. Building on a baseline established in 2025, historical data from 2020 through 2025 reflects a compound annual growth pattern that underscores the resilience of this niche despite broader macroeconomic headwinds. The market has expanded steadily, crossing key inflection points as novel treatment modalities gained regulatory traction and clinical adoption accelerated across multiple geographies.
Worldwide Amino Acid Metabolism Disease Market
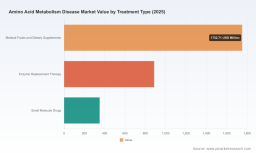
Looking ahead from 2026 through 2032, the trajectory remains firmly positive. Our base-case projections indicate a compound annual growth rate of 7.2 percent, translating market valuation from over three billion USD at the start of the forecast horizon to nearly five billion USD by the terminal year. This expansion is not merely a function of population growth or improved diagnostic yields; it is structurally reinforced by an expanding therapeutic arsenal, including enzyme replacement therapies, specialized medical foods, small-molecule interventions, and emerging gene-based approaches. The forecast period also captures the anticipated impact of patent expirations, pipeline milestones, and reimbursement policy adjustments that will collectively reshape competitive positioning.
For corporate planners, this growth curve demands more than passive observation. Strategic questions now center on resource allocation for clinical development, pricing architecture in an increasingly scrutinized rare disease space, and geographic prioritization as regional healthcare systems adopt divergent access pathways. Our report dissects these variables with scenario-based modeling, enabling decision-makers to stress-test assumptions against plausible regulatory and commercial outcomes.
Competitive Architecture: Established Leaders and Pipeline Disruptors
The competitive landscape is defined by a mix of specialized rare disease developers, large pharmaceutical entities leveraging acquisition-driven pipeline expansion, and innovative biotechnology firms advancing first-in-class modalities. Market concentration indicators reveal a moderately consolidated environment, where a handful of players command significant share, yet ample differentiation opportunities persist through novel mechanisms of action, improved delivery formats, and next-generation gene therapy candidates.
BioMarin Pharmaceutical Inc. continues to anchor therapeutic innovation for phenylketonuria and related urea cycle disorders, with landmark regulatory milestones reinforcing its commercial footprint. Most recently, the FDA expanded the label for Palynziq to permit self-administration, a development that enhances patient autonomy and may influence prescribing patterns across outpatient settings. Patent durability remains a critical strategic lever; composition-of-matter protections for Palynziq extend into the 2031 timeframe, delaying biosimilar entrants and preserving pricing power for originators during the forecast window.
Travere Therapeutics, Inc. has carved a focused niche in cystinuria management, offering Thiola and its extended-release formulation. Positive topline results from Phase 3 evaluations of sparsentan in rare kidney disease populations, including cystinuria-related indications, signal potential expansion of the company's clinical footprint and could reshape treatment algorithms if approved. These developments highlight how targeted clinical differentiation can translate into addressable market growth even within narrowly defined disease categories.
Chiesi Farmaceutici S.p.A. maintains a protected position in hereditary tyrosinemia type 1 through its Orfadin franchise. Recent regulatory approvals extending the oral suspension formulation to pediatric patients reinforce the product's role in early-intervention paradigms. Importantly, the supply chain for the active pharmaceutical ingredient relies on patented synthesis processes, with generic competition unlikely before 2030 in major markets. This structural barrier illustrates how manufacturing IP can function as a de facto market defense alongside therapeutic efficacy.
Recordati Rare Diseases contributes to the metabolic disorder ecosystem through carglumic acid for N-acetylglutamate synthase deficiency and related organic acidurias, while PTC Therapeutics advances sepiapterin for phenylketonuria, having initiated Phase 3 evaluations in 2024. The gene therapy frontier adds a new dimension to competitive dynamics: Takeda's advancement of AAV-based candidates for methylmalonic acidemia and arginase 1 deficiency, alongside AstraZeneca's continued development of LB-001 for MMA following its acquisition of LogicBio Therapeutics, signals a long-term shift toward potentially curative modalities. It is important to note, however, that gene therapies for MMA remain restricted to clinical trial use as of early 2026, with no commercial approvals yet granted—a constraint that shapes near-term commercialization expectations.
Together, these players illustrate a market where clinical differentiation, intellectual property durability, and strategic M&A shape competitive positioning. Our report maps each entity's pipeline status, recent regulatory milestones, and commercial implications, providing a structured lens through which to assess partnership opportunities, licensing threats, and market entry barriers.
Regulatory, Reimbursement, and Supply Chain Currents
Market outcomes in rare metabolic disorders are inseparable from policy and access dynamics. Regulatory designations continue to shape development incentives. For instance, orphan drug designation granted to DTX401 for methylmalonic acidemia confers seven years of market exclusivity upon approval, an incentive that materially alters the risk-reward calculus for developers pursuing first-in-class interventions. Such designations not only accelerate development pathways but also create competitive moats that early movers can leverage.
Reimbursement architecture exerts equal influence on commercial realization. In the United States, therapies such as Kuvan are covered under Medicaid subject to prior authorization and biochemical threshold criteria, illustrating how payer policies can gatekeep access even when clinical efficacy is established. These requirements underscore the necessity of health economics and outcomes research strategies that align with payer expectations, particularly as public and private payers intensify scrutiny over rare disease expenditures.
Supply chain considerations further complicate the strategic picture. For therapies dependent on proprietary synthesis routes, such as nitisinone-based treatments, the absence of generic alternatives until patent expiry in major markets provides temporary insulation from price erosion. However, organizations must monitor raw material sourcing, manufacturing scalability, and potential supply disruptions that could affect continuity of care and, by extension, market share stability.
These intersecting forces—regulatory exclusivity, payer conditionality, and manufacturing IP—form a triadic framework that our analysis explores in detail. Rather than treating each factor in isolation, the report evaluates their combined impact on pricing flexibility, market penetration timelines, and competitive entry windows.
Report Scope: What Decision-Makers Will Find Inside
The full Worldwide Amino Acid Metabolism Disease Market research publication is designed to function as an operational intelligence toolkit. Beyond the headline growth figures and compound annual projections, the report delivers a multi-dimensional dissection of the market architecture. The following elements are central to its analytical framework:
- Comprehensive historical valuation spanning 2020 through 2025, enabling retrospective performance analysis against macroeconomic and therapeutic adoption trends.
- Forward-looking forecasts extending to 2032, segmented to illuminate growth drivers across treatment modalities, disease categories, and geographic regions without exposing granular breakdowns in this preview.
- Detailed profiling of key market participants, including headquarters locations, therapeutic focus areas, recent regulatory events, and pipeline developments that inform competitive benchmarking.
- An examination of market concentration dynamics, highlighting how consolidated share distribution influences pricing behavior, partnership motivations, and barrier-to-entry assessments.
- Strategic context on regulatory designations, reimbursement mechanisms, patent timelines, and manufacturing supply considerations that collectively shape commercial viability.
- Scenario-oriented analysis that allows stakeholders to model the impact of pipeline approvals, exclusivity expirations, and policy shifts on revenue trajectories and market share redistribution.
Each section is structured to support actionable decision-making rather than passive reading. Whether the objective is portfolio optimization, geographic expansion planning, competitive threat assessment, or alliance evaluation, the report provides the evidentiary foundation needed to move from hypothesis to strategy.
Strategic Implications for 2026 Enterprise Planning
As organizations finalize their 2026 operating plans, several strategic imperatives emerge from the current market configuration. First, the growth trajectory supports continued investment in rare metabolic disease portfolios, but success will depend on disciplined capital allocation aligned with the most defensible therapeutic niches. The 7.2 percent compound annual growth rate offers a reliable baseline, yet the distribution of that growth across disease types, treatment categories, and regions is uneven and requires nuanced navigation.
Second, intellectual property strategy must be integrated with clinical development timelines. Patent expirations, orphan drug exclusivity windows, and manufacturing process protections do not operate on identical schedules. Companies that synchronize regulatory submissions, lifecycle management plans, and competitive monitoring will be better positioned to sustain revenue streams and mitigate erosion risks.
Third, payer engagement cannot be an afterthought. With reimbursement pathways increasingly conditional on biochemical thresholds, prior authorization protocols, and demonstrated outcomes, commercial teams must embed health economics evidence generation into early development stages. Proactive payer mapping and value proposition alignment will differentiate products that achieve rapid uptake from those that encounter access friction.
Fourth, the gene therapy horizon demands both optimism and realism. While AAV-based candidates for conditions such as methylmalonic acidemia represent a transformational prospect, commercial availability remains constrained to clinical trial settings through the forecast period. Strategic planners should account for this reality by modeling near-term revenue from established modalities while reserving capital and partnership flexibility for later-stage curative interventions.
Finally, competitive intelligence must be continuous rather than episodic. Recent regulatory approvals, clinical trial readouts, and M&A activity illustrate how quickly the landscape can shift. Organizations that institutionalize monitoring of pipeline milestones, exclusivity timelines, and supply chain developments will gain an information advantage that translates into faster, more confident strategic responses.
Conclusion: From Insight to Action
The Worldwide Amino Acid Metabolism Disease Market is defined by a confluence of unmet clinical need, innovative therapeutic development, and policy-driven access dynamics. Its growth is real, but its opportunities are unevenly distributed and contingent on regulatory, reimbursement, and competitive variables that require careful analysis. Our latest market research report provides the depth, granularity, and strategic framing necessary to convert macro trends into actionable enterprise decisions.
This preview has outlined the structural contours of the market, highlighted the competitive and regulatory forces shaping outcomes, and emphasized the strategic questions that demand rigorous answers in 2026. However, the full intelligence—complete with detailed segmentation data, regional revenue distributions, disease-specific valuations, treatment-type breakdowns, and comprehensive competitor benchmarking—resides exclusively in the complete publication. We invite stakeholders to access the full report to unlock the precise data and scenario analyses required to inform board-level strategy, investment committees, and commercial planning teams.
In a market where timing, exclusivity, and access architecture determine competitive advantage, comprehensive intelligence is the difference between reactive positioning and proactive leadership. Our research is designed to deliver that advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Amino Acid Metabolism Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


