



Global Student Microscopes Market to Hit $1.06B by 2032 at 5.1% CAGR Per PW Consulting

Strategic Clarity in a Growing Niche: Why the Worldwide Student Microscopes Market Demands Precision in 2026
The global student microscope sector is no longer a peripheral educational supply category. It has matured into a strategically significant hardware ecosystem shaped by curriculum modernization, laboratory digitization, and sustained institutional procurement cycles. For executives, distributors, and product strategists operating across education technology and scientific instrumentation, 2026 represents a decisive inflection point. Market momentum is visible in the numbers: the worldwide student microscopes market generated approximately 715.0 million USD in 2024, expanded to an estimated 751.5 million USD in 2025, and is projected to reach 789.83 million USD in 2026. Looking further ahead, the trajectory extends toward a 1.06 billion USD range by 2032, supported by a forecast Compound Annual Growth Rate of 5.1 percent across the 2026 to 2032 horizon. These figures signal steady, compounding expansion rather than sporadic spikes, but they also conceal structural complexity that only rigorous, data-backed analysis can untangle.
Surgical Microscopes Market
This introduction previews the strategic architecture of our latest research release, Worldwide Student Microscopes Market, and outlines why decision-makers should treat this study as an operational compass rather than a static reference document. The report is engineered to convert macro momentum into actionable strategy: mapping revenue trajectories, dissecting competitive positioning, decoding procurement behavior across purchasing environments, and isolating the operational variables that will determine margin resilience and product-market fit in the next planning cycle.
The Growth Narrative: Translating Aggregate Momentum into Strategic Direction
The expansion reflected in the 2026 to 2032 forecast is anchored in durable demand drivers rather than temporary stimulus. Educational institutions continue to refresh aging laboratory equipment, while home-based learning ecosystems and hobbyist communities have normalized microscopy as a hands-on exploratory tool. That dual engine—formal education and informal learning—creates a resilient demand base that buffers the market against single-sector fluctuations. Yet the headline CAGR only tells part of the story. The real strategic question for 2026 is not whether the market is growing, but where growth is concentrating, which product architectures are capturing share, and how procurement cycles are shifting across different purchasing environments.
Our report treats these macro projections as a starting framework and then decomposes them into commercially relevant pathways. Readers will find forward-looking evaluations that connect the 2026 baseline to the 2032 endpoint with intermediate checkpoints that expose inflection years, demand elasticity, and the pace at which product categories transition from introductory price competition to value-driven differentiation. This structure matters because student microscope purchasing is rarely impulsive. It is influenced by budget approvals, curriculum alignment, durability expectations, and, increasingly, digital connectivity requirements. A market growing at a 5.1 percent CAGR can still produce sharp divergence between winners and laggards if product roadmaps fail to match procurement realities.
Strategic reading of the forecast period also requires understanding that growth is not uniformly distributed across purchasing contexts or product architectures. The study maps how volume, price sensitivity, and feature expectations interact across environments where institutional specifications dominate versus settings where portability, power independence, and consumer-friendly interfaces matter more. The objective is to equip strategy teams with the segmentation logic required to allocate marketing resources, set pricing architecture, and prioritize development roadmaps without relying on assumptions that blur the line between institutional and non-institutional demand.
Inside the Report: Operational Intelligence Designed for Execution
A market study earns its place on a strategy team’s shelf when it converts information into execution clarity. The Worldwide Student Microscopes Market report is structured around segments that mirror how companies actually make decisions. It does not stop at sizing; it builds a working view of the commercial terrain across regions, product types, and purchasing environments so that teams can evaluate where to enter, where to defend, and where to reposition.
Regional Commercial Architecture
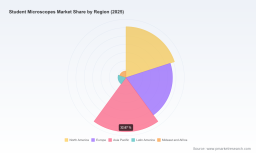
The report examines the geographic footprint of demand with a focus on the operational characteristics that shape market access. Rather than presenting regions as isolated statistics, it contextualizes how procurement sociology, distribution maturity, and compliance expectations differ across major markets. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct pathways for market entry and share capture. The analysis connects regional dynamics to practical variables such as channel structure, institutional buying cadence, certification requirements, and the cost economics of serving each geography. This regional lens helps executives judge whether a strategy should emphasize direct institutional sales, distributor partnerships, or hybrid models tailored to local purchasing norms.
Product-Type Segmentation and Commercial Positioning
Product architecture is a central axis of competition in student microscopy. The report breaks down the market along the categories that matter most to portfolio planning, including compound microscopes, stereo microscopes, and digital and USB-enabled models. Each type reflects different use cases, price expectations, and competitive pressures. Compound systems continue to anchor core educational demand, while stereo instruments serve applications where depth perception and three-dimensional observation are essential. Digital and USB-connected variants are reshaping purchase considerations by introducing imaging, data capture, and connectivity as differentiating factors.
The study evaluates how these categories interact with one another in real purchasing decisions. It clarifies where substitution risk is rising, where complementarity creates bundling opportunities, and where product definitions are blurring as manufacturers add illumination upgrades, magnification range flexibility, and imaging integration to traditional designs. For product leaders, this segmentation framework supports decisions about SKUs to expand, features to prioritize, and price tiers to defend or disrupt.
Application Environments and Buying Behavior
Student microscope demand is shaped by where the equipment is used and who approves the purchase. The report dissects the principal application environments, including K-12 schooling, colleges and universities, and home or hobbyist settings. These environments differ not only in volume potential but also in buying criteria. K-12 procurement typically emphasizes durability, safety, ease of use, and alignment with standardized classroom workflows. Higher education environments often place greater weight on optical performance, modular flexibility, and compatibility with laboratory teaching needs. Home and hobbyist purchasing tends to be more influenced by portability, intuitive operation, and consumer-visible features.
By separating these application contexts, the report helps teams anticipate how messaging, channel strategy, and product configuration should vary. A feature set that strengthens institutional approval may not be the same set that drives consumer conversion. The study exposes these differences so that go-to-market plans can be calibrated instead of generalized.
Competitive Landscape: Positioning, Pressure, and Product Signaling
The student microscope arena is contested by a diverse set of manufacturers, ranging from specialized education-focused suppliers to broader optical and scientific instrumentation names. Competitiveness in this market is not defined solely by scale. It is increasingly determined by product availability, update cadence, illumination quality, magnification range, digital integration, and the ability to meet region-specific compliance and classroom durability expectations. Our report maps the competitive field through the lens of companies whose product cadence and market presence actively shape procurement conversations.
Companies Shaping the Current Battleground
Several firms stand out for the way they combine product breadth with targeted positioning across student-grade categories. AmScope has built a recognizable presence in student compound and stereo microscopes for K-12 and home education, with models such as the M150 series emphasizing LED illumination and magnification ranges suitable for introductory to intermediate learning. OMAX Microscopes focuses on affordable student instruments, including digital and trinocular designs for biology lab environments, with offerings like the 40X-2500X LED compound series. Celestron continues to address entry-level educational use through lines such as the Labs series, which provide accessible magnification for school and lab settings. Swift Microscopes positions durability as a core value proposition, with classroom-oriented compound designs such as the M3600 series engineered for repeated instructional use.
In parallel, National Optical and Scientific Instruments supplies beginner-oriented models such as the 210 series with achromatic objectives for educational applications. Meiji Techno contributes entry-level student instruments including the ML1500 series for biology education with practical magnification coverage. Euromex supports school-focused deployments through student-grade lines like the BioBlue series, incorporating LED lighting and standard magnification ranges. Motic extends the competitive conversation with digital student microscopes such as the BA210 series, integrating imaging options relevant to modern classroom workflows. On the premium side of the student segment, Leica Microsystems offers educational instruments like the DM300 series with modular LED illumination, while Olympus, now operating under Evident Scientific, maintains entry-level relevance through models such as the CX23, which combine ergonomic design with a familiar magnification envelope.
This competitive set matters because it illustrates two simultaneous dynamics: congestion at the accessible price tier and differentiation at the feature and brand-trust level. Companies are not only competing on unit price; they are competing on update timing, illumination performance, magnification flexibility, digital readiness, and the perceived durability of instruments in high-traffic learning environments.
Recent Moves That Signal Strategic Direction
Product releases and channel events from recent months provide early indicators of where firms are placing their bets. In October 2024, AmScope introduced an updated M150C-I student compound microscope with improved LED illumination tailored for K-12 education. In September 2024, Swift Microscopes showcased the new M3602C student microscope series at the ISTEL 2024 education technology conference, signaling a focus on the intersection of classroom hardware and education technology ecosystems. In June 2024, OMAX released a 2024 catalog featuring enhanced 40X-2500X digital student microscopes with WiFi connectivity, reflecting the rising importance of digital integration in student instruments. In March 2024, Celestron updated the Labs S20 student microscope with cordless battery operation to support portable classroom use. Together, these developments illustrate a market in which illumination quality, portability, digital linkage, and education-channel visibility are becoming central competitive levers.
Market Dynamics: The Forces That Will Shape 2026 Outcomes
Beyond product specs and competitor moves, student microscope strategy must account for the structural forces that influence cost, compliance, and market access. The report integrates these dynamics into the commercial analysis so that teams can anticipate friction points before they affect margins or launch timing.
Regulatory and Certification Considerations
Educational optics do not operate in a vacuum. Student microscopes must comply with ISO 10993 for the biocompatibility of optical components in educational settings, reflecting the importance of material safety when instruments are used repeatedly by students. In European markets, CE marking is required for student microscopes sold into educational channels to ensure electrical safety. These requirements are not peripheral administrative details; they shape product design, supplier selection, documentation burdens, and time-to-market. The report contextualizes compliance as a commercial variable, showing how regulatory expectations influence both regional availability and competitive readiness.
Cost Structure and Production Economics
Margin strategy in student microscopes is closely tied to input economics. Glass lens blanks for student instruments typically cost between 5 and 15 USD per unit because of borosilicate material requirements, while assembly labor in China averages around 2 to 4 USD per unit in high-volume production. These baseline costs establish the floor beneath which price competition becomes destructive and above which differentiation becomes essential. The study uses this economic context to frame discussions of scaling, outsourcing, sourcing strategy, and the point at which feature upgrades justify higher unit pricing without losing price-sensitive buyers.
Concentration, Channel Power, and Strategic Implications
The market’s concentration profile is an important indicator of how aggressively new entrants can compete and how much leverage established players hold. The report evaluates market concentration using CR3 and CR5 measures, which provide insight into how much share is held by the leading suppliers and how fragmented the remainder of the field remains. For strategy teams, this concentration data helps answer practical questions about pricing resilience, distributor leverage, brand substitution risk, and the realistic pathways for gaining visibility in a crowded supply environment. A market with meaningful but not absolute concentration invites competition, but it also rewards companies that can distinguish themselves through product reliability, channel execution, and application-specific value propositions.
Worldwide Student Microscopes Market
Why 2026 Is a Decision Point, Not Just Another Forecast Year
The strategic value of this study lies in its ability to connect forward-looking sizing with the operational realities that determine whether growth can be captured. The worldwide student microscopes market is expanding from an estimated 789.83 million USD in 2026 toward a 1.06 billion USD range by 2032, with a forecast CAGR of 5.1 percent. That trajectory creates opportunity, but only for organizations that understand how demand is distributed across regions, product types, and application environments, and how competitive and regulatory forces shape execution risk. Broad market optimism is not enough. Companies need to know which segments offer defensible margin, which product categories are most vulnerable to commoditization, which geographies demand channel adaptability, and which product updates are likely to shift procurement preference in the next planning cycle.
This report is designed to answer those questions with the level of specificity that strategy teams require. It combines market sizing, segmentation logic, competitive mapping, recent product and channel developments, and structural cost and compliance dynamics into a single decision-oriented framework. For executives planning product roadmaps, pricing architecture, channel expansion, or competitive response, the study provides the intelligence needed to move from general market awareness to targeted commercial action.
What the Full Study Enables
The complete Worldwide Student Microscopes Market report extends well beyond the overview presented here. It provides a comprehensive, data-supported examination of how the market is structured today and how it is expected to evolve through 2032. Readers will gain access to detailed segmentation analysis across regions, product types, and application environments; a competitive landscape assessment centered on the companies actively shaping student microscope procurement; recent product and channel developments that reveal where innovation is being prioritized; and an integrated view of regulatory, cost, and certification dynamics that influence both product design and market access.
Most importantly, the study is built to support real strategic choices: where to invest, where to differentiate, where to consolidate, and where to reposition. In a market growing at a steady but nuanced pace, intelligence of this kind is not optional. It is the foundation for disciplined expansion and competitive resilience.
To explore the full segmentation detail, competitive analysis, regional dynamics, and forward forecast supporting the 2026 to 2032 outlook, access the complete Worldwide Student Microscopes Market research. The full report provides the depth required to translate market momentum into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Student Microscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


