



PW Consulting: Global Agricultural Nanotechnology Revenue to Reach $816M by 2032 on 14.03% CAGR

Navigating the Nano-Agriculture Revolution: Strategic Insights for the 2026–2032 Corporate Horizon
As agricultural systems confront intensifying climate volatility, constrained arable land, and mounting pressure for sustainable input utilization, nanotechnology has emerged as a transformative lever for precision crop management. The global market for agricultural nanotechnology is no longer a speculative research frontier. It has entered a phase of measurable commercial acceleration, driven by yield optimization mandates, regulatory tightening around conventional agrochemicals, and the operational need for targeted delivery mechanisms. For executives mapping capital allocation, product roadmaps, and competitive positioning through 2032, timely access to structured market intelligence is decisive. This strategic overview introduces our latest Worldwide Agricultural Nanotechnology Market research, designed to convert macroeconomic trajectories into actionable corporate strategy.
Market Trajectory & The Strategic Imperative for 2026 Decision-Making
The commercial expansion of agricultural nanotechnology over the past half-decade reflects a shift from laboratory validation to field-level deployment. Between 2020 and 2025, the global market scaled from approximately USD 165.4 million to an estimated USD 325.5 million, establishing a robust baseline for forward-looking planning. Looking ahead, our baseline projections indicate the market will reach roughly USD 370.9 million in 2026 and continue its upward trajectory, ultimately approaching USD 816 million by 2032. This expansion corresponds to a compound annual growth rate of approximately 14 percent across the forecast window, underscoring an environment where early positioning, scalable distribution, and formulation differentiation can compound competitive advantage.
For senior leadership, this trajectory carries several strategic implications. First, the pace of adoption is widening beyond early-adopter markets, meaning procurement cycles, regulatory clearances, and agronomic validation protocols are becoming standardized rather than experimental. Second, capital allocation toward nano-enabled inputs must be evaluated against total cost-of-ownership rather than upfront price differentials, as efficiency gains, reduced application volumes, and extended field performance increasingly reshape return profiles. Third, the convergence of digital agriculture and nanomaterials is accelerating, meaning companies that integrate sensor-driven monitoring, precision application platforms, and nano-formulation portfolio strategy will capture disproportionate value relative to siloed competitors. The 2026 planning cycle represents a critical inflection point: organizations must determine whether to build, partner, acquire, or follow as the market matures. Our report provides the analytical scaffolding to make those choices with empirical confidence rather than directional intuition.
Inside the Report: Operational Intelligence for Commercial & R&D Leadership
The Worldwide Agricultural Nanotechnology Market report is structured to serve strategy teams, commercial directors, and R&D planners who require granular visibility into market architecture without sacrificing readability. Rather than presenting isolated data tables, the analysis weaves macroeconomic trends, segmentation dynamics, competitive behavior, and operational constraints into a decision-ready framework. Key components include:
- Historical Benchmarking & Forecast Modeling: A multi-year reconstruction of market evolution from 2020 through 2025, paired with a ten-year forecast spanning 2026 to 2032. The modeling isolates growth drivers, demand elasticity among input categories, and sensitivity factors that may alter trajectory under differing regulatory or supply-chain scenarios.
- Segment Structure & Commercial Pillars: The analysis disaggregates the market by material architecture, covering nanoparticles, nanocapsules, nanofibers, and other nanomaterials, alongside application pathways such as nano-fertilizers, nano-pesticides, nano-biosensors, and soil amendment solutions. Each segment is examined for adoption readiness, formulation economics, and practical deployment conditions rather than theoretical potential.
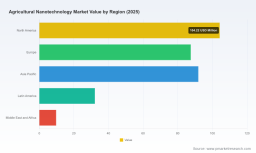
- Regional Demand Geography: Demand patterns are mapped across major economic blocs, illuminating where commercialization momentum is strongest, where agronomic validation pipelines are maturing, and where regulatory or infrastructural considerations shape speed-to-market.
- Competitive Landscape & Firm-Level Profiles: Detailed evaluations of leading participants, including strategic positioning, product architectures, geographic reach, and recent activity shaping the commercial agenda.
- Regulatory, Supply-Chain & Risk Context: An assessment of environmental safety discussions, nanoparticle toxicity considerations, input production economics, and the emerging use of agricultural waste biomass as a renewable feedstock for nano-formulation manufacturing.
- Integration Pathways with Precision Agriculture: Examination of how nano-enabled monitoring, real-time soil and crop sensing, and digital platform ecosystems are beginning to align, supporting optimized resource utilization and more sustainable field practices.
Each analytical module is designed to feed directly into pricing strategy, partnership evaluation, portfolio sequencing, and scenario planning. Executives gain visibility into where value is being created, which adoption barriers remain material, and how incumbents and emergent players are adapting their operating models. To ensure strategic teams have complete access to cross-tabulations, scenario assumptions, and detailed firm-level comparisons, the full dataset and extended commentary are reserved for the complete report accessible through our official market research hub.
Competitive Architecture: Navigating Scale, Specialization & Regional Momentum
The competitive field in agricultural nanotechnology is defined by a blend of specialized innovators, crop-science incumbents, and regional formulation leaders expanding their nano-enabled portfolios. Market concentration remains moderately distributed, with the top three players accounting for roughly 31 percent of revenue and the top five approaching 43 percent. This structure signals a market that is large enough to support multiple differentiated strategies, yet concentrated enough that early formulation leadership, distribution leverage, and partnership networks can materially influence share dynamics.
BASF SE has continued to intensify investment in nano-enabled crop protection and fertilizer solutions, with recent activity emphasizing targeted pesticide delivery architectures designed to reduce environmental load while preserving field efficacy. In February 2026, Syngenta AG expanded its precision agriculture portfolio by integrating nano-formulations for enhanced seed treatment and crop protection performance, reinforcing a strategic direction that ties advanced delivery systems to broader agronomic platforms. On the specialized side, Aqua-Yield Operations, LLC operates its Nano-Yield line with a focus on nano-fertilizer and nutrient delivery systems engineered for improved uptake efficiency and lower application rates, a positioning recognized in 2025 by inclusion on the Inc. 5000 list of America's fastest-growing private companies.
Several firms are strengthening the nano-input ecosystem across multiple geographies. Indogulf BioAg LLC advances nano-fertilizer offerings including Nano Urea and NPK and micronutrient mixes tailored for precision nutrient delivery. Migrow Agro Products and Annadata Organic are developing nano-based and nano-enhanced agricultural inputs, while Coromandel International Limited is expanding nano-fertilizer development and distribution within its broader crop protection and nutrient portfolio. Research-oriented organizations such as Ray Nano Science & Research Center and Zyvex Labs continue to explore molecular-scale solutions with implications for precision agriculture and crop enhancement. Nanoco Group Plc and Nanoshel LLC contribute additional nanomaterial supply and application development capacity relevant to agricultural productivity and resilience. SGS has also highlighted the practical promise of nanomaterials such as iron oxide nanoparticles for improving nutrient delivery and pest control in field trials and biostimulant formulations, reflecting an industry-wide interest in evidence-based application development.
The strategic takeaway for corporate planners is that competition is fragmenting by capability rather than consolidating around a single application model. Some organizations are optimizing for delivery precision and environmental performance, others for cost-efficient nutrient systems, and others for sensor-integrated monitoring. Companies evaluating market entry, partnership options, or acquisition targets must assess not only product performance claims but also formulation scalability, regulatory navigation, and the ability to embed nano-enabled products within existing agronomic service models. The report provides firm-level context and comparative lenses to support those evaluations.
Forces Shaping Adoption: Regulation, Economics & Sustainable Feedstock Innovation
Commercial momentum in agricultural nanotechnology is being shaped by interlinked technical, economic, and regulatory dynamics. One of the most consequential developments is the exploration of agricultural waste biomass as a renewable, low-cost feedstock for producing nano-fertilizers and related inputs. This pathway offers dual advantages: it lowers raw-material exposure for manufacturers while also reducing agricultural waste and associated greenhouse-gas emissions. As sustainability reporting becomes more central to procurement decisions and investor expectations, input suppliers that credential their formulations through circular feedstock strategies may gain meaningful competitive differentiation.
Worldwide Agricultural Nanotechnology Market
At the same time, adoption is tempered by practical considerations. Nano-fertilizers and nano-pesticides typically carry higher initial production costs relative to conventional formulations, even as they promise long-term efficiency gains, reduced application rates, and lower environmental footprint. Commercial success increasingly depends on whether suppliers can translate formulation advantages into measurable field outcomes and whether buyers can justify upfront cost premiums within their operating economics. That calculation is being reshaped by integration with precision agriculture and digital platforms, where nano-enabled sensors and monitoring assets support real-time soil and crop observation. This convergence supports more efficient resource deployment and aligns with broader sustainability objectives, but it also raises the bar for interoperability, data management, and service integration.
Regulatory and environmental scrutiny remains a defining strategic variable. Ongoing discussions center on nanoparticle behavior, potential toxicity considerations, impacts on soil ecosystems, and the need for proportionate regulatory frameworks that enable safe, scaled deployment of nano-agrochemicals. Organizations operating in this market must therefore treat compliance architecture, environmental stewardship, and field-testing rigor as core competitive capabilities rather than peripheral obligations. Recent expert commentary continues to emphasize both the promise of next-generation biostimulant formulations and the importance of disciplined safety evaluation. Companies that proactively align product development with transparent safety evidence, responsible application guidance, and credible environmental performance can reduce adoption friction while strengthening brand and partnership positioning.
Agricultural Films Market
Why the Full Intelligence Set Matters for 2026 Strategy
Strategic planning in a market moving at this pace requires more than directional awareness. Executives need scenario-ready estimates, segment-level adoption nuance, competitive benchmarking, and insight into the operational constraints that will determine whether nano-enabled products scale or stall. The complete research offering extends beyond this overview by providing detailed segment breakdowns, comparative assessments, and context designed to support pricing models, partnership selection, R&D prioritization, and market-entry decisions. It also maps the practical implications of feedstock innovation, regulatory evolution, and digital integration, enabling leadership teams to build strategies grounded in evidence rather than aggregated headlines.
Organizations that secure this level of visibility can calibrate investment with greater precision, identify where differentiation is still attainable, and anticipate competitive moves before they reshape accessible market space. For teams preparing 2026 budgets, product roadmaps, and capability builds, the difference between informed action and reactive positioning is access to a comprehensive, analytically rigorous market study. The Worldwide Agricultural Nanotechnology Market report is intended to deliver exactly that foundation.
Accessing the Full Market Intelligence
To explore the complete segmentation, firm-level evaluations, forecast assumptions, and scenario-based analysis supporting this outlook, please access our official Worldwide Agricultural Nanotechnology Market research portal. The full report provides the depth, cross-references, and structured data layers necessary to translate these trends into concrete corporate strategy and operational execution.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Nanotechnology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


