



PW Consulting: LAG3 Antibody Market Hits $1.32B in 2025, Forecasted to Reach $6.95B by 2032

Strategic Intelligence for the LAG3 Antibody Market: Navigating Growth and Competitive Complexity in 2026
The global oncology immunotherapy landscape is entering a decisive inflection point. As checkpoint inhibition matures beyond PD-1/PD-L1 dominance, Lymphocyte Activating 3 (LAG3) has emerged as a validated yet highly contested therapeutic axis. Our latest Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market study is designed to equip executives, portfolio leaders, and investment teams with the structured intelligence required to navigate this rapid expansion. The report is not a retrospective snapshot. It is a forward-looking decision framework calibrated for commercial planning, partnership strategy, and risk allocation throughout the 2026–2032 forecast horizon.
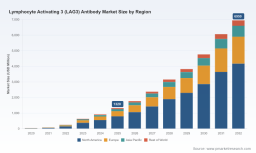
The market has already demonstrated extraordinary trajectory. From USD 45.2 million in 2020, global LAG3 antibody revenue expanded to USD 1,320.0 million by 2025. The forecast pathway signals continued acceleration, sequencing from approximately USD 1,770.15 million in 2026 toward USD 6,950.0 million by 2032, underpinned by a projected compound annual growth rate of 26.79 percent . Such magnitude reflects more than clinical momentum. It indicates a structural reordering of combination immunotherapy economics, manufacturing prioritization, and late-stage development alignment. The strategic question for 2026 is no longer whether LAG3 will scale. It is how organizations will position themselves to capture value amid concentrated supply chains, divergent clinical readouts, and intensifying bispecific competition.
Why 2026 Executive Planning Requires Dedicated LAG3 Market Intelligence
Checkpoint inhibitor markets are routinely misunderstood when analyzed through blunt historical totals. LAG3 is a case in point. Early revenue surges were propelled by the first approved LAG-3 blocking combination, but the subsequent commercial lifecycle depends on label evolution, resistance patterns, combination sequencing, and the arrival of next-generation molecular formats. Executives overseeing oncology portfolios, biopharma R&D pipelines, or specialized investor funds require granular visibility into how these variables interact, rather than high-level total addressable market approximations that obscure execution risk.
Our research framework was constructed for exactly this moment. The study maps the gap between early commercial adoption and the broader opportunity set that will define the remainder of the decade. It connects macro growth signals with the tactical inputs that shape 2026 budgeting, resource allocation, and partnership diligence. Readers who rely solely on headline figures risk underestimating the operational complexity involved in securing share within a space where approved products, clinical-stage assets, and bispecific programs compete for the same patient populations and payer attention.
Market Trajectory and the Structural Meaning of the Forecast Curve
The progression from 2020 through 2025 illustrates how quickly a targeted immune pathway can convert from scientific hypothesis to commercial reality. Growth was not linear. It accelerated sharply as regulatory milestones, combination clinical data, and commercial launch infrastructure aligned. The forecast period continues this expansion, but the curve also encodes critical strategic nuance. Sustained double-digit momentum implies that revenue creation will increasingly shift from first-mover advantage into differentiation by indication breadth, dosing convenience, safety profile, and biosimilar or competitive entry timing.
For strategy teams, the most valuable insight is not the absolute size of the opportunity. It is the pace at which competitive tiers are forming. Monoclonal LAG3 programs and bispecific constructs are not expanding in isolation. They are reshaping each other’s development priorities and commercial endpoints. Organizations that treat the forecast as a single growth number will miss the operational implications: manufacturing bandwidth planning, clinical trial positioning, and the timing of commercialization readiness across multiple therapeutic formats.
Competitive Architecture: Incumbents, Challengers, and Format Differentiation
The LAG3 field is defined by a small set of strategically positioned players operating across distinct development philosophies. Competitive advantage will be determined not only by molecule design, but by regulatory timing, combination strategy, and the ability to translate clinical data into durable commercial positioning.
The approved-commercial anchor remains centered on Bristol Myers Squibb, whose relatlimab-based fixed-dose combination established the first regulatory precedent in the category. That landmark positioned LAG3 alongside PD-1 blockade in melanoma care, yet it also raised broader questions about durability of benefit across treatment contexts. Recent clinical outcomes, including early-stage signals in the adjuvant setting, highlight the reality that commercial leadership in immunotherapy is continuously re-tested by new endpoints and new patient populations.
Parallel to commercialization, a second tier of developers is advancing late-stage and differentiated programs. Regeneron Pharmaceuticals, with its fianlimab program and alliance structure including Sanofi, represents one of the most closely watched monoclonal LAG3 efforts in advanced solid tumors. Immutep has pursued a conceptually distinct route through soluble LAG-3 fusion protein approaches and agonist-oriented assets, signaling that the category’s biology is being explored beyond conventional blocking antibodies. Merck Sharp & Dohme, Novartis, Incyte Corporation, and others maintain programs that continue to probe LAG3 across varied combination settings and indications.
A further competitive layer is emerging through bispecific engineering. Companies such as MacroGenics, Roche, Xencor, and F-star Therapeutics have been developing PD-1 x LAG-3 or PD-L1 x LAG-3 constructs designed to compress dual checkpoint modulation into streamlined dosing and potential mechanistic advantages. This format race matters because bispecifics can alter the economics of combination therapy, affecting everything from clinical development cost to market segmentation logic.
Market structure analysis within the report also emphasizes concentration dynamics as a strategic variable. In categories with high concentration, partnership access, supply positioning, and early label strategy can outweigh incremental efficacy gains. Executives evaluating entry, licensing, or co-commercialization must understand how dominance is being constructed, not simply which firms appear in the leaderboard.
Therapeutic Indications and the Commercial Logic of Application Breadth
Melanoma remains the foundational application for LAG3-based immunotherapy, but long-term market expansion will depend on broadening the clinical narrative. Non-small cell lung cancer and colorectal cancer represent high-value application pathways where LAG3 modulation may address unmet needs in combination or sequencing strategies. Beyond these core solid tumor domains, additional oncology settings are under active exploration, and their eventual contribution will shape the portfolio value of LAG3 assets over the forecast horizon.
This application diversity carries strategic implications. Indication expansion is rarely a pure scientific story. It involves trial design efficiency, regulatory pathway selection, payer evidence requirements, and the ability to position a product within existing standards of care. A market research asset that isolates total revenue without mapping the application architecture risks obscuring where growth will actually be earned. Our analysis approaches the application landscape as a commercial allocation puzzle, connecting clinical priority with launch sequencing and competitive overlap.
Bispecific Antibodies, Manufacturing Realities, and Strategic Format Choice
The shift toward bispecific architectures is one of the most consequential strategic developments in the category. Bispecifics offer the promise of simplified administration, enhanced target engagement logic, and potentially differentiated safety or efficacy profiles. But they also impose distinct development and manufacturing constraints, including molecular complexity, process optimization, and scale-up economics. In a category expanding at a rapid CAGR, the winners may not only be those with the strongest monotherapy data, but those with the most executable format strategy relative to their capital structure and partnership capabilities.
For strategic planners, format selection is effectively a multi-year operational commitment. Decisions made in 2026 regarding combination design, clinical positioning, and supply readiness will influence commercial viability well into the late 2020s. The research therefore evaluates format-related implications not as scientific commentary, but as a set of business-design choices with measurable risk trade-offs.
Regulatory Milestones and Reimbursement Landscape: What Has Been Set in Motion
Regulatory approval created the first commercial proof point for LAG3 blockade, establishing a regulatory precedent that has rippled across development planning. The initial FDA approval in 2022 and subsequent European Commission authorization in 2022 for the fixed-dose combination in advanced melanoma helped define a regulatory template for LAG3-containing regimens. These milestones did more than open a market. They established evidence expectations, label framing, and combination positioning that continue to influence trial strategy and commercial planning.
Worldwide Indoleamine 2,3 Dioxygenase 1 (IDO1) Antibody Market
Reimbursement dynamics have followed conventional oncology checkpoint inhibitor patterns in major markets, with pricing and access decisions shaped by existing immuno-oncology policies rather than by unique category-specific constraints. From an operational perspective, this means that commercial execution hinges on familiar challenges: evidence generation for line-of-therapy positioning, formulary strategy, and differentiation against entrenched PD-1/PD-L1 regimens. The report examines these dynamics as ongoing execution variables that can determine whether clinical promise translates into durable revenue capture.
Report Contents and Practical Applications for 2026 Decision-Making
This study is organized to support direct strategic application rather than passive reading. It translates the macro trajectory and competitive context into structured analytical modules that executives can use for planning, diligence, and scenario evaluation. Core contents include:
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
- Historical revenue context and forecast architecture mapped across the full analytical period, showing how growth unfolds from early commercialization into broader adoption and format diversification
- Competitive profiling of leading developers and program architectures, connecting molecule strategy, development stage, and partnership positioning to market implications
- Application landscape analysis that treats indications as commercial segments, assessing where LAG3 therapies can expand and how competitive overlap may shape share capture
- Coverage of format dynamics, including the strategic role of monoclonal and bispecific programs within the broader product architecture
- Regulatory and reimbursement framing that contextualizes approval precedents, evidence expectations, and access strategy within established oncology markets
- Recent development signals and clinical outcome context, including how trial readouts and milestone events can reorient commercial expectations and portfolio prioritization
- Concentrated market structure analysis that clarifies how leadership is being consolidated and what that implies for entrants and collaborators
For executives, these modules are designed to support concrete decisions: whether to prioritize partnership over internal development, how to stage launch readiness across indications, where to monitor clinical data for portfolio impact, and which segments will likely reward early positioning versus late follow-on strategy. The report does not simply describe market size. It provides the connective logic between data points and action.
How the Study Supports Portfolio Strategy, Partnerships, and Investment Committees
In high-growth immunotherapy categories, information asymmetry drives advantage. Companies that understand the interaction of clinical progress, regulatory timing, and competitive concentration can move earlier and with greater precision. Investment committees can use the study to assess not only market scale but also structural defensibility and format risk. Commercial teams can use it to identify where differentiation must be created versus where existing assets can be extended through indication or combination expansion.
The strategic value of the report lies in integration. It places the 26.79 percent growth signal within a context of format diversification, indication evolution, and concentrated leadership dynamics, helping decision-makers interpret what the numbers actually mean for capital allocation and go-to-market design.
Closing the Intelligence Gap for 2026 and Beyond
The worldwide LAG3 antibody market is moving from initial proof of concept toward broader commercial contestation. That transition rewards organizations with disciplined market intelligence. Growth is real, but the opportunity is unevenly distributed across indications, formats, partnerships, and execution timelines. The firms that succeed will be those that interpret the forecast as an operational blueprint rather than a headline estimate.
The full report expands on every dimension outlined here: detailed forecast segmentation, competitive positioning, development stage context, and the strategic implications of the category’s current concentration and format mix. Readers seeking complete figures, segment breakdowns, and the full analytical apparatus are encouraged to access the comprehensive release on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


