



PW Consulting: Global Charging Port Door Actuators Market Hits $341.4M in 2025, Projects 16.5% CAGR to 2032

Charging Port Door Actuators: The Strategic Imperative for EV Interiors in 2026 and Beyond
The electric vehicle market has moved past the phase of proving viability. The conversation among OEMs, Tier 1 suppliers, and procurement leaders has shifted decisively toward refinement, user experience, and the robustness of integrated subsystems. Within this landscape, the charging port door actuator has evolved from a peripheral accessory into a mission-critical component that directly influences brand perception, regulatory compliance, and safety architecture. Our newly published Worldwide Charging Port Door Actuators Market research isolates the forces shaping this niche-but-high-growth segment, offering a decision-grade lens on where value is being created and where risk is accumulating.
For executives planning capital allocation, supplier partnerships, and platform standardization through 2032, this study functions as more than a demand forecast. It reconstructs the competitive field, maps the regulatory pressure points, and exposes the operational bottlenecks that will determine margin sustainability in the years ahead.
The Trajectory: From Niche Add-On to Integrated Vehicle Architecture
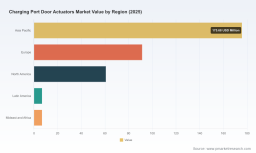
The global market for charging port door actuators reached an estimated valuation of USD 341.4 million in 2025, reflecting a clear acceleration from the USD 275.87 million recorded in 2024. Looking backward, the compound trajectory from 2020 through 2025 demonstrates the compounding effect of electrification tailwinds, with revenue climbing from USD 105.4 million at the start of the window to today's scale. The momentum does not flatten. Forward projections position the market at USD 399.29 million in 2026, expanding steadily to USD 994.36 million by 2032, supported by a forecast-period CAGR of 16.5%.
What makes this growth pattern strategically interesting is not the headline number alone but the forces compressing and expanding demand simultaneously. On one side, standardized charging interfaces across Europe and North America are accelerating adoption curves, with year-over-year sales growth in these regions reaching 27% as regulatory mandates reduce fragmentation. On the other side, supply chain friction around specialized components — particularly rare-earth magnets and precision gear systems — is stretching lead times to 12 to 16 weeks for certain actuator models, forcing procurement teams to rethink inventory buffers and dual-sourcing strategies.
The implication for 2026 planning is clear: demand visibility is strong, but execution risk is rising. Companies that treat the actuator as a commodity electromechanical part will find themselves exposed to both pricing pressure and reliability headaches. Those that integrate the actuator into broader packaging, sealing, and HMI strategies are building defensible positions.
What the Research Unpacks: From Component Specifications to Platform Strategy
This study is built for teams that need to move from macro awareness to actionable decision-making. Rather than停留在 top-line trends, the analysis decomposes the market into the structural dimensions that determine where competitive advantage can be seized.
-
Technology and actuation architecture — The report segments the market by actuator type, contrasting electronic actuators with mechanical release actuators. The analysis examines torque curves, control protocols, integration complexity, and the relative suitability of each architecture for different vehicle platforms and charging use cases.
-
Vehicle electrification pathways — Demand is mapped across battery electric vehicles and plug-in hybrid electric vehicles, with attention to how platform architecture, charging frequency, and port placement influence actuator specification and durability requirements.
-
Geographic concentration and regional regulatory exposure — Regional demand distribution is assessed in the context of local mandates, safety expectations, and manufacturing footprints. The study connects regional sales patterns to the compliance and localization pressures that shape sourcing decisions.
-
Competitive benchmarking and strategic positioning — Profiles of leading suppliers are structured around capability depth, integration readiness, and innovation cadence, enabling side-by-side comparison rather than isolated company summaries.
-
Supply chain and component risk mapping — Beyond demand, the research evaluates the upstream constraints that will influence pricing, lead times, and design flexibility, including magnet availability, gear precision, and control electronics complexity.
-
Functional safety and compliance architecture — The study details how actuators are being engineered to meet functional safety expectations, including fault detection, redundancy, IP67 sealing, wide temperature operation, and child-proof or fail-safe unlocking logic.
Each section is designed to feed directly into sourcing strategy, platform standardization, and supplier evaluation. The intent is to give teams a shared analytical vocabulary — one that connects component-level choices to vehicle-level outcomes and commercial performance.
The Competitive Field: Innovation Concentration and the Tier 1 Race
Market structure matters as much as market size. The charging port door actuator segment exhibits meaningful concentration, with the top three players holding approximately 42.5% of revenue and the top five capturing around 58.2%. This concentration reflects both the technical barriers to reliable automated flap systems and the strategic value OEMs place on proven, integrated solutions. Yet the field remains dynamic, with suppliers differentiating through control architecture, sealing robustness, and the breadth of their platform-compatible offerings.
Worldwide Charging Port Door Actuators Market
Several companies have defined themselves through distinct value propositions that resonate with the current market priorities:
-
Magna International has positioned its SmartAccess Charge Port Door as a complete automated flap system, pairing high-torque actuators with intelligent capacitive entry, false-trigger protection, and optional lighting, locking, and HMI features. The emphasis is on an integrated safety and convenience package rather than a standalone mechanism.
Electric Actuators Market -
Motion Controls Inc brings a high-speed, high-torque actuator portfolio built on its global Active Aero platform production, offering mechanical clutch abuse protection and flexible control options ranging from non-smart setups to full LIN control with patented Lead-Follow technology.
-
NMB Technologies Corporation, through MinebeaMitsumi, supplies customizable charge port door systems and smart BLDC actuators with LIN communication, integrated sensors, LEDs, wireless and gesture control, and anti-pinch or ice-breaking functions tailored for automated EV charge port operation.
-
Haoyong Automotive Controls manufactures multiple CPD actuator models focused on stable, durable opening and closing under frequent use and challenging environmental conditions, serving manual and actuator-driven mechanisms across EV applications.
-
Padmini VNA Mechatronics Ltd produces charge port actuators designed to open and close the port lid via intelligent key or switch in electric and hybrid vehicles, emphasizing reliable mechanical execution in cost-sensitive architectures.
-
WITTE Automotive develops charging port modules with integrated automatic actuators for flush integration, supporting tip-to-run, gesture, and touch control, along with sensors and compact packaging for both AC and DC charging with automatic plug recognition.
-
Röchling Automotive provides kinematic solutions and automatic charging flaps built for reliable port operation, with robust construction, locking, and emergency release as core design priorities.
-
Marquardt offers the E-Lock Gen2 advanced locking actuator for charging plugs in EVs and charging stations, featuring fail-safe mechanical unlocking, a modular design compatible with global standards such as CCS and NACS, and a focus on secure, standards-aligned interfaces.
-
Johnson Electric supplies locking actuators for secure EV charging stations and related motion solutions, extending its motion-control heritage into the charging interface domain.
-
TE Connectivity manufactures AMP+ stand-alone charging inlet actuators for locking plugs in EVs, available in multiple configurations suited to different vehicle types and integration requirements.
The competitive picture is further animated by recent moves that signal where the market is heading. In March 2025, Bosch entered a strategic collaboration to co-develop and supply next-generation charging port door actuators for Volkswagen Group's upcoming electric models, with a focus on improved opening reliability and sealing. In November 2024, Valeo unveiled a modular charging port door actuator system designed for multiple platforms, aiming to enable faster assembly and higher resistance to dirt and water ingress. In May 2024, Continental secured a supply contract for charging port door actuators for a global EV program, reinforcing the importance of proven execution at scale.
Together, these developments illustrate a market in which integration depth, sealing performance, and platform flexibility are becoming the primary differentiators. Suppliers that can deliver reliable operation across environmental extremes while simplifying assembly and aligning with global charging standards are positioning themselves for durable share gains.
The Operating Environment: Regulation, Safety, and the Cost of Reliability
The actuator market is being shaped less by a single disruptor than by a convergence of structural pressures. Regulatory mandates for standardized charging interfaces in Europe and North America are compressing vendor selection windows and accelerating demand, while also raising the bar on compliance. Strict safety expectations in key regions are driving innovation in fail-safe mechanisms and child-proof designs, ensuring that automated access does not introduce new risk profiles.
At the same time, functional safety standards such as ISO 26262 are becoming non-negotiable design constraints. Actuators must support fault detection, redundancy, and environmental resistance, including IP67 sealing and operation across wide temperature ranges. These requirements are not cosmetic. They directly influence part count, control architecture, validation burden, and ultimately the cost structure of the actuator system. Companies that treat compliance as a downstream checklist will find themselves redesigning under pressure. Those that embed safety and sealing logic early in the architecture are better placed to manage both performance and cost.
Supply-side complexity adds another layer. Shortages of specialized components, particularly rare-earth magnets and precision gear systems, are extending lead times and forcing harder choices around design flexibility, inventory strategy, and supplier diversification. For procurement and program management teams, the challenge is not merely securing volume but ensuring that the chosen actuator architecture can withstand component volatility without compromising launch timing or field reliability.
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to connect a high-growth, technically specific market to the decisions that determine competitiveness in 2026 and beyond. The charging port door actuator is no longer an isolated hardware choice. It sits at the intersection of charging standardization, exterior packaging, user experience, safety compliance, and supply chain resilience. That positioning means that actuator decisions reverberate across platform strategy, supplier selection, and margin planning.
For OEMs and platform owners, the research provides a framework for evaluating which actuator architecture best fits a given vehicle strategy, balancing automation depth, control complexity, and integration risk. For Tier 1 suppliers and component manufacturers, it clarifies where differentiation is being rewarded and where commoditization pressure is intensifying. For procurement and supply chain leaders, it surfaces the bottlenecks and concentration risks that should inform sourcing architecture and contingency planning.
The study also helps teams sort signal from noise in a segment where multiple suppliers are making credible claims. By benchmarking capabilities against real-world priorities — sealing, reliability, fail-safe behavior, assembly efficiency, and standards alignment — the analysis supports more disciplined supplier evaluation and more confident partnership decisions.
Moving From Demand Visibility to Execution Discipline
The market's projected expansion from USD 341.4 million in 2025 to nearly USD 1 billion by 2032 is a compelling headline, but the real strategic question is execution. Which actuator architectures will prove most reliable across diverse charging environments? Which suppliers will sustain advantage as safety and sealing expectations tighten? How will organizations manage component volatility while preserving launch certainty? And where will regional regulatory momentum create both opportunity and obligation?
These are the questions that determine whether a company captures value or merely participates in a crowded market. The answers require more than aggregate growth figures. They require a granular understanding of technology trade-offs, competitive positioning, compliance pathways, and supply chain exposure. That is the scope of this research.
For organizations preparing for 2026, the charging port door actuator market offers both a growth opportunity and a test of execution discipline. The companies that succeed will be those that treat the actuator not as a small hardware item but as a strategically integrated system component — one that must perform reliably, comply rigorously, and align with broader platform and charging strategies. Our full market study provides the depth, segmentation, and competitive intelligence needed to make those choices with confidence.
To access the complete analysis, including detailed segmentation, regional context, and full supplier benchmarking, visit the source page for the Worldwide Charging Port Door Actuators Market research. The complete report is designed to support sourcing strategy, platform planning, and competitive positioning with the specificity that 2026 decision-making demands.
For detailed analysis of this topic, please visit the official page: Worldwide Charging Port Door Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


