



PW Consulting: Global Soft Shackle Market Hits $335.25M in 2025, 7.21% CAGR to 2032

Strategic Intelligence: Navigating the Global Soft Shackle Market Trajectory (2026–2032)
The global rigging and load securement landscape is undergoing a structural transformation, driven by a decisive shift from traditional metal hardware to advanced synthetic load-handling solutions. As industrial, automotive, and marine end-users prioritize weight reduction, corrosion resistance, and operational efficiency, the soft shackle market has emerged as a critical node in modern supply chain and recovery ecosystems. Our latest Worldwide Soft Shackle Market study provides a rigorous, forward-looking intelligence framework designed specifically for executive decision-makers, procurement leaders, and strategic planners operating across the 2026–2032 horizon.
Understanding this market requires more than tracking nominal growth figures. It demands a systems-level view of material science adoption, regional deployment patterns, regulatory compliance pathways, and competitive positioning among specialized manufacturers. The following analysis outlines the strategic architecture of our research, demonstrates its immediate applicability to 2026 corporate planning, and clarifies the operational intelligence contained within the full report.
Macro Market Trajectory and Growth Architecture
Over the past half-decade, the global soft shackle sector has demonstrated consistent revenue expansion, reflecting accelerated commercialization, broader application penetration, and increasing substitution of steel-based hardware across high-stress load environments. From a historical baseline of approximately $236.42 million in 2020, market revenue advanced through a period of methodological scaling and manufacturing maturation, reaching an estimated $335.25 million by 2025. This trajectory establishes a firm foundation for the current forecast cycle, with projected revenue crossing the $380.64 million threshold in 2026 and continuing to scale toward $545.43 million by 2032.
The forecasted compound annual growth rate of 7.21 percent across the 2026–2032 period signals a sustained mid-to-high single-digit expansion environment. This growth is not merely cyclical; it is structurally anchored in material performance advantages, safety protocol evolution, and cross-industry standardization of synthetic rigging components. For corporate strategists, this trajectory implies that demand forecasting, inventory positioning, and capacity planning must account for a multi-year upward slope rather than discrete product launches or short-term procurement cycles. The dataset underlying this projection captures cumulative adoption curves, regional revenue flows, and application-driven consumption patterns, offering a calibrated baseline for scenario modeling and capital allocation decisions in 2026.
Structural Segmentation and Material Substitution Dynamics
The market architecture is defined by three interlocking segmentation dimensions: material composition, geographic deployment, and end-use application categories. At the core of product differentiation lies the dominance of Ultra High Molecular Weight Polyethylene (UHMWPE) fibers—frequently referenced in commercial and technical contexts as Dyneema or Plasma-based synthetic lines. UHMWPE soft shackles have established a clear performance premium by delivering strength-to-weight ratios that substantially exceed conventional steel alternatives, while simultaneously providing inherent corrosion resistance, buoyancy characteristics, and reduced operator fatigue during overhead or mobile load handling.
Complementing the UHMWPE segment, aramid and Technora-based shackle variants occupy specialized deployment niches where thermal stability, cut resistance, and specific load-direction requirements dictate material selection. Remaining synthetic fiber alternatives serve cost-sensitive or application-specific use cases, contributing to a diversified material ecosystem that allows procurement teams to balance performance specifications, compliance mandates, and total cost of ownership. The segmentation data contained in the full report maps these material pathways against regional consumption volumes and application-driven demand, enabling precise matching of product portfolios to target markets without relying on broad generalizations.
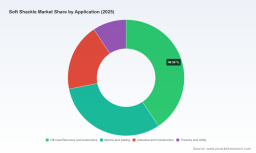
From an application perspective, demand distribution spans off-road recovery and automotive operations, marine and sailing environments, industrial and construction rigging, as well as forestry and utility workflows. Each application category presents distinct performance thresholds, safety factor requirements, and environmental stressors. The research delineates how these application segments interact with regional procurement practices, certification expectations, and replacement-cycle economics, providing a decision-ready framework for product positioning and channel strategy.
Competitive Landscape and Firm-Level Strategic Positioning
The soft shackle market exhibits a moderately concentrated competitive structure, characterized by specialized manufacturers that compete on material engineering, testing rigor, certification compliance, and application-specific product design. The cumulative market share concentration reflects a landscape where established trauma-recovery and marine hardware players coexist with emerging synthetic-focused producers, each carving out defensible positions through proprietary coatings, braided guard architectures, load-testing protocols, and traceability systems.
Firms such as ASR Offroad and Factor 55 have built recognized positions in off-road and heavy vehicle recovery segments by emphasizing abrasion protection, consistent minimum breaking strengths, and laboratory- and field-validated performance metrics. Their product lines incorporate protective jackets, fiber-locking coatings, and braided guard configurations designed to mitigate wear in high-friction recovery scenarios. Similarly, Bubba Rope has expanded its synthetic soft shackle offerings across off-road 4x4, agriculture, mining, and marine towing applications, leveraging the weight and corrosion advantages of Plasma-based constructions to position synthetic alternatives as superior to steel in demanding field conditions.
On the specialized and compliance-driven end of the spectrum, Safe-Xtract has developed military-approved soft shackles manufactured from next-generation synthetic line with proprietary protective coatings. These products operate under Berry Amendment and Buy American Act compliance frameworks, with serialized traceability and factory load-testing protocols that align with U.S. military SOCOM deployment requirements. This compliance layer illustrates how regulatory and procurement mandates can create highly durable competitive moats for manufacturers that invest early in certification infrastructure and documented quality management systems.
Parallel developments appear in the lifting, rigging, and marine hardware segments. Companies including Cortland Company, Erickson Manufacturing, Robship, Wichard, Fulcrum Lifting, and Dynamica Ropes contribute application-tailored solutions spanning rope-on-rope connection systems, towing and load securement configurations, and compact marine rigging components. Their product development efforts emphasize fatigue testing, break-strength validation, strength-to-weight optimization, and optional abrasion covers or machine-stretching processes. Together, these firms illustrate a market in which differentiation arises less from scale alone and more from engineering specificity, testing transparency, and application-aligned design philosophy.
Manufacturing quality infrastructure further reinforces competitive differentiation. Several premium producers operate under ISO 9001:2015-certified facility standards, integrating consistent quality management into fiber sourcing, braiding, assembly, and final inspection workflows. For procurement and supply chain leaders, these quality certifications are not merely administrative markers; they represent verifiable risk-reduction mechanisms in overhead lifting, dynamic recovery, and critical load-handling environments.
Industry Dynamics, Compliance Frameworks, and Operational Risk Management
Beyond product specifications and firm positioning, the market is shaped by a set of operational and regulatory dynamics that directly influence procurement strategy, safety planning, and deployment protocols. Material science remains the foundational driver: synthetic soft shackles continue to gain acceptance because they combine superior strength-to-weight characteristics with corrosion immunity and, in many configurations, flotation properties that enhance safety during marine and water-adjacent operations.
Safety standardization practices have also evolved. In overhead lifting contexts, soft shackles can be configured with documented safety factor tagging—commonly at a 5:1 ratio upon customer request—supported by manufacturer-conducted laboratory and field testing for minimum breaking strengths and fatigue performance. This capability enables lifting and rigging operators to integrate synthetic hardware into controlled lifting plans with clear load-rating documentation, bridging the gap between traditional metal shackle protocols and modern synthetic alternatives.
Regulatory and procurement environments introduce additional strategic layers. Certain soft shackle products have achieved military specification alignment, with compliance under the Berry Amendment and Buy American Act facilitating integration into U.S. military vehicle and recovery programs. For commercial manufacturers, these compliance pathways create both opportunity and execution complexity: they require supply chain transparency, domestic content verification, and traceable quality documentation. Firms that systematically address these requirements position themselves for repeat procurement cycles in government and defense-adjacent channels, while also signaling reliability to commercial buyers who value documented conformance.
Worldwide Soft Shackle Market
From an operational risk perspective, the shift toward synthetic shackles requires updated inspection routines, wear-pattern monitoring, and UV/abrasion awareness. Manufacturers increasingly support these needs through protective jackets, optional covers, and machine-stretching processes that improve consistency and reduce dimensional variance. The full report examines how these operational considerations affect replacement cycles, stocking strategies, and field maintenance planning across the major application categories.
Report Architecture: Executive Intelligence for 2026 Planning
The Worldwide Soft Shackle Market research is structured to deliver actionable intelligence across multiple planning horizons. Rather than presenting static size estimates, the report integrates historical revenue progression, forward-looking forecast trajectories, segmentation alignments, competitive profiles, and dynamic factor analysis into a single decision-support architecture. Executive readers will find direct utility in the following components:
- Market sizing and forecasting framework: A calibrated revenue baseline spanning historical years through 2025, extended across the 2026–2032 forecast window, with growth-rate context that supports capacity planning, inventory modeling, and revenue scenario construction.
- Segmentation mapping: Detailed alignment of material types, geographic regions, and application categories, enabling precise identification of high-potential demand clusters and portfolio targeting opportunities.
- Competitive profiling: Firm-level assessments of leading manufacturers, covering product engineering focus, certification posture, manufacturing quality standards, application coverage, and differentiation strategy.
- Industry dynamics and compliance mapping: Analysis of material substitution drivers, safety factor practices, military and procurement compliance pathways, and quality management certifications that shape buyer decision criteria.
- Strategic implication synthesis: Translational guidance connecting market structure to sourcing strategy, product positioning, channel development, and risk-adjusted deployment planning for 2026 and beyond.
Each component is designed to stand alone for targeted reading while also functioning as an integrated intelligence system. Procurement teams can use the segmentation and dynamic-factor sections to refine specification requirements and supplier evaluation criteria. Product and marketing leaders can leverage competitive profiles and application mappings to align messaging, feature prioritization, and regional go-to-market sequencing. Corporate strategists can apply the forecast architecture and concentration context to evaluate growth resilience, channel diversification, and investment timing.
Side Shaft Market
Strategic Applications for 2026 Decision-Making
For organizations planning 2026 operations, the soft shackle market presents both opportunity and execution complexity. Demand is expanding across multiple application environments, but the rate and shape of adoption differ by region, material preference, and compliance requirement. Companies that approach the market with granular intelligence will be better positioned to align product specifications with real deployment conditions, avoid overgeneralization in marketing and sales targeting, and structure procurement relationships around documented performance and certification evidence.
In practical terms, the research supports several immediate planning functions:
- Sourcing and specification optimization: Matching material categories and safety-factor configurations to actual load profiles, environmental exposure, and regulatory expectations rather than relying on generic hardware substitution assumptions.
- Portfolio and channel alignment: Identifying which application segments and geographic flows offer the strongest resonance for specific product architectures, protective features, and certification footprints.
- Competitive positioning and procurement risk: Understanding how manufacturing quality standards, testing protocols, and compliance certifications influence buyer trust, repeat purchasing, and supply continuity.
- Forecast-informed resource allocation: Using multi-year revenue trajectories and growth-rate context to shape inventory planning, production scheduling, and market-entry sequencing with appropriate confidence intervals.
Conclusion: From Market Awareness to Actionable Advantage
The Worldwide Soft Shackle Market study delivers more than a retrospective size estimate or a forward-looking growth figure. It provides a structured, evidence-based view of how material innovation, application diversification, compliance requirements, and competitive specialization are reshaping load-handling hardware selection across industrial, automotive, marine, and lifting environments. For executives and strategists operating in 2026, the distinction between reactive procurement and proactive positioning depends on access to segmentation detail, firm-level intelligence, and dynamic-factor analysis that connect market structure to operational decision-making.
The complete report contains the full segmentation breakdowns, regional revenue distributions, application-level demand mappings, competitive assessment depth, and compliance and testing analyses required to translate market awareness into concrete strategy. Readers seeking the complete intelligence package, including detailed data tables, segmentation splits, and expanded manufacturer profiles, are encouraged to access the full report through the official research portal. There, the full dataset and analytical framework are available to support targeted planning, supplier evaluation, and long-range strategic positioning across the 2026–2032 market cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Shackle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


