



PW Consulting: Global Surgical Tray Market to Hit $801.59M by 2032 Driven by 5.81% CAGR

Strategic Intelligence for Surgical Tray Markets: Navigating Growth Through 2032
The global surgical tray market stands at a critical inflection point as healthcare delivery models, sterilization science, and supply chain economics converge. Our latest Worldwide Surgical Tray Market research provides decision-makers with a structured, evidence-based view of where value is being created, where pressure is intensifying, and how leading organizations are positioning for the 2026–2032 horizon. This introduction outlines the strategic architecture of the study, demonstrates its relevance to corporate planning, and invites executive teams to access the full intelligence suite for detailed segmentation, competitive benchmarking, and forward-looking scenario analysis.
A Market Defined by Structural Expansion and Operational Complexity
Historical performance shows a market that has consistently expanded through cycles of capacity investment, protocol refinement, and procedural volume growth. From a baseline in the early 2020s, revenue progression has accelerated into a mid-single-digit compound annual growth trajectory forecast to sustain through the end of the decade. The overall market size has climbed steadily from 2020 through 2025, with the latest base-year valuation reflecting sustained demand across both reusable and disposable formats. Forecasts extending to 2032 indicate a continued upward path, with the market expected to move decisively past the 700 million USD threshold before reaching a final projected valuation near 800 million USD.
This scale is not merely a function of procedural volume. The growth profile reflects a combination of sterilization modernization, tray standardization initiatives, and the ongoing tension between infection prevention imperatives and cost containment pressures. Organizations that treat surgical trays as a commoditized logistics item often underestimate the operating leverage embedded in tray design, reprocessing efficiency, material durability, and procedural-specific customization. Our research frames the market through that lens: trays are not passive containers but active components in sterile workflow, turnaround time optimization, and clinical outcomes.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands clarity on three interlocking questions:
- Which material and format choices offer the best balance of lifecycle cost, reprocessing compliance, and user preference across care settings?
- How are concentration patterns, supplier capabilities, and recent product or contract developments reshaping procurement leverage?
- Where do regulatory, reimbursement, and sterilization validation requirements create barriers, enablers, or margin opportunities?
Our study is built to answer these questions with data that can be operationalized. Rather than stopping at high-level market sizing, the analysis connects macro trends to procurement strategy, tray engineering trade-offs, sterile processing economics, and competitive positioning. For manufacturers, the research supports roadmap decisions around material mix, reusable versus disposable portfolio balance, and regional capability deployment. For providers and sterile processing leaders, it informs standardization strategies, vendor evaluation criteria, and total-cost-of-ownership modeling. For investors and corporate development teams, it clarifies where market concentration and innovation activity suggest durable advantages versus crowded segments.
Report Architecture: Practical Intelligence, Not Abstract Synthesis
The Worldwide Surgical Tray Market study is organized to support rapid executive consumption while offering enough depth for cross-functional planning. The report moves from market foundation to actionable segmentation, then integrates competitive intelligence and regulatory context into a coherent decision framework.
What the Study Covers
- Historical market performance and forward-looking projections anchored to a consistent methodology, including a clearly defined base year, retrospective window, and forecast horizon through 2032.
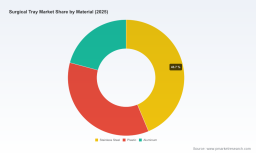
- Segment-level perspective across material choices and tray types, with attention to how stainless steel, plastic, and aluminum applications differ in utilization patterns, reprocessing requirements, and cost structures.
- End-user demand analysis spanning hospitals, ambulatory surgical centers, and specialty clinics, reflecting distinct purchasing behaviors, procedure mixes, and turnaround priorities.
- Regional assessment across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, framed around market maturity, supplier presence, and procedural environment differences.
- Competitive landscape mapping for major participants, including profile context and a set of recent developments that illustrate how product innovation, contract wins, and catalog expansion are shaping the market.
- Regulatory, reimbursement, and sterilization governance considerations that directly affect product classification, validation burden, and procurement economics.
Material and Format Dynamics: The Core Trade-Offs
Material selection remains one of the most consequential design decisions in surgical tray planning. Stainless steel continues to anchor reusable workflows because of durability, compatibility with reprocessing cycles, and long-term cost amortization. Plastic-based solutions serve high-throughput disposable needs where convenience, reduced reprocessing dependency, and single-use safety considerations dominate procurement thinking. Aluminum appears where weight, cost, and specific procedural requirements drive a middle path between permanence and portability.
The broader tray conversation is similarly bifurcated. Reusable trays emphasize reprocessing infrastructure, sterilization validation, and instrument longevity, while disposable trays emphasize workflow simplicity, inventory flexibility, and reduced cleaning variability. The research does not treat either format as universally superior. Instead, it examines where each format is gaining traction based on setting-specific pressures, infection control protocols, and total cost structures. In doing so, the study helps leaders evaluate not just what is being purchased today, but how format preferences may shift as sterilization technology, staffing models, and reimbursement incentives evolve.
Procurement Realities Across Care Settings
End-user segmentation reveals how differently surgical trays are valued depending on the clinical environment. Large hospital systems typically integrate trays into broader sterile processing strategies, where reprocessing throughput, instrument availability, and validation consistency directly affect operating room readiness. Ambulatory surgical centers often prioritize convenience, turnaround speed, and cost predictability, especially in settings where procedural volume is high but on-site reprocessing resources are limited. Specialty clinics sit in a distinct position, with procedure-specific requirements that can make customized or application-focused tray configurations more relevant than generic standardization alone.
Our analysis connects these setting-specific realities to purchasing behavior, service expectations, and contract design. This is crucial because the same tray can function as a cost center in one environment and a workflow enabler in another. Decision-makers who understand these differences are better positioned to negotiate terms, design service agreements, and align product specifications with real operational constraints rather than generic assumptions.
Competitive Landscape: Concentration, Capability, and Recent Moves
The market is not evenly distributed. Competitive concentration is meaningful, with the top three participants and the top five participants together representing a substantial share of overall activity. That concentration suggests that scale, distribution reach, sterilization expertise, and procedural portfolio depth continue to matter. At the same time, specialized players can compete effectively by focusing on niche applications, custom configurations, or highly differentiated sterilization container systems.
Several leading organizations anchor the market. Cardinal Health is widely recognized for custom sterile surgical procedure trays and packs serving operating rooms globally. Medline Industries produces reusable stainless steel and disposable plastic instrument trays with sterilization compatibility in mind, while B. Braun Melsungen AG offers modular stainless steel trays and containers designed for steam and EO sterilization across international markets. Steris contributes rigid sterilization container systems and surgical trays tailored for hospital central sterile processing departments. Teleflex supports specialty surgical trays through its Pilling brand, including perforated and solid bottom instrument trays. Integra LifeSciences serves neurosurgery and orthopedic surgical needs through Miltex instruments and accessories, while Becton, Dickinson and Company integrates surgical trays into procedure kits for vascular and general surgery. Mölnlycke Health Care develops custom procedure trays for wound care and general surgery applications internationally.
What matters strategically is not only who is present, but how these organizations are executing. Recent market activity illustrates the pace of change. In late 2023, Steris plc introduced a next-generation rigid container system intended to enhance sterilization efficiency for surgical trays, signaling continued investment in reprocessing performance. Earlier that year, Cardinal Health secured a multi-year supply agreement with a major US hospital system for custom surgical trays, reinforcing the importance of long-term service relationships and institutional standardization. In late 2022, Medline released an expanded surgical tray catalog featuring new anti-fog and modular designs, demonstrating how product-level innovation can broaden application fit and user appeal.
These developments are not isolated events. They reflect a broader pattern in which suppliers compete on sterilization efficiency, customization capability, material performance, and procurement partnerships. Our report translates such moves into competitive signals that procurement teams, product planners, and strategy leaders can actually use.
Regulatory, Reimbursement, and Sterilization Context
Surgical tray decisions do not happen in a vacuum. They are shaped by standards, device classification, sterilization validation, and payment frameworks that influence both product design and commercial readiness.
Sterilization quality remains foundational. Surgical trays must comply with ISO 17665-1 for moist heat sterilization validation, and reusable trays require validated cleaning protocols per AAMI ST79 to keep bioburden within acceptable limits. These requirements are not administrative footnotes; they determine reprocessing reliability, failure risk, and the operating burden placed on central sterile processing departments. In parallel, most surgical instrument trays are classified as Class II devices under FDA oversight, requiring 510(k) premarket notification for many offerings. That classification influences time-to-market, documentation requirements, and the level of technical rigor needed from manufacturers.
On the financial side, tray economics intersect with reimbursement structures. Surgical trays are included in CMS DRG payments for inpatient procedures under relevant major operating room case categories, which ties tray costs to broader procedure payment logic rather than treating them as standalone consumables. This link matters because it shapes how hospitals evaluate cost, how suppliers frame value, and how procurement teams assess whether a tray solution reduces downstream risk or simply adds visible expense.
Material cost dynamics also affect long-term planning. Medical-grade 316L stainless steel used for reusable trays carries a unit cost that can materially influence durable product economics, especially when procurement teams model total lifecycle cost rather than unit price alone. Combined with sterilization validation, instrument life expectancy, and reprocessing labor, the true cost picture becomes more nuanced than a simple reusable-versus-disposable comparison.
Worldwide Surgical Tray Market
What the Full Report Enables Beyond This Overview
This introduction is deliberately designed to demonstrate analytical depth without revealing the detailed figures and split-level sensitivities that sit inside the complete study. The full report provides:
Sterilization Trays Market
- Granular market size and forecast values across the historical period and the 2026–2032 forecast window.
- Segment-level market values across material types, tray formats, and end-user categories.
- Regional breakdowns that allow leadership to prioritize expansion, sourcing, or partnership moves by geography.
- Contextual competitive evaluation that ties recent product launches, contract awards, and catalog changes to market positioning.
- Practical guidance for interpreting regulatory and sterilization requirements in commercial and operational terms.
By reserving those specifics for the complete report, we ensure that executive readers receive both credibility and curiosity: enough substantive insight to trust the methodology, and enough unresolved detail to justify accessing the full intelligence set.
Where to Focus Next
For teams planning 2026 budgets, product roadmaps, supplier evaluations, or market entry assessments, the immediate value of this research lies in its ability to turn market growth into actionable strategy. The worldwide surgical tray market is not simply expanding; it is evolving in response to sterilization efficiency demands, procedural standardization pressures, and competitive consolidation. Organizations that use this study as a strategic reference point will be better equipped to distinguish short-term procurement noise from structural opportunity.
The complete Worldwide Surgical Tray Market report provides the detailed segmentation, competitive benchmarking, and forecast architecture needed to support those decisions. We recommend aligning planning teams around the full study so that market insight can be translated into concrete actions across product strategy, purchasing strategy, and growth planning.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Tray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


