



PW Consulting: Worldwide D-Ring Blood Pressure Cuffs Market Hits $539.36M in 2025, Projected 7.0% CAGR to 2032

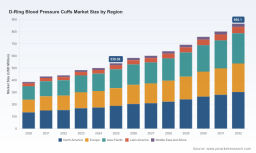
The Strategic Imperative of D-Ring Blood Pressure Cuffs: Navigating Market Growth Through 2032
In the rapidly evolving landscape of medical devices, few components are as ubiquitous yet critically underanalyzed as the D-ring blood pressure cuff. As healthcare systems globally shift toward early detection, home monitoring, and cost-effective chronic disease management, the demand for reliable, standardized cuff technology has accelerated. PW Consulting is pleased to introduce our comprehensive Worldwide D-Ring Blood Pressure Cuffs Market study, a strategic intelligence report designed to equip executives, procurement leaders, and product strategists with the foresight required to navigate market expansion from 2026 through 2032. This article outlines the core trajectory of the market, the operational and regulatory forces shaping competitive dynamics, and the actionable frameworks embedded within the full research deliverable.
Worldwide D-Ring Blood Pressure Cuffs Market
A Market Defined by Steadiness and Structural Expansion
The D-ring blood pressure cuff segment has demonstrated consistent growth, reflecting both the aging global population and the widespread adoption of non-invasive monitoring protocols across clinical and homecare environments. Drawing on historical tracking from 2020 through the 2025 base year, the market has progressed from a revenue base of approximately 385.4 million USD to a projected 539.4 million USD in 2025. Looking forward across the 2026 to 2032 forecast horizon, the market is positioned to reach 866.1 million USD by the close of the period, underpinned by a compound annual growth rate of 7.0 percent. These figures signal more than incremental volume increases; they indicate a structural reorientation of where and how blood pressure measurement occurs.
Growth is increasingly being driven by the transition from single-use, disposable-only protocols toward versatile, standardized D-ring designs that accommodate both clinical-grade accuracy and patient-friendly usability. The durability of nylon filament structures, the widespread availability of polyester blends, and the expanding role of non-woven fabric variants have collectively broadened the design palette available to manufacturers, while simultaneously creating distinct procurement pathways for buyers in different care settings. The market’s expansion trajectory is also reinforced by reimbursement frameworks that continue to recognize reusable cuffs as essential durable medical equipment, creating a stable demand floor that supports long-term product roadmaps.
Structural Segmentation: What Decision-Makers Must Evaluate
While aggregate market sizing establishes the baseline opportunity, real strategic advantage emerges when organizations understand how value is distributed across regions, materials, and end-user channels. Our research maps these dimensions with granular operational context, enabling buyers and suppliers to align product positioning, inventory planning, and geographic expansion strategies with actual demand signals rather than broad assumptions.
Geographically, demand patterns reveal meaningful disparities in volume concentration and growth velocity. North America remains a dominant market pillar, reflecting mature clinical procurement cycles, established reimbursement structures, and high adoption rates of standardized cuff formats. Europe follows as a substantial demand center, shaped by harmonized regulatory expectations and growing institutional preferences for latex-free, clinically validated designs. Asia Pacific presents a highly dynamic profile, combining rapid healthcare infrastructure expansion with rising consumer awareness of home monitoring, while Latin America and the Middle East and Africa reflect smaller but strategically relevant volumes that reward targeted entry strategies and differentiated distribution partnerships.
Material selection represents another critical axis of differentiation. Nylon continues to command the largest share of market preference, favored for its tensile durability and compatibility with repeated clinical use. Polyester configurations serve as a widely deployed alternative, particularly where cost efficiency and specific ergonomic profiles are prioritized. Non-woven fabric variants occupy a specialized but expanding role, most notably in settings that emphasize disposable workflows, infection control, or specific patient comfort requirements. The interplay between material availability, cost structures, and end-user compliance profiles makes material strategy a direct contributor to margin performance and product acceptance.
End-user segmentation further clarifies how purchasing behavior diverges across care environments. Homecare settings have emerged as the largest volume driver, reflecting the broad shift toward self-managed hypertension monitoring and the increasing availability of user-friendly D-ring cuffs compatible with both professional and consumer-grade devices. Hospitals and clinics remain a foundational channel, where cuff selection is influenced by throughput requirements, compatibility with multi-parameter monitors, and institutional procurement standards. Ambulatory surgical centers and related outpatient environments represent a more specialized but operationally important channel, where precision, quick fitting, and disinfection compatibility guide procurement decisions.
Worldwide Fingertip Pulse Blood Pressure Meter Market
Competitive Landscape: Positioning Among Leading Manufacturers
The market is characterized by a moderately concentrated competitive environment, where a core group of experienced device manufacturers and component suppliers holds a substantial share of reputational and distribution advantage. Understanding how these players differentiate their D-ring offerings is essential for both incumbents evaluating defensive strategies and new entrants assessing whitespace opportunities.
Among the most established participants, Welch Allyn, operating under Hillrom in the United States, has built recognition around FlexiPort D-ring cuffs offering both reusable and disposable formats across adult, thigh, and large adult sizes. Their compatibility emphasis and broad size range position them as a preferred choice for facilities seeking standardization across multiple monitor platforms. Omron Healthcare, based in Japan, has strengthened its footprint with D-ring style cuffs designed for both home and professional use, notable for wide-range sizing that extends from small adult to extra-large configurations. This range flexibility supports their dual focus on consumer accessibility and clinical reliability.
GE Healthcare maintains a strong clinical-supply presence through DINAMAP D-ring cuffs, available in single-patient use and reusable models, with sizing that spans neonates to thigh applications. Their integration of FlexiPort technology underscores a continued focus on connectivity and workflow efficiency in acute-care environments. Philips, headquartered in the Netherlands, offers D-ring cuffs tailored for IntelliVue and SureSigns monitors, including adult long and thigh sizes delivered in latex-free materials, reinforcing the importance of material safety standards in hospital procurement.
Additional players contribute meaningful portfolio depth to the market. SunTech Medical’s Advantage D-ring cuffs utilize segmented bladder designs to improve fit accuracy, offered in both reusable and disposable options across limb sizes, including expanded bariatric coverage released in recent product catalog updates. A&D Medical provides D-ring cuffs for its UA-611 platform and professional sphygmomanometers, emphasizing durable nylon construction suited to repeated adult and large adult use. American Diagnostic Corporation (ADC) continues to serve a reliability-focused segment with diagnostically accurate D-ring cuffs compatible with its aneroid gauge systems, leveraging proprietary stretch fabric to support consistent measurement performance across multiple sizes.
Recent activity among these companies highlights how product certification, catalog expansion, and exhibition visibility are being used to reinforce positioning. In late 2024, GE Healthcare received FDA 510(k) clearance for new DINAMAP ProCare D-ring cuffs with improved antimicrobial properties, a development that aligns with growing institutional emphasis on infection prevention in reusable device lines. Around the same period, Hillrom showcased FlexiPort D-ring cuffs at ACC.24 with demonstrations focused on one-tube connectivity, reinforcing workflow simplification as a buyer consideration. In mid-2024, SunTech Medical expanded its Advantage D-ring line to include bariatric sizes in both reusable and single-patient use formats, broadening applicability in higher-acuity and specialized patient populations.
Regulatory, Reimbursement, and Material Dynamics as Strategic Forces
Market performance in this segment is not solely a function of demand volume; it is also shaped by compliance expectations, cost-of-goods realities, and reimbursement policy. These dynamics influence go-to-market timing, product design tradeoffs, and the economics of scale.
On the regulatory side, D-ring cuffs must comply with ISO 81060-1:2019 for non-invasive sphygmomanometers, which requires clinical validation for accuracy within ±5 mmHg. This standard is not merely a technical checkbox; it establishes the baseline for institutional purchasing confidence, especially in hospital and clinic settings where measurement reliability directly affects clinical decision-making. For manufacturers, maintaining documented validation and ensuring consistent production quality is a competitive prerequisite, not an optional enhancement.
Material cost realities further shape strategic planning. Medical-grade nylon fabric for D-ring cuffs typically ranges from 4 to 7 USD per square meter, while PVC bladders can be sourced at approximately 2 to 3 USD per unit in bulk production. These input-cost parameters directly affect margin architecture and pricing flexibility, particularly in price-sensitive channels where procurement teams balance performance requirements against budget constraints. Companies that can stabilize supply chains, negotiate volume agreements, and optimize material utilization gain a structural cost advantage that becomes more pronounced as production scales.
Reimbursement policy also forms a critical demand enabler. Under current coding frameworks, HCPCS code A4574 covers reusable blood pressure cuffs, including D-ring styles, with reimbursement generally falling in the range of 15 to 25 USD per unit under Medicare Part B. This reimbursement visibility supports recurring procurement in eligible care environments and gives suppliers a predictable commercial context within which to plan product introduction and pricing. Meanwhile, institutional safety standards continue to influence product specifications: latex-free D-ring cuffs are required in a substantial majority of U.S. hospitals under Joint Commission standards to minimize allergic reaction risk, reinforcing material selection as both a compliance and market-access issue.
Why This Research Matters for 2026 Decision-Making
As the forecast period begins, executives face a market that is expanding predictably but competing intensely on precision, compatibility, material safety, and supply efficiency. The 7.0 percent CAGR trajectory suggests that growth will remain durable, but it also raises the stakes for companies that must decide where to invest, what product variants to prioritize, and how to position against established players with deep procurement relationships. Our study is structured to convert this broad market momentum into actionable intelligence.
The report provides detailed segmentation analysis across regions, materials, and end-user environments without leaving readers to infer demand patterns from high-level aggregates. It examines how procurement behaviors differ by care setting, how price sensitivity intersects with compliance requirements, and how material choice affects both product performance and total cost of ownership. In parallel, the competitive assessment maps out the strategic postures of leading manufacturers, identifies the practical implications of recent product certifications and catalog expansions, and highlights the areas where differentiation is becoming increasingly difficult versus where genuine whitespace remains.
Beyond segmentation and competitor profiling, the full report integrates market concentration data, demand drivers, restraint factors, and scenario-informed forecasting to help organizations test their assumptions before committing capital. Readers will find operational guidance on evaluating compatibility claims, understanding how antimicrobial or latex-free features influence purchasing criteria, and interpreting the implications of reimbursement and regulatory frameworks for product launches and inventory planning. For procurement teams, the study clarifies the tradeoffs between reusable durability and disposable infection-control logic. For manufacturers, it identifies which product attributes are becoming table stakes and which still offer room for premium positioning.
Conclusion: Turning Market Momentum into Informed Strategy
The worldwide D-ring blood pressure cuffs market is entering a phase where steady top-line growth meets increasingly sophisticated buyer expectations. Organizations that treat cuff selection as a commodity decision risk missing the strategic implications embedded in material standards, compatibility design, reimbursement eligibility, and clinical validation requirements. Those that approach the segment with structured, evidence-based intelligence will be better positioned to choose the right geographies, the right product configurations, and the right competitive posture as the 2026 to 2032 period unfolds.
PW Consulting’s Worldwide D-Ring Blood Pressure Cuffs Market report is designed to serve as that strategic foundation. By combining historical context, forward-looking forecasts, segmentation depth, and competitive and regulatory analysis, the study enables decision-makers to move beyond generalized market narratives and toward specific, defensible actions. The full report expands on every dimension outlined here and provides the detailed data sets, vendor evaluations, and market trajectory analysis necessary to support executive planning, product strategy, and procurement alignment. For organizations seeking to convert market opportunity into measurable advantage, the complete research offers the clarity required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide D-Ring Blood Pressure Cuffs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


