



PW Consulting: Global Radiator Flushing Chemicals Market Hits $225.5M in 2025, 5.48% CAGR to 2032

Global Radiator Flushing Chemicals Market 2026: Executive Intelligence Brief
Market Trajectory and Strategic Relevance
The Worldwide Radiator Flushing Chemicals Market has entered a decisive inflection period. Between 2020 and 2025, global revenue expanded from 172.4 million USD to 225.5 million USD, reflecting a compound trajectory that has accelerated through fleet modernization, extended cooling-system intervals, and heightened aftermarket maintenance awareness. Our latest research traces this momentum through a detailed 2026-2032 forecast window, during which the market is projected to reach 327.61 million USD, underpinned by a forecasted CAGR of 5.48 percent. This growth trajectory is not merely a function of volume expansion; it signals structural shifts in formulation strategy, regional sourcing dynamics, and competitive positioning that demand proactive planning from chemical manufacturers, distributors, and automotive aftermarket operators.
For executives calibrating 2026 budgets, capacity investments, and go-to-market strategies, the market presents a nuanced opportunity landscape. Demand is increasingly shaped by the interplay of raw material price cycles, evolving engine architectures, and regional maintenance habits. Understanding where margin pools are forming, which vehicle segments are outpacing baseline growth, and how leading manufacturers are adapting their product architectures requires more than top-line figures. It requires a granular view of competitive positioning, formulation differentiation, and regional demand intensity that our research delivers in a structured, decision-ready format.
Formulation Architecture and Segment Leadership
The product chemistry landscape remains anchored in acid-based and alkaline-based formulations, with solvent-based variants capturing a distinct niche tied to specialized cleaning performance and equipment compatibility requirements. Acid-based chemistries continue to lead in total revenue contribution, driven by their established efficacy in removing mineral scale, corrosion deposits, and coolant degradation byproducts across diverse cooling-system architectures. Alkaline-based solutions maintain strong positioning where compatibility with aluminum components, extended service intervals, and reduced metal erosion are strategic priorities. Solvent-based formulations, while representing a smaller share of total market revenue, are gaining attention in applications where rapid deposit removal, low-foam performance, and targeted system revitalization are critical to service throughput.
Vehicle-type segmentation reveals a hierarchy of demand intensity that reflects broader automotive fleet structures and maintenance behavior. Passenger cars account for the largest revenue pool, supported by high vehicle density, routine cooling-system maintenance cycles, and strong aftermarket retail distribution. Light commercial vehicles form the second major demand pillar, with fleet operators increasingly standardizing preventive cooling-system flushing as part of scheduled maintenance programs. Heavy commercial vehicles represent a specialized segment where extended thermal loads, severe operating conditions, and long service life create differentiated product requirements around deposit control, corrosion suppression, and formulation durability under continuous-duty environments.
Worldwide Radiator Flushing Chemicals Market
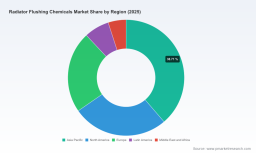
Regional demand patterns reinforce the importance of localized distribution strength and product adaptation. Asia Pacific demonstrates the highest revenue concentration, reflecting dense vehicle parc growth, expanding aftermarket networks, and increasing adoption of cooling-system maintenance protocols across both passenger and commercial fleets. North America and Europe maintain robust demand bases shaped by mature service infrastructure, stringent performance expectations, and established brand loyalty in the chemicals and aftermarket segments. Latin America and the Middle East and Africa region contribute targeted growth opportunities where infrastructure expansion, fleet renewal, and increasing awareness of cooling-system care are creating incremental demand. Detailed regional revenue breakdowns, growth differentials, and priority submarkets are mapped comprehensively within the full report to support country-level planning and channel strategy.
Competitive Positioning and Strategic Differentiation
The competitive landscape in radiator flushing chemicals is characterized by a balanced concentration profile, with the top three players collectively commanding approximately 38.45 percent of market revenue and the top five firms accounting for roughly 52.12 percent. This structure indicates both established brand presence and meaningful room for differentiation through formulation innovation, distribution expansion, and service-channel integration. Strategic positioning among the market's core participants reflects a mix of specialty formulation expertise, broad aftermarket reach, and targeted product architectures designed to address specific cooling-system failure modes and maintenance workflows.
Major participants such as Prestone Products Corporation emphasize multistep cleaning functionality, offering cooling-system formulations designed to remove build-up, corrosion, and rust while maintaining compatibility across manufacturer-specific radiator and cooling-system materials. Valvoline Inc. continues to leverage its broader coolant ecosystem, aligning radiator flush products with coolant service lines and promoting contaminant removal as part of integrated cooling-system maintenance. Liqui Moly GmbH focuses on restoring cooling-system performance through formulations intended to eliminate scale, grease, sludge, and deposits across water-cooled engine applications. CRC Industries, Inc. has built recognition around acid-free rapid-flush and rust-removal solutions that target rust, scum, oil, and scale while aiming to revitalize cooling efficiency without aggressive chemical profiles.
Other notable competitive players reinforce the breadth of formulation strategies in the market. Bar's Leaks markets cooling-system cleaners that employ buffing-agent approaches to remove corrosion, sludge, and scale from radiators and cooling systems. BG Products, Inc. produces universal cooling-system cleaners designed to remove scale, oil, mineral deposits, rust, and residues from gasoline and diesel engine cooling systems without requiring neutralization steps. Jelmar LLC, through its CLR PRO line, offers a phosphate-free, ammonia-free, biodegradable formula utilizing lactic and gluconic acids for heavy-scale and rust removal within shorter service windows. Chemtex Speciality Limited supplies non-foaming inorganic blend formulations intended for use during system operation, targeting contaminated coolant, debris, rust, scale, and oily deposits. RX Marine International manufactures both acidic descaler-type and non-acidic cleaner options aimed at removing dirt, grease, scale, grime, solder, and broader contaminants from engine cooling systems. Callington's ROX Pro Radiator Flush concentrates are positioned for targeted removal of oil, grease, and contaminants across vehicle cooling systems.
The competitive narrative is increasingly defined not only by product performance but by how effectively companies integrate formulation advantages with distribution reach, service-channel training, and compliance-aware packaging. Detailed company profiles, product positioning matrices, and competitive benchmarking are provided within the full research to support benchmarking exercises, partnership evaluations, and market-entry planning.
Supply-Side Dynamics and Formulation Cost Exposure
Formulation economics in radiator flushing chemicals are closely tied to feedstock availability, commodity price trajectories, and regional input-cost differentials. Ethylene glycol, a primary upstream feedstock for many coolant-related formulations, experienced strong price behavior early in 2025, followed by weakening conditions and a rebound from year-end lows. For 2026, market indicators point to initial weakness and then range-bound stability in the vicinity of 4,000 to 4,400 RMB per ton amid ample supply conditions. This trajectory matters for manufacturers because cooling-system flush formulations often intersect with broader coolant and antifreeze value chains, where glycol-linked input dynamics can influence margin planning, price positioning, and inventory strategy.
Phosphoric acid pricing trends further illustrate the regional complexity of formulation input costs. As of March 2026, phosphoric acid prices stood at approximately 1.21 USD per kilogram in North America, up 0.8 percent; 1.37 USD per kilogram in Europe, down 0.7 percent; 1.05 USD per kilogram in Northeast Asia, down 1.9 percent; and 0.87 USD per kilogram in Africa, unchanged. These regional differentials can shape sourcing decisions, export-import competitiveness, and formulation design choices, particularly for acid-based chemistries where acid sourcing and purity profiles influence performance claims, cost structures, and regional price elasticity. The report integrates these raw-material dynamics into formulation-cost modeling and margin-scenario analysis, enabling procurement and product-management teams to map exposure across geographies and product lines.
Regulatory Context and Operational Compliance
Regulatory developments continue to shape how cooling-system maintenance products are positioned, communicated, and deployed within service workflows. U.S. EPA refrigerant management rules under 40 CFR Part 84 Subpart C introduced stricter limits on reclaimed refrigerants, with full effectiveness from January 1, 2026, including restrictions that no refrigerant may be sold as reclaimed if containing more than 15 percent of certain specified substances. While the radiator flushing chemicals market is not directly a refrigerant market, the broader regulatory direction reinforces heightened compliance expectations across automotive cooling-related service categories, including documentation practices, material sourcing integrity, and chemical handling standards.
At the regional level, the California Energy Code 2025 update, effective January 1, 2026, strengthens ventilation standards and expands electric vehicle charging requirements for new buildings. Although this policy does not directly regulate radiator flushing chemicals, it indirectly influences automotive and cooling-system maintenance practices by shaping service-environment standards, facility design expectations, and the broader context in which vehicle servicing and cooling-system care are delivered. These regulatory shifts are examined within the report as part of the operating environment affecting distribution channels, service-provider adoption, and long-term product positioning in regulated markets.
Antifreeze & Coolants Market
What the Market Research Delivers
This Worldwide Radiator Flushing Chemicals Market research is designed to convert market complexity into actionable strategic inputs. Rather than offering a static overview, the report provides a structured intelligence framework covering historical performance from 2020 through 2025, forward-looking forecasts for 2026-2032, and detailed segmentation analysis across product chemistry, vehicle type, and regional demand. The research integrates competitive profiling of core industry participants, formulation-level market positioning, and upstream raw-material monitoring to support both commercial planning and operational decision-making.
Key deliverables include revenue trajectory analysis covering 2020-2032, with explicit focus on the 2026-2032 forecast period and the 5.48 percent CAGR environment that shapes expansion planning. The segmentation component unpacks product chemistry dynamics across acid-based, alkaline-based, and solvent-based categories, alongside vehicle-type demand patterns spanning passenger cars, light commercial vehicles, and heavy commercial vehicles. Regional analysis maps demand intensity and growth positioning across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa region without oversimplification, enabling country-level prioritization and channel strategy development. Competitive analysis covers core manufacturers with profile depth on product architectures, formulation differentiation, and market presence, supporting benchmarking, competitive response planning, and partnership evaluation. Raw-material monitoring integrates ethylene glycol and phosphoric acid price dynamics into formulation cost exposure and margin planning, while the regulatory context section outlines operating-environment factors that affect compliance posture and service-channel adoption.
To ensure strategic usefulness, the report emphasizes operational interpretation over raw enumeration. Readers will find guidance on where formulation differentiation is most likely to create pricing power, which segments are expanding fastest relative to base markets, how regional cost structures influence competitive positioning, and how leading companies are aligning product portfolios with service-channel expectations. Core segment revenue splits, detailed country-level figures, and full company-level benchmarking tables are reserved for the complete dataset, ensuring that the final research serves as a decision-grade intelligence asset rather than a summary-level briefing.
Implications for 2026 Decision-Making
For organizations planning 2026 initiatives, the market's structural signals point to several strategic priorities. First, formulation performance narratives around corrosion control, deposit removal, system compatibility, and service-speed improvement remain central to competitive differentiation, especially as service providers and fleet operators increasingly weigh maintenance efficiency against total cost of ownership. Second, regional cost exposure and feedstock dynamics should be incorporated into pricing strategy, sourcing decisions, and inventory planning, with attention to regional phosphoric acid differentials and ethylene glycol supply conditions that can influence margin stability across product lines. Third, the balanced competitive concentration profile suggests that both established players and new entrants can influence share dynamics through targeted product positioning, distribution expansion, and service-channel relationship building. Fourth, regulatory and operating-environment developments should be tracked as part of go-to-market planning, particularly where service-environment standards and compliance expectations affect product adoption and channel execution.
The full research report translates these implications into a structured decision framework, enabling leadership teams to assess where to allocate commercial resources, which formulation and segment opportunities warrant deeper investment, and how competitive and supply-side dynamics are likely to shape margin and share outcomes over the 2026-2032 horizon. The complete market sizing dataset, segmentation detail, and proprietary competitive benchmarking are available through the full report, providing the depth required for definitive strategic planning and execution design.
Request access to the full Worldwide Radiator Flushing Chemicals Market research to obtain detailed segment revenues, regional breakdowns, competitive benchmarking matrices, and the complete 2026-2032 forecast model.
For detailed analysis of this topic, please visit the official page: Worldwide Radiator Flushing Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


