



PW Consulting: Worldwide Cold Ramming Paste Market Hits $487.04M in 2025, Projected 4.0% CAGR to 2032

Strategic Intelligence for the Next Cycle: Why the Worldwide Cold Ramming Paste Market Demands Precision in 2026
The global Cold Ramming Paste (CRP) market stands at a critical inflection point. As industrial operators navigate tightening environmental regulations, raw material volatility, and intensifying competition for process efficiency, the ability to anticipate market shifts is no longer optional—it is a strategic imperative. Our latest Worldwide Cold Ramming Paste Market research delivers a comprehensive, data-driven roadmap for enterprise decision-makers operating across aluminum smelting, ferroalloy production, silicon manufacturing, and heavy metallurgical furnace applications. This article outlines the structural dynamics, competitive realities, and forward-looking intelligence embedded in the report, demonstrating why precise market intelligence will define competitive advantage throughout the 2026–2032 forecast horizon.
Worldwide Cold Ramming Paste (CRP) Market
Macro Market Trajectory: From Recovery to Sustained Expansion
The CRP market has demonstrated remarkable resilience through a period of structural adjustment. Historical tracking from 2020 through 2025 reveals a market that expanded from approximately 385.4 million USD to 487.04 million USD, reflecting both demand recovery and supply-side modernization. The current baseline anchors at 487.04 million USD, with near-term projections indicating a measured climb to 495.06 million USD in 2026. Looking further ahead, the market is positioned to reach 640.9 million USD by 2032, translating to a compound annual growth rate of approximately 4.0 percent across the full forecast window.
These figures do more than chart volume—they signal a maturing ecosystem. The gradual upward trajectory reflects steady electrification of smelting operations, ongoing furnace maintenance cycles, and the gradual replacement of legacy sealing materials with engineered carbon-based formulations. Yet the true strategic value lies beneath the headline numbers. The forecast period exposes inflection zones where capacity shifts, regional rebalancing, and product substitution will alter procurement economics. Companies that treat CRP as a commoditized input risk margin erosion; those that align sourcing, formulation strategy, and supplier partnerships with forward-looking market intelligence will capture disproportionate operational stability.
Segmentation Dynamics: Type, Application, and Regional Realities
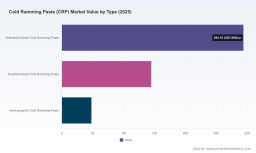
The market architecture is defined by distinct segmentation layers that collectively shape pricing behavior, supply chain design, and technology adoption. By product type, the landscape is anchored by anthracite-based formulations, complemented by graphite-based and semi-graphitic variants. Each category carries unique performance profiles, thermal stability boundaries, and cost structures that determine suitability across different furnace environments. By application, aluminum smelting cells dominate consumption, while blast furnaces and submerged arc furnaces represent specialized but strategically vital demand nodes. Regional distribution further complicates the picture, with Asia Pacific commanding the largest share of market activity, followed by Europe, the Middle East and Africa, North America, and Latin America.
Our analysis deliberately avoids superficial percentage breakdowns. Instead, the report maps how these segments interact under real-world operating conditions. Procurement teams must understand not just which segment is largest, but which segments exhibit the highest sensitivity to binder substitution, which applications face the most acute downtime risks during paste replacement cycles, and where regional supply constraints could trigger price dislocation. The interplay between type, application, and geography creates a multi-dimensional decision matrix that generic market summaries consistently fail to address.
Competitive Landscape: Consolidation, Specialization, and the Battlefield for Performance
The CRP market is neither fully fragmented nor monolithically concentrated. With a CR3 of 45.5 percent and a CR5 of 62.3 percent, the industry exhibits moderate-to-high concentration, yet significant room remains for specialized players to compete on formulation excellence, regional service coverage, and sustainability credentials. Our report profiles the core companies shaping this competitive arena, translating corporate positioning into actionable supplier evaluation criteria.
- Elkem ASA anchors its offering around ELSEAL cathode ramming paste variants designed to seal voids between prebaked cathode blocks and prevent electrolyte leakage in aluminum electrolysis cells. Its operational footprint extends to Brazil, reinforcing a global supply posture that balances technical consistency with regional availability.
- Maruti Electro Carbon leverages advanced manufacturing technology to deliver formulations with strong thermal stability and resistance in high-temperature environments, primarily serving aluminum and adjacent industrial sectors.
- Henan Rongxing Carbon Products Co., Ltd. has built a multi-decade portfolio across carbon metallurgical products, now including eco-friendly cold ramming paste variants for electrolytic cells and furnace lining applications.
- Bawtry Carbon Ltd focuses on aluminum smelting applications, emphasizing cathode and sidewall use cases through dedicated ramming paste series engineered for consistent sealing performance.
- Ningxia Hongyuan Huida Industrial Co., Ltd. produces environmentally conscious cold ramming paste series for cathode sealing and industrial furnace use, capitalizing on proximity to anthracite supply bases and a broader electrode paste ecosystem.
- Luoyang Longxin Furnace Co., Ltd. integrates cold ramming paste with carbon electrode paste and sealed electrode paste, serving metallurgical furnace operators that value integrated product compatibility.
- Shandong Robert New Material Co., Ltd. emphasizes thermal stability, density, and adhesion in its formulations, targeting aluminum electrolysis cells and blast furnace environments where performance consistency is non-negotiable.
- Wuhai Cowin Carbon Co., Ltd. positions cold ramming paste within a broader carbon and graphite product range, addressing ferroalloy, silicon, and calcium carbide industries that demand durable furnace lining materials.
- Ningxia Coalician Carbon & Coke Co., Ltd. supplies environmentally oriented furnace lining materials for silicon, ferroalloy, and calcium carbide electric furnaces, promoting graphitized, gap-free properties that support both new installations and repair linings.
- Carbone Savoie has advanced a fully eco-friendly cold ramming paste portfolio designed to reduce or eliminate PAH content, with formulations tested at industrial sites to validate performance under real smelting conditions.
The strategic implications are clear. Large, integrated suppliers compete on scale, global logistics, and certified consistency. Regional specialists compete on technical responsiveness, localized service, and formulation adaptation. Meanwhile, sustainability-driven entrants are reshaping procurement preferences by offering low-PAH or zero-PAH alternatives that align with corporate environmental mandates. Evaluating supplier risk, negotiating long-term agreements, and designing dual-sourcing strategies all require granular insight into how these players position themselves across type, application, and geography.
Market Forces Reshaping Procurement and Formulation Strategy
Several structural forces are redefining how operators source, specify, and manage cold ramming paste. First, raw material composition remains foundational. CRP is typically formulated using calcined anthracite, artificial graphite, and coal tar pitch or alternative binders. The precise balance of these feedstocks determines electrical resistivity, thermal stability, adhesion, and service life. Recent technical literature indicates that finished applications often target electrical resistivity below 65 Ω·mm²/m, with binder content typically spanning 55–70 percent asphalt or coal tar pitch alongside anthracene oil and functional additives. Procurement teams that understand these formulation levers can better assess supplier claims, anticipate price sensitivity to feedstock movements, and select products aligned with specific furnace operating parameters.
Second, environmental and occupational health regulations are accelerating formulation transformation. Conventional coal tar pitch binders can release polycyclic aromatic hydrocarbons during use, prompting the development of eco-friendly alternatives utilizing furan resin, lignin, or treated pitch with zero or reduced PAH content. Industry studies and manufacturer technical documentation have increasingly highlighted these shifts, while major smelting operators have begun implementing environment-friendly cold ramming mixtures designed to limit the liberation of hazardous volatile organic compounds such as benzo pyrene. The regulatory trajectory favors suppliers that can demonstrate measurable environmental performance without compromising sealing integrity, thermal stability, or installation practicality.
Third, application-specific performance requirements are becoming more rigorous. Aluminum smelting cells demand materials that withstand electrochemical environments, thermal cycling, and mechanical stress during maintenance windows. Blast furnaces and submerged arc furnaces impose distinct constraints related to high-temperature stability, lining adhesion, and compatibility with repair cycles. The market is therefore moving away from one-size-fits-all procurement toward specification-led sourcing, where paste selection is tied to cell design, operating temperature profiles, downtime tolerance, and environmental compliance targets.
What Our Report Delivers for 2026 Decision-Making
The Worldwide Cold Ramming Paste Market research is structured to convert complex market signals into executable strategy. The report moves beyond descriptive statistics to provide a practical intelligence toolkit for executives, procurement leaders, technical managers, and investors. Key deliverables include:
- A full historical reconstruction from 2020 through 2025, establishing baseline behavior, recovery patterns, and volatility triggers that inform baseline scenario planning for 2026 and beyond.
- A forward forecast extending through 2032, with annual revenue projections that enable capacity planning, budget modeling, and investment timing decisions across the forecast horizon.
- Segment-level analysis that clarifies how type, application, and regional demand interact, helping organizations identify the most resilient procurement categories and the segments most exposed to substitution or regulatory shifts.
- A competitive benchmarking framework that evaluates core suppliers on operational footprint, formulation emphasis, sustainability positioning, and service model, supporting vendor selection, negotiation strategy, and supply chain diversification.
- A market dynamics assessment that integrates raw material feedstock considerations, binder substitution trends, environmental compliance pressure, and application-specific performance requirements into a cohesive view of risk and opportunity.
- Strategic scenario mapping that highlights where capacity evolution, regional rebalancing, and product innovation are likely to alter pricing logic, availability, and total cost of ownership for end users.
Importantly, the report is designed to support decisions that must hold up under operational scrutiny. Procurement teams can use the intelligence to align contract structures with anticipated market movement. Technical leaders can map formulation characteristics to furnace performance requirements. Strategy and finance groups can stress-test capital allocation against realistic demand pathways. The objective is not to provide a static snapshot, but to equip organizations with a living framework for evaluating supplier options, anticipating regulatory impact, and positioning procurement strategy ahead of market inflection points.
Why This Intelligence Matters Now
The 2026 operating environment will reward precision. As environmental standards continue to tighten and furnace operators seek to reduce downtime, extend lining life, and maintain process stability, the selection of cold ramming paste becomes a strategic lever rather than a routine consumable purchase. Suppliers that invest in eco-friendly formulations, consistent thermal performance, and application-specific engineering are gaining prominence in procurement evaluations. At the same time, regional demand patterns, feedstock availability, and competitive concentration are creating new considerations for sourcing resilience.
Electrode Paste Market
Our research isolates these dynamics into a structured, decision-ready format. It enables organizations to move beyond intuition and generic market narratives, grounding their strategy in validated sizing, credible segmentation logic, and a realistic assessment of the competitive field. Whether the goal is to optimize supplier portfolios, evaluate entry opportunities, benchmark against industry peers, or prepare for regulatory-driven formulation shifts, the report provides the analytical foundation required to act with confidence.
Accessing the Full Strategic Picture
The macroeconomic trajectory, segmentation architecture, competitive profiles, and regulatory influences discussed here represent only the surface of what the report contains. Detailed segment sizing, regional demand structures, application-specific consumption patterns, supplier positioning matrices, and forward scenario analysis are all developed to support precise, evidence-based decision-making. For organizations that require complete visibility into how the worldwide cold ramming paste market will evolve through 2032, the full research publication offers the depth necessary to convert market intelligence into operational advantage.
The strategic window for aligning procurement, technical specification, and supplier strategy is open now. Enterprises that invest in comprehensive market intelligence today will be better positioned to manage cost structures, mitigate supply risk, and respond to the formulation and compliance shifts that will define the next phase of market growth.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Ramming Paste (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


