



PW Consulting: Mini Drama Market to Hit $10.85B in 2025, CAGR 13.93% Through 2032

Beyond the Scroll: Strategic Intelligence for the Global Mini Program Short Drama Market in 2026
The convergence of mobile-first consumption, fragmented attention economies, and hyper-localized monetization has crystallized into one of the most structurally resilient digital entertainment segments of the decade. Mini program short dramas are no longer an experimental distribution quirk. They are a standalone commercial architecture. As we move through 2026, platform operators, content producers, advertising buyers, and international expansion teams face a critical inflection point: the market has crossed threshold scale, regulatory frameworks have hardened, and the competitive center of gravity has shifted from domestic experimentation to globally coordinated production-distribution networks. Our newly released Worldwide Mini Program Short Drama Market study translates this complexity into a decision-ready intelligence layer. This preview outlines the analytical architecture, strategic relevance, and core operational dimensions of the full report, while intentionally preserving the granular segmentations and proprietary indices that demand direct access for executive deployment.
Worldwide Mini Program Short Drama Market
The Scale Trajectory and Why 2026 Is a Strategic Pivot Year
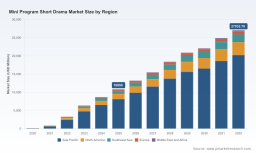
The historical arc of this segment tells a story of compressed adoption cycles followed by disciplined commercial maturation. From a niche content format in the early 2020s, the market accelerated rapidly through platform ecosystem integration, social-commerce payment wiring, and vertical-video consumption habits. By the base year of 2025, the overall market had reached a scale that signaled institutional commitment rather than speculative traffic play. Over the 2020 to 2025 historical window, revenue progression demonstrated the classic S-curve acceleration of a format finding its monetization equilibrium. The forecast period from 2026 through 2032 extends that trajectory, with compound annual growth projected at 13.93 percent, measured in USD millions.
For enterprise planning, the absolute figures matter less than the structural implications embedded in that growth rate. A double-digit CAGR sustained across a multi-year horizon indicates that demand is not being driven solely by platform subsidies or one-off viral cycles. Instead, it reflects durable shifts in how audiences discover, commit to, and pay for serialized micro-content. In 2026, the strategic question is no longer whether short dramas can scale. It is how organizations can anchor their content pipelines, monetization design, and regional entry sequences to a growth curve that compounds annually while regulatory and competitive conditions continuously reset the baseline. Our report maps the revenue path across the full forecast window so that leadership teams can stress-test investment horizons, content amortization schedules, and platform partnership timelines against a consistent growth assumption rather than fragmented quarterly snapshots.
Report Architecture: From Macro Signals to Operational Playbooks
A market research asset only earns executive airtime when it converts data into action. The Worldwide Mini Program Short Drama Market study is organized around four interlocking modules, each designed to support a distinct decision function inside the enterprise.
- Market sizing and forward projection. The report establishes a consistent top-down and bottom-up sizing framework across the historical and forecast periods. It aligns revenue definitions, currency conventions, and monetization scopes so that cross-functional teams can benchmark internal performance against a shared reference plane.
- Segmentation logic and consumption mapping. Rather than treating short dramas as a monolith, the study decomposes the market along content typologies, monetization architectures, and regional distribution footprints. This allows product, content acquisition, and commercial teams to isolate where margin profiles, audience retention curves, and price elasticity diverge.
- Competitive and ecosystem diagnosis. The report profiles the leading platforms, production entities, and cross-border distribution players shaping supply and demand. It connects corporate strategy, product launches, partnerships, and content pipeline moves to the broader market structure, highlighting where concentration creates pricing leverage and where fragmentation creates entry opportunities.
- Regulatory, compliance, and risk overlay. Because mini program short dramas sit at the intersection of content review, platform governance, and cross-border distribution, the study integrates the evolving compliance environment into strategic scenarios. This ensures that expansion roadmaps and production commitments are evaluated against realistic enforcement dynamics rather than idealized market access assumptions.
The full report deliberately avoids treating these modules as isolated chapters. Instead, it threads them together so that a content investment decision, for example, can be evaluated simultaneously against forecast demand, monetization fit, competitor response patterns, and regional compliance risk. Executive summaries, data exhibits, and scenario overlays are structured for direct insertion into board materials, content budgeting cycles, and platform negotiation frameworks.
Competitive Architecture: Platform Ecosystems, Production Networks, and Cross-Border Momentum
The competitive landscape is defined by three overlapping layers: super-app and social platform ecosystems, dedicated short-drama and streaming platforms, and a growing set of internationally oriented production and distribution players. The interaction among these layers determines who controls discovery, who captures transaction margin, and who owns the intellectual property pipeline.
At the ecosystem core, Tencent operates WeChat Mini Programs as a primary distribution channel for short dramas, integrating payment, social sharing, and content ecosystems into a single consumption and monetization loop. WeTV extends this architecture by co-producing and distributing exclusive short-form dramas for WeChat mini-programs and its own platform. China Literature complements the stack by supplying intellectual property suited for conversion into serialized vertical short dramas, reinforcing a production-to-distribution funnel inside the broader Tencent ecosystem. ByteDance, through Douyin and the Hongguo platform, delivers mini-program and short drama content while pushing international short drama initiatives, including Melolo in Southeast Asia and PikoShow in Japan. This combination of domestic feed logic and overseas platform experimentation illustrates how short dramas are increasingly treated as a transferable format rather than a purely local entertainment product.
Dedicated streaming and video platforms have moved aggressively into micro-serialized content as well. iQIYI has launched dedicated short-drama divisions and mini-program integrations targeting younger audiences, while Youku, under Alibaba, introduced a Mini-Drama Studio that enables creators to publish micro-episodes directly into its mini-program ecosystem with integrated analytics, monetization, and cross-platform promotion. Bilibili hosts short-format dramas and mini-program channels, including collaborations for co-production and distribution. Mango TV focuses on integrating short-form dramas within popular apps and WeChat and TikTok mini-program ecosystems, reinforcing a hybrid placement strategy. Kuaishou has historically provided short drama content via its platform and mini-program ecosystem, though recent industry adjustments have recalibrated its role in the micro-drama space.
Internet Micro Short Drama Production Market
Beyond the domestic platform core, a parallel set of international-facing players has emerged. Mega Matrix operates a short-video streaming platform and produces short dramas, partnering for joint development and global distribution. Snail has developed and produced short dramas with AI and immersive elements for global distribution, including partnerships for mini-program style content. ReelShort and DramaBox represent another strategically important cohort: both have built significant overseas in-app revenue profiles by leveraging Chinese production models for global mini-program style vertical dramas. Their ascent underscores a broader structural reality. A substantial share of the top grossing short drama apps internationally now traces its production, format design, and monetization logic back to mini-program short drama ecosystems.
Recent corporate activity makes these competitive linkages explicit. In early 2025, WeTV announced a partnership with Lionsgate to co-produce and distribute exclusive short-form dramas for the Chinese mini-program market, with first-window streaming on WeChat mini-programs and WeTV. Later in the year, Youku expanded its creator-facing infrastructure through the launch of Mini-Drama Studio, enabling direct publishing of micro-episodes into its mini-program ecosystem with embedded analytics and monetization tools. ByteDance advanced its international footprint by launching a free-model short-drama platform targeting the Southeast Asian market as part of its broader globalization push. Separately, an MOU between Snail and Mega Matrix outlined joint development, production, and global distribution of a slate of short dramas with AI-enabled personalization and immersive storytelling elements. These moves are not isolated product launches. They are positioning actions that redefine who controls content supply, discovery pathways, and cross-border monetization in the next phase of market growth.
Market Concentration and the Strategic Meaning of a Fragmented Top
Concentration metrics provide an important lens for evaluating bargaining power, platform dependence, and content monetization risk. In this market, the top three players account for approximately 32.5 percent of revenue, while the top five reach roughly 41.2 percent. These figures describe a landscape that is meaningfully concentrated at the leadership tier yet still wide open across the long tail. For enterprises, that combination creates two simultaneous conditions. First, the leading platforms and apps command enough scale to influence payment routing, promotion placement, and content review expectations. Second, the remaining share is distributed across a broad field of regional apps, niche content providers, and international-facing services, which means differentiation, format innovation, and targeted regional entry can still produce disproportionate returns.
Concentration also interacts with monetization design. In-app purchases and pay-per-episode mechanics continue to anchor revenue for a large portion of the market, reflecting an audience willingness to transact incrementally for serialized emotional payoff. Subscription models and advertising-based video on demand capture different audience segments and different engagement rhythms, and each model carries distinct content cadence, retention, and pricing implications. The strategic challenge for 2026 is not selecting a single monetization model in isolation. It is aligning content production cycles, episode length, cliffhanger design, and platform promotion economics so that the chosen revenue architecture matches the consumption behavior of the target audience in a specific distribution environment.
Regulatory Dynamics and the Compliance Premium
Content governance has become a structural force rather than a peripheral risk. Beginning in mid-2024, major platforms implemented filing and review systems for micro short dramas. WeChat introduced cost allocation reporting requirements for productions below certain thresholds, while Douyin and Kuaishou mandated filing numbers as part of broader compliance enforcement. By 2025, enforcement had moved from procedural compliance to active content removal, with platforms purging non-compliant titles as part of ongoing review cycles. In parallel, some participants adjusted their business models away from less compliant or lower-quality short play mini-program offerings, reflecting a market-wide shift toward more controlled, higher-quality content models.
For strategic planning, this environment creates what can be described as a compliance premium. Titles, formats, and production pipelines that are designed with filing requirements, cost transparency, and review readiness in mind gain faster distribution confidence and lower operational friction. Conversely, content strategies that ignore review mechanics or depend on borderline content risk disruption, removal, and reallocation of marketing spend. The full report integrates these regulatory dynamics into market behavior scenarios so that expansion plans, production commitments, and platform partnerships can be evaluated against realistic compliance timelines and enforcement intensity.
Consumer Scale, Content Archetypes, and the Globalization Signal
Demand-side scale provides the foundation for the market's monetization momentum. By 2025, China's micro-drama audience had grown to over 660 million regular viewers, with more than half the population engaging in short drama consumption through mini-programs and apps. This audience breadth transforms short dramas from a niche format into a mainstream mobile entertainment habit, which in turn supports the revenue architecture and platform investment cycles observed across the market.
Content preferences further shape commercial strategy. Romance and marriage narratives command the largest share of content-driven revenue, followed by revenge and urban drama, fantasy and historical titles, and thriller and other categories. These segments are not interchangeable from a production standpoint. They differ in episode design, emotional pacing, audience retention triggers, and regional portability. A format that performs strongly in one content archetype may not translate cleanly into another without adjustments to casting, pacing, cliffhanger structure, and cultural references. The study decomposes these content typologies so that content acquisition and production teams can map audience behavior to specific format choices rather than relying on generalized category assumptions.
The globalization signal is equally important. As of early 2025, more than 40 of the top 50 global short drama apps by in-app revenue were developed by Chinese companies, together accounting for the overwhelming majority of overseas market revenue. This concentration of international success within a relatively small group of producers and platforms indicates that the mini-program short drama playbook has become a globally exportable commercial model. The implication for 2026 is clear: international expansion is no longer about simply localizing titles. It is about adapting a proven production-to-monetization system, including episode economics, transaction prompting, platform distribution, and audience retention design, to regional regulations, payment environments, and competitive dynamics.
Why This Study Matters for 2026 Decision-Making
Executive teams entering 2026 need more than a market snapshot. They need a coordinated view of growth trajectory, monetization logic, competitive positioning, content segmentation, and regulatory exposure. The Worldwide Mini Program Short Drama Market study is built for that purpose. It gives content strategists a forward revenue frame, gives platform and partnership teams a competitive map that connects ecosystem moves to structural advantage, gives international expansion teams a realistic view of where Chinese-origin short drama models have already established global revenue dominance, and gives risk and compliance functions a structured view of review enforcement and content governance trends.
The research is designed to support decisions that unfold across multiple time horizons. Near-term, it helps prioritize which content archetypes, monetization paths, and distribution channels deserve budget allocation. Mid-term, it supports producer and platform partnership choices by clarifying where concentration creates leverage and where fragmentation creates room for differentiated entry. Longer-term, it provides a forecast backbone for capacity planning, IP acquisition strategy, and cross-border rollout sequencing.
Accessing the Full Intelligence Package
The preview above establishes the analytical direction and strategic relevance of the study, but the decision-grade detail lives in the full report. The complete package contains the segmented market sizing and forecast exhibits, the full competitive profiles and recent development chronology, the content-type and monetization breakdowns, the regional distribution architecture, and the scenario overlays that connect regulatory and consumer dynamics to commercial planning. These components are structured for direct use in investment committees, content roadmapping sessions, platform negotiation preparation, and international expansion reviews.
For teams operating in a market growing at a sustained double-digit pace, the cost of relying on fragmented public information is rising. The full report converts that risk into a structured intelligence advantage. Access the complete Worldwide Mini Program Short Drama Market study through the source page to retrieve the detailed data exhibits, segmentation logic, competitive profiles, and scenario frameworks needed to align your 2026 strategy with the market's actual structure rather than its surface momentum.
For detailed analysis of this topic, please visit the official page: Worldwide Mini Program Short Drama Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


