



PW Consulting: Global Negative Ion Cyclotron Market Hits $425.5M in 2025, 6.15% CAGR to 2032

Strategic Intelligence in the Global Negative Ion Cyclotron Market: Navigating the 2026–2032 Expansion
The worldwide negative ion cyclotron market stands at a critical inflection point. As diagnostic imaging demand strengthens and therapeutic radioisotope production accelerates, the equipment landscape is evolving from a niche manufacturing segment into a strategically vital healthcare infrastructure market. This article introduces PW Consulting’s latest Worldwide Negative Ion Cyclotron Market research, a comprehensive analysis designed to equip executives, procurement leaders, and investment committees with the decision-grade intelligence required for 2026 planning and beyond.
Built on a rigorous quantitative foundation and filtered through operational, regulatory, and competitive lenses, this study does more than project top-line figures. It maps the structural shifts reshaping procurement cycles, technology adoption, supply chain dependencies, and competitive positioning. The following overview outlines the analytical architecture of the report, demonstrates how the data translates into strategic action, and clarifies why this research has become an essential reference for organizations operating at the intersection of medical technology, radiopharmaceutical manufacturing, and capital equipment investment.
Market Trajectory and Structural Growth Dynamics
The historical record from 2020 through 2025 reflects a market that has consistently absorbed institutional demand, capacity upgrades, and geographic expansion. Revenue has climbed steadily from 312.45 million USD in 2020 to 425.5 million USD in 2025, demonstrating resilience across product cycles and regional procurement patterns. Looking forward, the forecast period from 2026 to 2032 projects sustained momentum, with the market expected to reach 454.05 million USD in 2026 and advance to 646.16 million USD by 2032. This trajectory corresponds to a compound annual growth rate of 6.15 percent, a rate that signals more than incremental expansion; it reflects a structural realignment in how healthcare systems and research organizations approach isotope production, beamline infrastructure, and on-site radiopharmacy capabilities.
Worldwide Negative Ion Cyclotron Market
Several underlying forces are reinforcing this trajectory. The expansion of positron emission tomography networks continues to drive demand for reliable, centrally located or decentralized isotope production. At the same time, the growing clinical adoption of theranostic approaches is pushing buyers to evaluate equipment flexibility, beam performance, and multi-isotope compatibility with greater scrutiny. Organizations that understand not just the size of the opportunity but the timing, sequencing, and risk profile of adoption will be best positioned to allocate capital efficiently and secure competitive advantage in procurement, installation planning, and service partnerships.
This research does not simply chart a growth curve. It decomposes the drivers behind the curve, evaluates the durability of demand signals, and identifies where market participants are likely to encounter capacity constraints, validation delays, or competitive recompetition. The result is a planning framework that supports scenario-based budgeting, site readiness assessment, and long-range capacity strategy.
Energy-Level Segmentation and the Strategic Meaning of Beam Architecture
Negative ion cyclotrons are not interchangeable assets. The market divides into three energy-level categories, each serving distinct operational requirements and buyer priorities. Low energy systems below 20 MeV account for the largest revenue share among the three categories, reflecting their broad applicability in routine diagnostic radioisotope production and their alignment with the installation requirements of many hospital-based and regional radiopharmacy sites. Medium energy systems in the 20 to 70 MeV range represent a substantial and strategically important segment, typically selected where facilities require broader isotope portfolios, higher throughput, or preparation for advanced therapeutic workflows. High energy systems above 70 MeV form the most specialized tier, with revenue concentration in applications that demand the highest acceleration performance for theranostic isotope production and complex research programs.
From a strategic standpoint, these energy tiers are not merely technical specifications; they are proxy indicators for buyer maturity, facility readiness, regulatory exposure, and commercialization ambition. Lower-energy deployments often align with faster installation timelines and narrower operational scopes, while higher-energy systems typically entail more demanding infrastructure, stricter export and licensing scrutiny, and longer validation pathways. Decision-makers evaluating capital allocation, site selection, or technology roadmaps must therefore treat energy level as a strategic variable, not just a procurement parameter.
The report examines how these energy categories interact with buyer behavior, installation economics, and long-term service requirements. It explores where demand is most responsive to capacity expansion, where competitors are likely to defend share through product specialization, and how infrastructure requirements shape total cost of ownership. By isolating these dynamics, the analysis enables organizations to align product strategy with realistic adoption curves rather than aspirational forecasts.
Regional Demand Patterns and Deployment Geography
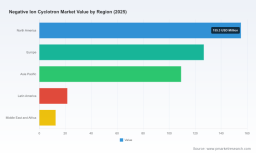
Demand for negative ion cyclotrons is distributed across geographies with distinct maturity profiles, procurement rhythms, and infrastructure prerequisites. North America remains a leading market in absolute terms, reflecting established diagnostic imaging networks, substantial research footprints, and a relatively mature ecosystem for radioisotope supply and clinical adoption. Europe represents a similarly significant demand base, characterized by strong institutional procurement frameworks, rigorous device and safety standards, and an active pipeline of facility upgrades and new installations. Asia Pacific contributes a substantial share of market activity, supported by expanding imaging capacity, growing regional radiopharmaceutical capabilities, and increasing investment in medical infrastructure. Latin America and the Middle East and Africa together form a smaller but strategically relevant demand footprint, often shaped by selective flagship installations, phased capacity building, and partnerships that bridge technology access with local operational readiness.
Regional analysis in this study goes beyond share comparisons. It evaluates procurement timing, the influence of local regulatory and safety frameworks, the role of distribution and service networks, and the practical implications of deploying complex beamline equipment in environments with varying levels of technical support maturity. For organizations considering market entry, partnership development, or site-specific installation strategy, these regional dynamics determine not only where demand exists, but where it can be converted into executable projects with acceptable risk and timeline certainty.
The report also addresses how export controls and dual-use considerations shape the flow of high-energy systems across borders. In certain cases, systems above specific energy thresholds are subject to licensing requirements that affect sales cycles, dealer networks, and cross-border project execution. This is a critical variable for any organization planning international expansion or multi-country procurement programs, and it is analyzed here with the operational specificity required for realistic planning.
Application Mix and the Shifting Value of Isotope Production
Negative ion cyclotron revenue is anchored by a clear hierarchy of applications. Diagnostic radioisotope production remains the dominant demand driver, reflecting the continued centrality of PET and related imaging workflows in clinical practice and the corresponding need for dependable, on-site or regionally distributed isotope supply. Radiation and proton therapy applications represent a significant secondary tier, tied to facilities where beam infrastructure supports therapeutic programs and where equipment selection must accommodate both production and clinical delivery requirements. Industrial and scientific research constitutes a smaller but meaningful application pool, often linked to specialized isotope needs, materials analysis, and institutional research programs that value beam stability and multi-purpose capability.
Application mix is strategically important because it influences equipment configuration, validation requirements, service intensity, and long-term revenue durability. A facility optimized for diagnostic isotope output may prioritize different performance characteristics than one preparing for therapeutic workflows or research diversification. Buyers increasingly assess not only immediate production needs but also the optionality of the installed base, especially as radiopharmaceutical pipelines evolve and clinical programs expand.
This research evaluates how application demand interacts with product design, procurement decision-making, and competitive positioning. It identifies where application-driven purchasing is most concentrated, where expansion is likely to be incremental versus step-change, and how manufacturers and operators can align product portfolios with the most resilient demand pools. The objective is to help organizations move from generic market sizing to application-aware investment strategy.
Competitive Landscape: Differentiated Positioning Among Leading Suppliers
The market is shaped by a concentrated group of established manufacturers, each pursuing distinct product strategies, geographic reach, and application focus. Ion Beam Applications SA (IBA), headquartered in Louvain-la-Neuve, Belgium, provides the Cyclone series of negative ion cyclotrons, including models such as Cyclone 18+, Cyclone 30, Cyclone KIUBE, and Cyclone 70. These systems support H- ion acceleration up to 70 MeV and are positioned across PET and therapeutic radioisotope production. Recent activity underscores IBA’s continued footprint in both regional deployment and higher-energy theranostic programs, including the delivery of a Cyclone KIUBE system to a hospital facility in Australia and a major contract for a Cyclone 70 high-energy negative ion cyclotron for theranostic isotope production in the United States.
Advanced Cyclotron Systems Inc. (ACSI), based in Richmond, British Columbia, Canada, manufactures the TR series, including TR-19, TR-24, and TR-30, which accelerate H- ions for multi-isotope production in PET imaging. ACSI’s recent installation activity, including the delivery of a TR-24 system to a new PET facility in Poland, highlights the ongoing relevance of mid-tier systems in expanding imaging networks and regional radiopharmacy development.
GE Healthcare, headquartered in Chicago, Illinois, offers the PETtrace 800 and 880 negative ion cyclotrons designed for on-site production of PET isotopes through H- acceleration. Its presence reflects the intersection of molecular imaging strategy and isotope supply reliability, particularly for health systems seeking integrated diagnostic workflows.
Sumitomo Heavy Industries, Ltd., based in Shinagawa, Tokyo, supplies HM-18 and HM-30 negative ion cyclotrons for clinical PET radionuclide production. Its product focus aligns with clinical isotope manufacturing requirements and supports buyers seeking established hardware platforms with defined operating envelopes.
TeamBest Global Companies, Inc., located in Sugar Land, Texas, produces Best Cyclotron models such as the 18p and 14p, using negative hydrogen ion acceleration for radioisotope manufacturing. This offering reinforces the competitive breadth of the market and the continued relevance of specialized configurations tailored to specific production goals.
The research does not treat these players as a static roster. It evaluates how product differentiation, service capability, installation track record, and regulatory readiness influence competitive outcomes. It also examines concentration dynamics, including the extent to which leading firms command disproportionate share and how that concentration affects pricing, vendor selection, and the bargaining position of buyers. Understanding this landscape is essential for organizations planning procurement, partnership, or market-entry strategies in a market where trust, compliance, and long-term support often matter as much as headline specifications.
Regulatory, Infrastructure, and Operational Constraints as Strategic Variables
Capital equipment in this sector does not succeed on performance claims alone. It must operate within a framework of safety standards, device classification requirements, infrastructure limitations, and export controls that collectively shape project feasibility. Medical cyclotrons must comply with IAEA Safety Standards Series No. SSG-49 for radiation protection and facility design, creating a baseline expectation for site planning, shielding, and operational governance. In parallel, cyclotrons used for isotope production are classified as Class IIb medical devices under the EU Medical Device Regulation 2017/745, which requires ISO 13485 certification and introduces quality-management discipline into product development, manufacturing, and post-market support.
On the technical side, negative H- ion sources in commercial cyclotrons are generally limited to beam currents of 1 to 5 mA because of space charge effects and extraction challenges. This constraint matters because it influences throughput expectations, isotope production planning, and the practical boundaries of system performance. In addition, cyclotron facilities require RF power systems in the range of 100 to 200 kW and ultra-high vacuum conditions below 10^-8 mbar to maintain stable negative ion acceleration. These requirements have direct implications for site design, utilities, maintenance planning, and total cost of ownership.
The study integrates these constraints into market analysis rather than treating them as background notes. It evaluates how regulatory compliance timelines affect procurement cycles, how infrastructure readiness influences installation sequencing, and how technical limits shape competitive differentiation. For executives, this means the report provides not only market size and growth estimates, but also an operational reality check on what it takes to convert demand into installed capacity.
Report Scope: What Decision-Makers Will Find Inside
This research is structured to support practical decision-making across strategy, procurement, investment, and operational planning. It combines macro-level market sizing with segmentation analysis, competitive profiling, and contextual assessment of the regulatory and infrastructure environment that governs deployment. Rather than functioning as a static data table, the report is designed as an actionable intelligence package that helps organizations answer questions such as:
Medical Cyclotron Market
- Where is demand most likely to convert into installed capacity over the forecast horizon, and under what conditions
- How do energy-level requirements shape buyer selection, site preparation, and service expectations
- Which application pools provide the most durable revenue opportunities for manufacturers and the most strategic value for operators
- How do regional procurement patterns differ in timing, risk, and support requirements
- What competitive advantages are emerging from product specialization, installation track record, and compliance readiness
- How do export controls, safety standards, and device regulation influence market access and project execution
The report also provides context for evaluating total cost of ownership, including the implications of RF power requirements, vacuum system performance, beam current limitations, and post-installation support. By linking market structure to operational reality, the analysis enables more disciplined capital planning and more credible go-to-market or procurement strategies.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle is not simply another forecast update. It is the point at which organizations must reconcile rising demand signals with practical limits on installation capacity, regulatory readiness, service scalability, and competitive recompetition. In that environment, decision-makers need intelligence that connects market growth to implementation risk, product differentiation to buyer priorities, and regional opportunity to operational feasibility.
PW Consulting’s Worldwide Negative Ion Cyclotron Market research is built for that purpose. It provides the analytical depth required to support scenario planning, capacity strategy, vendor evaluation, and investment prioritization. It also intentionally preserves the granularity of segmentation detail, regional deployment logic, and competitive benchmarking within the full study, so that organizations can access the specific figures and comparative frameworks needed for internal modeling and executive review.
The strategic message is straightforward: the market is expanding at a measured but meaningful pace, the demand core is anchored in diagnostic isotope production, competitive differentiation is increasingly tied to compliance, installation capability, and service reliability, and the practical constraints of beam performance and infrastructure are shaping what can realistically be deployed and when. Organizations that understand these dynamics early will be better positioned to secure supply partnerships, plan site readiness, and align product or procurement strategy with durable demand rather than short-term momentum.
Next Steps for Stakeholders
For executives, procurement leaders, investors, and technology strategists evaluating the negative ion cyclotron sector, this research offers a structured pathway from high-level market context to decision-ready insight. The complete study delivers the detailed segmentation data, competitive comparisons, regional deployment analysis, and operational constraint mapping required to translate strategic intent into executable plans.
Readers seeking the full range of figures, segmentation breakdowns, and company-specific strategic assessments are encouraged to access the complete report through PW Consulting’s official market research portal. There, the full intelligence architecture is available to support internal validation, procurement benchmarking, and long-range planning with the precision required for high-stakes capital and capacity decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Negative Ion Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


