



Trading to $2.3B by 2032: PW Consulting Notes 6.92% CAGR in Global Topical Dispenser Market

Strategic Intelligence for the Global Topical Dispenser Market: Navigating Growth and Precision in 2026 and Beyond
The worldwide topical dispenser market stands at a critical inflection point. As healthcare systems increasingly prioritize precise drug delivery, infection control, and patient-centric formulation design, the mechanisms that govern how creams, gels, lotions, and topical adhesives reach their intended site of action have evolved from simple packaging components into indispensable clinical enablers. For executives, procurement leaders, and R&D strategists operating across pharmaceutical, dermatology, cosmetics, and personal care value chains, understanding the structural forces shaping this segment is no longer optional. It is a core determinant of competitive positioning, supply chain resilience, and regulatory readiness through the end of the decade.
This article outlines the strategic rationale behind PW Consulting’s latest worldwide topical dispenser market study, a comprehensive intelligence framework designed specifically to equip decision-makers with actionable clarity for 2026 planning. Rather than offering static snapshots, the research maps the interplay of demand fragmentation, manufacturing precision, regulatory scrutiny, and competitive consolidation that will define the next seven years of market evolution.
The Macro Trajectory: Mapping a Seven-Year Expansion Cycle
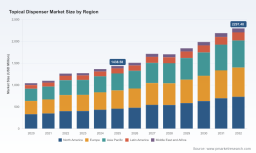
Over the historical window from 2020 through 2025, the topical dispenser market demonstrated consistent upward momentum, reflecting cumulative shifts in compounding pharmacy workflows, hospital formulary modernization, and consumer-facing skincare innovation. That trajectory sets the stage for the forecast period spanning 2026 to 2032, during which the global market is projected to expand at a compound annual growth rate of 6.92 percent. By the close of the forecast horizon, total revenue is expected to surpass the two-billion-dollar threshold in USD terms, underscoring a market that has matured beyond niche clinical applications into a broadly integrated distribution ecosystem.
For strategic planners, the significance of these headline figures lies not in the numbers themselves but in what they reveal about underlying demand elasticity. Growth is being distributed across multiple innovation vectors: the continued adoption of airless pump architectures that protect sensitive active ingredients from oxidation and microbial contamination, the steady utilization of metered-dose tubes and click-dosing mechanisms that standardize compound preparation, and the expanding role of dual-chamber systems that maintain ingredient separation until point-of-use. Jar dispensers, droppers, and ancillary accessories continue to serve specialized workflows, but the center of gravity is clearly shifting toward dispensing technologies that deliver repeatable, dose-controlled output across varied base formulations.
The forecast window also exposes the market’s structural sensitivity to broader healthcare and industrial trends. Supply chain localization efforts, evolving pharmacopeial expectations for dose uniformity, and the growing intersection of human and veterinary compounding are all reshaping procurement calendars, manufacturing scale-up timelines, and regional distribution footprints. A rigorously segmented view of these dynamics is essential for distinguishing transient demand spikes from durable shifts in application mix, and for forecasting capital allocation with greater precision.
From Volume to Value: Why Strategic Precision Matters in 2026
Leadership teams operating in this space are increasingly asked to reconcile two competing imperatives: capturing volume growth while defending margin integrity through higher-value dispensing architectures. The transition is not merely technological; it is commercial, regulatory, and operational. As formulators and compounding organizations demand greater consistency in active-ingredient delivery, the economic premium associated with precision dispensing mechanisms becomes more pronounced. Simultaneously, the cost of non-compliance—whether through dose variability, inadequate sterile-barrier performance, or misalignment with quality management expectations—continues to rise.
A research framework built for 2026 decision-making must therefore move beyond aggregate sizing. It needs to isolate the operational drivers that determine which dispensing platforms gain traction in institutional versus decentralized compounding environments, how reimbursement structures influence formulary inclusion of topical agents paired with specific applicators, and which geographic corridors are experiencing the fastest reconfiguration of supply and demand balances. The strategic value lies in mapping the trigger points where product design, regulatory classification, and procurement economics intersect.
In practice, this means equipping regional managers with the context needed to evaluate whether a shift toward metered-dose or airless architectures aligns with local clinical workflows and sterilization capacity, helping product developers anticipate which formulation characteristics will require dispenser redesign, and enabling sourcing leaders to stress-test supplier qualification pipelines against evolving quality-system expectations. Without a clear view of these intersections, organizations risk over-indexing on legacy container strategies or underinvesting in the precision components that will define competitive differentiation as the market matures.
Inside the Research: Operational Intelligence for Cross-Functional Teams
The newly released PW Consulting study is structured to convert macro trends into practical decision support across multiple functional domains. Rather than functioning as a single-volume market summary, the report is designed as an operational intelligence toolkit that can be deployed by commercial, R&D, regulatory, and supply chain teams in parallel.
At its core, the research provides a detailed breakdown of the global market across its primary segmentation axes, mapping revenue distribution by geographic corridor and by dispensing technology category. The regional view captures divergent adoption patterns, procurement maturity, and the varying intensity of institutional demand, while the technology-level analysis isolates the relative positioning of airless pump dispensers, metered-dose tubes, dual-chamber systems, jar dispensers, and dropper-based accessories. This dual-lens approach enables readers to cross-reference where specific dispensing formats are gaining structural advantage and how regional demand profiles influence product-mix planning.
A parallel segmentation by end-use application situates the compounding and healthcare context within the broader commercial landscape. Pharmaceutical and dermatology applications, cosmetics and skincare workflows, and personal care utilization all draw on the same underlying dispensing infrastructure, yet they impose distinct requirements on dose accuracy, barrier performance, manufacturability, and end-user experience. Clarifying how these segments interact with the overall revenue base allows organizations to anticipate cross-segment demand spillover, identify adjacent market entry opportunities, and calibrate investment priorities with a realistic view of where growth is being generated and where it is merely ornamental.
The study also integrates a dedicated competitive landscape analysis, profiling organizations that are actively shaping product architecture, manufacturing capability, and go-to-market positioning. These profiles are paired with a chronological account of recent corporate developments, including new product introductions and regulatory milestones that signal shifts in the competitive baseline. For strategists evaluating partnership opportunities, supplier transitions, or competitive response scenarios, this timeline provides the context needed to distinguish one-off announcements from sustained positioning moves.
To support scenario planning, the research addresses the regulatory and reimbursement environment with applied granularity. Coverage spans device classification expectations for topical applicators and skin adhesives, quality management standards relevant to design and production, and the practical implications of dose-uniformity evaluations for dispenser selection in compounding workflows. Reimbursement considerations are also mapped, particularly where topical agents and associated applicators intersect with coverage policies that affect downstream demand. These elements are presented as decision variables rather than background noise, enabling teams to factor compliance and coverage risk directly into product and market strategy.
Finally, the report is built to support executive-level synthesis. It provides the connective tissue needed to translate data points into actionable conclusions: where concentration dynamics suggest platform-level competition, where regional variance indicates the need for localized supply strategies, and where technological differentiation is likely to become a determinant of customer retention and pricing power.
Competitive Architecture: Incumbents, Specialists, and the Push Toward Precision Manufacturing
The competitive landscape in the topical dispenser market is defined by a blend of established packaging and dispensing specialists, medical-device-oriented manufacturers, and niche players concentrated on compounding and clinical workflow optimization. This mix creates a market structure in which scale advantages in component supply and global distribution coexist with highly differentiated clinical engineering capabilities. Understanding how these tiers interact is essential for anticipating pricing behavior, partnership structures, and technology adoption cycles.
Among the profiled organizations, several illustrate the market’s direction of travel. Companies developing metered dosing applicators for creams, gels, and lotions are increasingly emphasizing dose uniformity and workflow integration for both human and veterinary compounding pharmacy applications. The focus on pharmacist and patient experience signals a broader shift from purely mechanical dispensing toward solutions that reduce preparation variability and streamline operational throughput. In parallel, suppliers of airless and semi-solid dispensing systems continue to highlight product protection, hygiene, and metered output as core value propositions for pharmaceutical skin treatments, reinforcing the clinical premium attached to containers that preserve formulation integrity.
The competitive field also includes providers of click-dosing and metered pump dispensers designed for both non-sterile and sterile compounded preparations, alongside manufacturers supplying airless metered dose pumps and lidded applicators tailored to compounding workflows. These product lines reflect the market’s sensitivity to dosing accuracy across different cream bases and the growing expectation that dispensing hardware should be evaluated for consistency rather than convenience alone. Supporting this ecosystem are porous plastic and fiber component manufacturers that engineer drug delivery reservoirs and applicator components for medical device integration, as well as organizations developing precision healthcare dispensing solutions for dermal applications and controlled-dosing devices for topical gels and creams.
Dispenser Pump Market
Contract manufacturing capability further shapes the landscape. FDA-registered, ISO 13485-certified manufacturers of injection-molded pharmaceutical and medical applicators provide the production discipline required to support Class I and Class II device supply chains. Their presence underscores the market’s dependence on quality-system maturity as a competitive differentiator, particularly as demand for precision applicators grows across regulated healthcare channels.
Worldwide Topical Dispenser Market
Recent corporate activity reinforces these structural themes. A notable product launch introduced a metered-dose topical applicator optimized for in-container automated compounding, with design choices explicitly oriented toward improving pharmacist workflow and patient experience. In parallel, regulatory activity surrounding topical skin adhesives—classified as Class II medical devices requiring premarket notification—illustrates the broader device-ecosystem context within which topical dispensers and applicators operate. These developments are more than isolated milestones; they indicate how product architecture, regulatory expectations, and workflow efficiency are converging into a new competitive baseline.
Concentration dynamics within the market suggest a landscape that is neither fully fragmented nor tightly consolidated. A meaningful share of revenue is captured by a defined tier of leading participants, while substantial remaining share is distributed across specialists and regional suppliers. For strategy teams, this implies that competitive advantage will increasingly depend on the ability to combine component reliability, dosing precision, and workflow compatibility, rather than competing on container cost alone.
Regulatory and Reimbursement Fault Lines as Strategic Variables
As the topical dispenser market matures, regulatory and reimbursement variables are moving from peripheral considerations to central strategic inputs. Device classification frameworks, quality management requirements, and dose-uniformity expectations directly influence which dispensing architectures can scale efficiently and which require additional validation investment. At the same time, reimbursement treatment for certain topical agents and their associated application methods can shape formulary decisions, compounding volume, and downstream demand for specific applicator types.
For manufacturers and distributors, the implication is clear: product strategy cannot be decoupled from compliance strategy. ISO-aligned quality systems, documentation discipline, and design controls are increasingly treated as market-access prerequisites rather than operational overhead. Similarly, understanding dose-accuracy performance across formulation types is becoming relevant not only for clinical outcomes but also for procurement justification in regulated environments. The market’s most agile participants are those that integrate regulatory foresight into product roadmaps early, allowing them to align dispensing capabilities with evolving expectations before compliance gaps become market barriers.
2026 Positioning: How to Use This Intelligence
The strategic utility of this research lies in its ability to convert a rapidly evolving market into a structured set of decision levers. For commercial leaders, the segmentation views clarify where demand is concentrated and where regional variance calls for differentiated go-to-market models. For R&D and product management teams, the technology- and application-level analysis identifies the performance attributes that will command premium positioning as compounding and clinical workflows demand greater consistency. For supply chain and procurement functions, the competitive profiles and manufacturing context support more disciplined supplier evaluation and risk allocation. For regulatory and market-access teams, the coverage of device classification, quality standards, and reimbursement dynamics provides the context needed to anticipate friction points before they affect launch timing or adoption.
To move from overview to operational advantage, organizations need the full analytical layer behind these themes: the detailed segmentation splits, the regional revenue architecture, the application-level demand mapping, and the competitive-event timeline that together form the study’s core intelligence spine. These components transform strategic narrative into precise planning inputs, allowing leadership teams to size opportunity, calibrate investment, and stress-test assumptions with confidence.
Access the Full Strategic Framework
The complete PW Consulting Worldwide Topical Dispenser Market study provides the detailed data architecture and cross-segment analysis required to translate market direction into executable strategy. For decision-makers responsible for portfolio planning, supply chain positioning, competitive benchmarking, and regulatory readiness through 2032, the full report delivers the granularity needed to move from observation to action. Readers seeking the precise segmentation values, regional revenue distributions, application-level demand breakdowns, and extended competitive intelligence should consult the full research release, where the underlying dataset and analyst commentary are available in complete form.
For detailed analysis of this topic, please visit the official page: Worldwide Topical Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


