



PW Consulting: FPSO Market to Hit $21.1B by 2032, Powered by 7.34% CAGR and Deepwater Growth

Strategic Imperatives in the Global FPSO Market: Navigating Growth Through 2032
The global offshore energy landscape is undergoing a structural transformation, driven by the interplay of deepwater resource development, evolving service delivery models, and shifting macroeconomic conditions. As operators seek to maximize asset utilization while managing capital expenditure, Floating Production Storage and Offloading (FPSO) equipment has emerged as a critical enabler of offshore field development. The Worldwide Floating Production Storage and Offloading Equipment Market study provides a comprehensive lens into this evolving ecosystem, offering decision-makers the analytical rigor required to navigate the forecast period from 2026 through 2032.
Our latest market research captures the momentum building across the sector. The overall market valuation expanded from approximately US$9.0 billion in 2020 to an estimated US$12.9 billion in 2025, reflecting sustained demand across multiple offshore basins. Looking ahead, the market is projected to follow a compound annual growth rate of 7.34 percent, reaching a substantial valuation by the end of the forecast window. This trajectory underscores a sector that is not merely recovering from cyclical downturns but is being reshaped by structural demand drivers, technological standardization, and changing commercial arrangements.
The strategic value of this analysis lies in its ability to translate macroeconomic and project-level signals into actionable intelligence. For executives evaluating capacity allocation, supply chain partnerships, or fleet expansion strategies, the report delineates where value pools are forming, which commercial models are gaining traction, and how competitive dynamics are consolidating around a set of capable, globally positioned players. Rather than offering static snapshots, the study maps the interplay between equipment categories, water depth classifications, and regional project pipelines, enabling stakeholders to anticipate shifts in procurement timing, scope definition, and risk allocation.
Market Trajectory and Core Dynamics
The growth path reflected in the data is neither linear nor uniform. Market expansion between 2020 and 2025 was characterized by incremental gains punctuated by project sequencing decisions, contract negotiation cycles, and the influence of input cost dynamics. Going forward, the forecast period reveals a more pronounced acceleration, with yearly valuations climbing steadily as project awards translate into fabrication, conversion, and installation activity. This pattern highlights the importance of understanding lead-time sensitivity and the cascading effects of final investment decisions on equipment demand.
Worldwide Floating Production Storage and Offloading Equipment Market
Several structural dynamics are reshaping how FPSO projects are conceived and executed. Lease-and-operate contracts have gained considerable share in recent award cycles, reflecting a broader industry preference for models that reduce upfront operator capital exposure while transferring operational responsibility to specialized providers. This shift toward turn-key, lease-based arrangements is altering the risk-reward calculus for both operators and equipment suppliers, favoring entities with strong execution track records, financial flexibility, and the ability to manage long-duration charters.
Regional content requirements and local supply chain development continue to influence project economics in key basins. In certain jurisdictions, regulatory frameworks designed to foster domestic industrial capacity can increase project budgets while simultaneously expanding the pool of trained personnel and supporting suppliers. Understanding these trade-offs is essential for bidders and investors evaluating entry strategies, as compliance costs and schedule implications can materially affect bid competitiveness and margin structures.
Macro energy pricing and supply environment conditions further modulate investment decisions. Variations in benchmark crude pricing and gas market dynamics influence the economic viability of offshore development schemes, particularly for projects with higher breakeven thresholds. At the same time, the push toward decarbonized operations is starting to inform equipment specification decisions, with operators increasingly favoring concepts that reduce greenhouse gas emissions intensity through electrification, process optimization, and integrated subsea-to-topsides design. These considerations are becoming embedded in procurement criteria and are reshaping the competitive differentiation of equipment and service providers.
Equipment Segmentation, Water Depth, and Geographic Distribution
The FPSO equipment market is inherently multi-dimensional, spanning process equipment, mooring and marine systems, power generation and distribution, and safety and control systems. Each category carries distinct technology requirements, supply chain dependencies, and margin profiles. Process equipment typically anchors the scope definition of an FPSO, reflecting the central role of separation, treatment, and process control in field development plans. Mooring and marine systems remain critical to station-keeping reliability and operational safety, particularly in exposed environments and ultra-deepwater settings. Power generation and distribution systems, alongside safety and control architectures, are increasingly scrutinized for their contribution to overall energy efficiency and compliance with evolving operational standards.
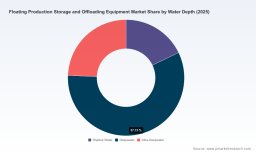
Water depth classification further differentiates demand patterns and engineering complexity. Shallow water projects continue to support a meaningful share of activity, often leveraging mature designs and established fabrication pathways. Deepwater deployments represent the largest demand concentration, reflecting the migration of development activity into more challenging environments where FPSO flexibility offers distinct logistical and economic advantages. Ultra-deepwater applications, while smaller in relative terms, are characterized by higher technical barriers, customized engineering, and longer execution cycles, making them focal points for specialized contractors and technology leaders.
Geographic distribution of demand is similarly varied, with activity concentrated across multiple offshore basins. Latin America remains a dominant demand center, supported by extensive pre-salt programs and ongoing fleet expansion. Asia Pacific continues to contribute a significant share, driven by regional field developments and conversion activity. Africa maintains a steady presence as operators advance new projects and extend the life of existing facilities. Europe and the Middle East and North America region also represent relevant demand pockets, often associated with specific field developments, conversion opportunities, and technology demonstration projects. Importantly, the relative weight of these regions is not static; it evolves with the timing of final investment decisions, the pace of regulatory approvals, and the competitive dynamics of local content and supply chain readiness.
Worldwide Subsea Well Access And BOP System Market
Commercial Models and Project Delivery Evolution
The way FPSO capacity is procured and operated has become as strategically important as the equipment itself. Operators are increasingly evaluating total cost of ownership, schedule certainty, and operational flexibility when selecting between newbuilds, conversions, and lease-based arrangements. Conversion programs offer potential schedule and cost advantages by repurposing existing hull structures, while newbuilds provide design freedom andthe ability to incorporate latest-generation process and decarbonization features. The choice between these pathways often hinges on fleet availability, yard capacity, hull integrity assessments, and the specific production profile of the target field.
Standardization initiatives are beginning to influence procurement efficiency. The emergence of standardized hull concepts and modular delivery approaches is reducing engineering redundancy, compressing cycle times, and improving predictability for repeated project types. For suppliers and operators alike, standardization can unlock economies of repetition, simplify spare parts management, and enhance the bankability of lease-and-operate structures by reducing performance uncertainty across multiple units.
At the same time, the industry is witnessing the continued maturation of integrated delivery models. Engineering, procurement, construction, installation, and commissioning scope is increasingly bundled across multiple disciplines, including subsea systems, topsides, hull fabrication, and marine operations. Such integration can reduce interface risk, improve schedule alignment, and facilitate single-point accountability, but it also demands robust project controls, supply chain coordination, and commercial structuring. Stakeholders evaluating partnership strategies should assess not only technical capability but also the commercial architecture through which risks and rewards are shared across the project lifecycle.
Competitive Landscape and Key Players
The FPSO market is defined by a mix of specialized offshore service companies, major shipbuilders, and operator-driven project constituencies. A consolidated set of firms commands a significant share of activity, with the top three participants accounting for roughly 38.4 percent of market revenue and the top five reaching approximately 52.15 percent. This concentration reflects the capital intensity, technical complexity, and execution risk associated with FPSO projects, which tend to favor organizations with established fleet management capabilities, strong balance sheets, and long-term operator relationships.
SBM Offshore stands out for its global leadership in FPSO design, engineering, construction, installation, and lease/operate models, supported by standardized hull concepts and a substantial backlog anchored in deepwater projects across Guyana and Brazil. MODEC has built a strong reputation in EPCI and charter/operate arrangements, particularly for ultra-deepwater and harsh environment applications, with multiple active units and recent contract wins in Brazil pre-salt and Guyana. BW Offshore continues to provide FPSO ownership, leasing, and operations, with an active footprint across Brazil, Africa, and advancing projects such as Bay du Nord, while Yinson Holdings has expanded its leasing and operations portfolio with recent Brazilian deployments including Anna Nery and Maria Quiteria units.
Bumi Armada contributes design, construction, and operations capabilities with a focus on Southeast Asia and international markets, and Bluewater Energy Services delivers specialized turret mooring systems and FPSO/FSO units with expertise in harsh environments and marginal field developments. On the engineering and integration side, Saipem offers integrated EPCI services spanning subsea and topsides across multiple offshore basins, while TechnipFMC provides subsea and topside integration often in partnership with hull specialists. Keppel Offshore & Marine and Samsung Heavy Industries represent major shipyard capabilities in FPSO construction and conversions, supporting Asian and global projects, and HD Hyundai Heavy Industries adds significant capacity for deepwater hull and topsides fabrication.
The operator side is equally influential. Petrobras remains a major charterer and operator of FPSOs in Brazil's pre-salt fields, with an extensive fleet and an ongoing newbuild program, including recent final investment decisions on SEAP-scheme units awarded to SBM Offshore under build-operate-transfer arrangements. ExxonMobil continues to drive significant demand through multiple FPSO developments in the Guyana Stabroek block. These operator-led programs not only shape demand volumes but also influence technology specifications, procurement timing, and the competitive positioning of equipment and service providers.
Recent Project Developments and Demand Signals
Recent milestones illustrate the pace and direction of market activity. In early 2026, Petrobras reached a final investment decision on the SEAP scheme, awarding SBM Offshore the P-81 and P-87 FPSOs under a build-operate-transfer model, reinforcing the continued expansion of Brazil's pre-salt fleet and the preference for collaborative delivery structures. Around the same time, Hunting secured a significant equipment supply contract for an FPSO offshore Guyana, highlighting the breadth of demand across different equipment categories and the continued inflow of fabrication and supply awards tied to major operator programs.
In the second half of 2025, MODEC received an award for the FPSO Hammerhead for ExxonMobil in Guyana, contributing to a notable surge in order activity and underscoring the strength of ultra-deepwater demand in the region. BW Offshore advanced its Bay du Nord FPSO project with Equinor, completing pre-FEED activities and initiating long-lead equipment ordering, a signal that new project fronts are moving into execution-ready phases. Separately, the BW Opal FPSO arrived at the Barossa gas field and progressed through hookup and final commissioning activities ahead of first gas, demonstrating the operational transition from construction to production that characterizes mature project cycles.
Collectively, these developments point to a market where demand is being driven by multiple concurrent programs, with Brazil and Guyana acting as focal points, while additional basins contribute incremental but strategically relevant activity. For market participants, the implication is clear: visibility into award timing, scope composition, and delivery sequencing is essential for aligning capacity, securing contracts, and managing cycle-time risk.
Strategic Takeaways for 2026 Decision-Making
As organizations formulate their strategies for the 2026 to 2032 horizon, several priorities emerge. First, demand visibility should be anchored in a disciplined view of final investment decision timing, project award cycles, and the lag between contract execution and equipment fabrication. Second, commercial model selection is increasingly consequential, with lease-and-operate structures reshaping capital allocation and risk transfer; stakeholders should evaluate the implications for balance sheet exposure, operational control, and long-term profitability. Third, supply chain resilience and yard capacity must be assessed against the backdrop of concentrated demand in specific regions and water-depth segments, where competition for engineering talent, hull slots, and long-lead equipment can create bottlenecks.
Fourth, technological differentiation is becoming a decisive competitive factor. Standardization, electrification concepts, process efficiency improvements, and integrated subsea-to-topsides design are not merely engineering optimizations; they are becoming commercial differentiators that influence operator preferences and lease economics. Fifth, regulatory and local content environments require careful navigation, particularly in markets where compliance costs and domestic supply chain development intersect with project economics and schedule risk.
Finally, the concentration of market revenue among a limited set of players suggests that partnership strategy matters. Whether through joint ventures, EPCI alliances, charter structures, or technology partnerships, the ability to assemble credible, execution-ready consortia will be central to securing a position in a market where trust, track record, and financial strength are heavily weighted in award decisions.
The Worldwide Floating Production Storage and Offloading Equipment Market report is designed to provide the analytical foundation for these decisions. It integrates macro market size and growth trajectory with granular segmentation, competitive profiling, recent project developments, and sector-specific dynamics, enabling stakeholders to move from high-level awareness to targeted strategic action. By mapping where demand is forming, how it is being structured, and which organizations are positioned to capture it, the study equips executives, investors, and project planners with the intelligence needed to allocate resources, shape partnerships, and anticipate the next wave of market opportunity.
For detailed analysis of this topic, please visit the official page: Worldwide Floating Production Storage and Offloading Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


