



PW Consulting: Worldwide High Voltage System Market to Hit $247B by 2032, Growing at 18.64% CAGR

Unlocking the Currents of Growth: Strategic Intelligence for the Global High Voltage System Market (2026-2032)
The global energy infrastructure is undergoing a paradigm shift. As nations race to decarbonize grids and accommodate the surging power demands of artificial intelligence data centers and electric mobility, the high voltage system market stands at the forefront of this transformation. At PW Consulting, we recognize that navigating this landscape requires more than general industry knowledge; it demands precise, data-backed strategic intelligence. Our latest report, Worldwide High Voltage System Market, offers a comprehensive roadmap for stakeholders aiming to capitalize on the opportunities defining the next decade.
This market research is not merely a collection of statistics. It is a strategic instrument designed to inform capital allocation, risk assessment, and competitive positioning in 2026 and beyond. With a projected Compound Annual Growth Rate (CAGR) of 18.64% from 2026 to 2032, the sector is experiencing exponential expansion. The total market revenue, valued at approximately 74,550.0 Million USD in the base year 2025, is forecasted to surge toward 247,030.12 Million USD by 2032. This trajectory underscores a critical reality: the window to secure supply chains, forge partnerships, and enter key territories is narrowing. Decision-makers need to understand the magnitude of this expansion without getting lost in the noise of fragmented data sources.
Macro Trends Driving the 18.64% CAGR
The velocity of growth in the high voltage sector is fueled by converging macro trends. Historically, the market has demonstrated resilience and acceleration. From 2020 to 2025, revenue climbed from roughly 22,450.12 Million USD to the aforementioned 74,550.0 Million USD. This five-year historical performance sets the stage for the forecast period, where the compounding effect of renewable integration, grid modernization, and cross-border energy trade will drive figures even higher. By 2028, the market size is expected to breach 136,430.59 Million USD, and by the end of the decade in 2030, it will approach 196,261.41 Million USD.
Several underlying dynamics are propelling this surge. Firstly, the transition to high voltage direct current (HVDC) technologies is becoming standard for long-distance bulk power transfer and offshore wind integration. Traditional alternating current (AC) systems are increasingly unable to handle the efficiency requirements of modern renewable energy corridors. Secondly, the electrification of transport and industry is placing unprecedented load on transmission networks, necessitating upgrades to high voltage infrastructure. Thirdly, geopolitical energy security concerns are driving nations to invest in independent, robust grid capabilities, further stimulating demand for high voltage components and systems.
However, these opportunities are tempered by supply chain complexities. Industry data indicates that lead times for critical components, such as large power transformers, have extended significantly. Prices for these units have risen approximately 77% since 2019, driven by raw material costs including steel and copper. Understanding how these cost pressures impact overall market revenue and project viability is essential for financial planning. Our research dissects these cost drivers to help organizations anticipate budgeting needs and negotiate better terms with suppliers.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of established global giants and specialized regional players. Concentration ratios indicate a moderately consolidated environment where strategic alliances and technological superiority determine market share. The CR3 stands at 38.5%, while the CR5 reaches 52.1%, suggesting that while there are dominant forces, there remains ample room for niche players and regional specialists to flourish.
Key enterprise players are actively shaping the market through capacity expansion and landmark contract wins. Hitachi Energy, headquartered in Zurich, continues to strengthen its manufacturing footprint, including a significant investment exceeding 1 billion USD in U.S. manufacturing expansion announced in September 2025. This move targets high voltage grid infrastructure needs, including those for AI data centers. Similarly, GE Vernova, based in Cambridge, Massachusetts, has secured major contracts, such as the consortium award with Seatrium for the BalWin5 2.2 GW offshore HVDC grid connection in the German North Sea in December 2025. These moves highlight the strategic importance of offshore wind transmission.
In the Asia-Pacific region, companies like TBEA Co., Ltd. and NR Electric Co., Ltd. are expanding their influence with HVDC converter equipment and control systems. Meanwhile, European cable specialists such as Prysmian Group, Nexans, and NKT A/S are critical to the submarine and land interconnection segments. NKT, for instance, secured 2 billion Euro contracts with SSEN Transmission in January 2026 for 525 kV HVDC transmission links in Scotland. Sumitomo Electric Industries and Toshiba Energy Systems & Solutions Corporation are also prominent in providing cables and transformers for bulk power applications.
High Voltage Cables Market
Our report provides detailed profiles on these entities, analyzing their strategic moves, technological portfolios, and regional strengths. However, the specific revenue contributions, exact market shares, and proprietary partnership networks are detailed within the full study. Access to this granular competitive intelligence allows clients to identify potential collaborators, assess competitor vulnerabilities, and refine their own go-to-market strategies.
Segmentation Insights: Components, Voltage, and Geography
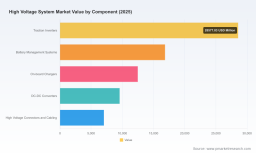
Understanding where value is generated within the high voltage system market is crucial for targeted investment. The market is segmented by component, voltage level, and region, each presenting unique growth vectors. Among components, traction inverters and battery management systems represent significant portions of the revenue stream, reflecting the electrification trend in transport and energy storage. On-board chargers, DC-DC converters, and high voltage connectors and cabling also constitute vital parts of the ecosystem.
Voltage level segmentation reveals a bifurcation between standard 400V to 600V systems and the emerging above 600V (800V architecture) systems. While the former currently holds a larger share of the market revenue, the latter is poised for accelerated adoption as efficiency standards tighten and power demands increase. The shift toward higher voltage architectures is particularly relevant for automotive and industrial applications where energy density and transmission efficiency are paramount.
Geographically, the market exhibits varied growth patterns. Asia Pacific remains a dominant region in terms of market value, driven by rapid industrialization and renewable energy installations. Europe and North America follow, with strong regulatory pushes for grid modernization and decarbonization. The Rest of the World segment also presents emerging opportunities as developing nations upgrade their transmission infrastructure. While the aggregate regional values are substantial, the specific percentage contributions and localized growth rates are reserved for the full report to ensure clients rely on our comprehensive analysis rather than partial data points.
Our segmentation analysis goes beyond top-line numbers. We explore the inter dependencies between components and voltage levels, identifying which combinations offer the highest margin potential and fastest deployment cycles. This granular view is essential for component manufacturers and system integrators looking to optimize their product portfolios.
Regulatory and Operational Dynamics Shaping 2026
Policy and regulation are as influential as technology in the high voltage sector. Governments are increasingly intervening to streamline project development and fund innovation. For instance, the U.S. Department of Energy selected four projects totaling 11 million USD under the IDEAL HVDC program in November 2024 to develop high-performance, low-cost HVDC converters. Such initiatives signal a long-term commitment to reducing the cost barrier of high voltage transmission.
Operational milestones are also accelerating. The New England Clean Energy Connect 1,200 MW high-voltage direct current transmission line from Hydro-Quebec began commercial operations on January 16, 2026. This event marks a significant step in cross-border renewable energy integration. Furthermore, regulatory bodies are adapting to infrastructure needs; Colorado enacted legislation allowing co-location of high voltage transmission lines within state highway rights-of-way to streamline development. These regulatory shifts reduce development timelines and lower soft costs, directly impacting project economics.
Grid operators are also planning aggressively. TenneT's Onshore and Offshore Grid Investment Plans 2026 outline multiple high voltage grid expansion projects, though they note longer realization times for new substations and connections. This tension between ambitious investment plans and execution realities creates a complex environment for suppliers. Understanding the timing and scale of these grid plans is vital for aligning production capacity and sales forecasts. Our report integrates these regulatory and operational updates to provide a realistic view of market accessibility and risk.
Why This Report is Indispensable for 2026 Decision-Making
In a market growing at nearly 19% annually, hindsight is insufficient. Leaders need foresight. The Worldwide High Voltage System Market report is designed to provide that foresight. It combines historical data integrity with forward-looking forecasts that account for technological shifts, regulatory changes, and competitive maneuvers.
For investors, the report offers clarity on where capital is most likely to yield returns, highlighting high-growth segments and regions. For manufacturers and suppliers, it provides actionable intelligence on demand forecasting, supply chain vulnerabilities, and customer expectations. For policymakers and grid operators, it offers a benchmark against global trends to validate domestic strategies.
Worldwide High Voltage System Market
The depth of analysis covers over 15 key companies, detailed segmentation across components and voltage levels, and a thorough examination of market dynamics including raw material constraints and regulatory frameworks. While the summary provides a sense of the scale—highlighting the jump from 74,550.0 Million USD in 2025 to a projected 247,030.12 Million USD by 2032—the specific strategic recommendations, normalized data tables, and executable insights require the full document.
We invite industry leaders, investors, and strategy teams to access the complete Worldwide High Voltage System Market research. In an era where energy infrastructure defines economic resilience, having the right data at the right time is the ultimate competitive advantage. PW Consulting delivers the intelligence necessary to navigate the high voltage currents of the future.
For detailed analysis of this topic, please visit the official page: Worldwide High Voltage System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


