



PW Consulting: Global Wood Foam Market Hits $78.5M in 2025, Projects 17.84% CAGR to $247.74M by 2032

Navigating the Green Shift: Strategic Insights from the Worldwide Wood Foam Market Research 2026
The global materials landscape is undergoing a seismic transformation. As industries grapple with the dual pressures of regulatory compliance and sustainability mandates, wood foam has emerged from a niche innovation to a critical component in the supply chain of major sectors ranging from packaging to construction. At PW Consulting, we recognize that understanding this trajectory is not merely an academic exercise but a commercial imperative. Our latest comprehensive study, the Worldwide Wood Foam Market research, offers a granular look at this evolving sector, providing the intelligence necessary for stakeholders to navigate the complexities of 2026 and beyond.
This article serves as a strategic preview of our findings. It outlines the macroeconomic forces driving growth, the competitive dynamics reshaping the supply base, and the specific operational insights contained within the full report. Our goal is to equip decision-makers with the context needed to evaluate opportunities in this high-growth market, while highlighting why detailed data access is crucial for precise planning.
Market Trajectory: From Niche to Mainstream
The wood foam market has demonstrated remarkable resilience and acceleration over the past half-decade. Based on historical analysis spanning 2020 through 2025, the sector has moved steadily away from its experimental roots toward established commercial viability. The total revenue generated by the market has seen a consistent upward trend, reflecting a broader industrial shift toward bio-based materials. By the base year of 2025, the market had solidified its position, setting the stage for the forecast period extending to 2032.
Our analysis indicates that the momentum is not slowing down. The forecast period from 2026 to 2032 predicts a robust compound annual growth rate (CAGR) of 17.84%. This growth trajectory suggests that wood foam will capture significant market share from traditional petroleum-based foams. The total market size is projected to expand substantially by the end of the forecast window, signaling a mature acceptance of wood fiber-based solutions in high-volume applications. For investors and corporate strategists, this growth curve represents more than just volume; it indicates a structural change in how materials are sourced, processed, and disposed of globally.
Worldwide Wood Foam Market
The acceleration is driven by a confluence of factors that go beyond simple cost competition. It is rooted in a fundamental reassessment of material lifecycle. As companies face increasing scrutiny regarding their carbon footprints, the appeal of a material derived from sustainably managed forests becomes a strategic asset. The market data underscores that this is not a temporary trend but a long-term reallocation of capital and resources toward renewable feedstocks.
Melamine Foam Market
Regulatory Tailwinds and Raw Material Realities
One of the most critical drivers identified in our research is the regulatory environment. Governments worldwide are tightening restrictions on single-use plastics and non-recyclable packaging materials. In Europe, the Packaging and Packaging Waste Regulation (PPWR) stands out as a pivotal force. This regulation drives demand for fiber-based alternatives like wood foam to replace single-use plastics in packaging. For manufacturers operating in or exporting to the European Union, compliance is no longer optional, and wood foam offers a compliant pathway that aligns with circular economy goals.
Beyond compliance, there is a technical advantage regarding end-of-life scenarios. Wood foam materials are designed for kerbside recyclability in existing paper and cardboard streams, supporting circular economy compliance. This feature differentiates wood foam from many biodegradable plastics that require industrial composting facilities. The ability to integrate into existing waste infrastructure reduces liability for downstream customers and simplifies the value proposition for procurement teams.
On the supply side, the reliance on sustainably sourced Nordic wood fibers from managed forests as the primary renewable feedstock ensures a stable raw material base. Unlike petrochemical feedstocks, which are subject to volatile oil prices and geopolitical instability, wood fiber supplies are managed through established forestry protocols. Furthermore, advanced processes start with wood fibers and water suspension foamed without petrochemical additives, resulting in 100% renewable resource composition. This purity profile is increasingly valuable as brands seek to eliminate hidden plastics from their product portfolios.
Segmentation Dynamics: Where the Opportunity Lies
While our full report delves into precise volumetric and valuation splits, the strategic narrative points to clear dominance in specific areas. The segmentation analysis reveals that certain types of wood foam are outpacing others in adoption rates. Flexible variants are capturing a significant portion of the market attention, driven largely by their versatility in cushioning and protective roles. Rigid variants also hold a substantial position, particularly where structural insulation and lightweight construction are priorities.
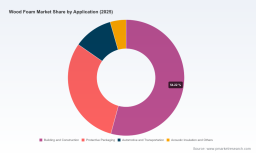
Application-wise, the building and construction sector represents a major consumption center. The need for thermal insulation and sustainable building materials aligns perfectly with the properties of wood foam. However, the protective packaging sector is rapidly emerging as a critical growth engine. As e-commerce continues to expand and consumers demand eco-friendly unboxing experiences, the demand for cushioning materials that do not compromise on sustainability is surging. Automotive and transportation applications also contribute to the mix, leveraging the lightweight nature of the material to improve fuel efficiency and reduce vehicle weight.
It is important for strategists to note that regional demand varies significantly based on local regulations and industrial maturity. Europe currently holds a leading position in terms of market share, reflecting its early adoption of sustainability mandates. North America and Asia Pacific are following closely, with distinct growth drivers in each region. North America is seeing growth driven by consumer brand commitments to sustainability, while Asia Pacific is leveraging manufacturing scale and growing domestic demand for green materials. The Rest of the World segment, while smaller currently, presents potential for future expansion as regulatory frameworks evolve globally.
Competitive Landscape: Innovation and Collaboration
The competitive environment in the wood foam market is characterized by a mix of established material giants, specialized research institutes, and niche distributors. Our report provides detailed profiles and strategic assessments of key companies shaping the industry. Leading the charge is Stora Enso, headquartered in Helsinki, Finland. As a primary global producer of Fibrease and Papira wood foam, Stora Enso is setting the benchmark for cellulose and wood fiber-based foam. Their focus on bio-based, recyclable alternatives to polymer foams with cushioning and insulating properties has made them a central figure in the transition away from plastics.
Collaboration is a key theme in this landscape. Nature-Pack serves as an exclusive North American distributor and partner for Stora Enso Fibrease, providing sustainable, recyclable packaging foam solutions as a low-carbon substitute for traditional polymer foams. Similarly, NOVAPOR supplies Stora Enso Fibrease wood foam as sheets, cuttings, punched parts, and finished packaging solutions for protective, insulating, and cushioning applications. This ecosystem approach allows technology developers to focus on production while partners handle regional distribution and customization.
Research and development remain vital. Fraunhofer WKI, based in Braunschweig, Germany, is a research institute developing 100% wood-based foam from wood particles and fibers for thermal insulation, packaging, and lightweight construction applications. Their focus on scalable production processes for rigid boards and flexible mats ensures that the technology remains viable for industrial-scale adoption. On the commercial side, Nefab collaborated on early commercialization of wood foam for eco-friendly fibre-based recyclable packaging, offering fibre-based foam solutions for industrial packaging.
The market concentration indicates a somewhat consolidated environment, with the top firms holding a significant share of revenue. This consolidation suggests that barriers to entry may be high regarding proprietary technology and supply chain integration. However, there are active manufacturers such as Reilly Foam Corporation and JB Polymers, both based in the United States, who are listed as active in the wood foam sector. Their involvement signals that the technology is accessible enough for broader manufacturing participation, provided the right capabilities are in place. Recent developments, such as the continued commercial supply and development of Fibrease and Papira wood foam lines by Stora Enso in early 2025, validate the scalability for plastic phase-out in protective applications. Additionally, capacity expansions in related foam sectors, such as the investment by American Excelsior Company to triple molded urethane production capacity, indicate a broader industry readiness to meet growing demand in foam-based applications.
Inside the Report: Actionable Intelligence for 2026
The Worldwide Wood Foam Market research report is designed to be a practical tool for strategic planning. It goes beyond high-level trends to offer specific data points that can inform budgeting, sourcing, and expansion decisions. The report covers the historical period from 2020 to 2025, providing a solid baseline for understanding how the market reacted to recent economic shocks and policy changes. It then extends the forecast through 2032, allowing for long-term capacity planning.
Readers will find detailed segmentation analysis that breaks down the market by Region, Type, and Application. While we cannot disclose the full granularity here, the report quantifies the revenue contributions of each segment in USD Million. This allows clients to identify which niches offer the highest margin potential or the fastest growth rates. For example, understanding the precise split between flexible and rigid foam helps manufacturers decide whether to invest in flexible mat production lines or rigid board presses.
The report also includes a comprehensive competitive landscape section. We analyze the market concentration, noting that the top three players account for a significant portion of the market revenue. This insight helps new entrants understand the competitive intensity and helps existing players benchmark their position. We also track recent developments and company profiles, ensuring that stakeholders know who is partnering with whom and where capacity is being added.
Furthermore, the research integrates industry context noise into the analysis. This includes specific facts about raw material sourcing, such as the use of sustainably sourced Nordic wood fibers, and regulatory impacts like the EU PPWR. By contextualizing the data within these operational realities, the report helps users assess risks related to supply chain continuity and regulatory compliance. Whether you are looking to invest in production technology, switch materials for packaging, or identify acquisition targets, the data provided is structured to support those specific use cases.
Strategic Imperatives for Decision Makers
As we look toward 2026, the message from the data is clear: wood foam is transitioning from an alternative material to a mainstream solution. The CAGR of 17.84% is not just a number; it represents a window of opportunity for companies that act decisively. For material suppliers, the imperative is to secure supply chains and scale production to meet the anticipated demand surge. For users of foam materials, such as packaging firms and construction companies, the strategic move is to pilot wood foam solutions now to stay ahead of regulatory curves and consumer expectations.
Risk management is also a key component of the strategy. While the growth outlook is positive, reliance on specific feedstocks and regulatory stability requires careful monitoring. The report provides the frameworks to assess these risks. Understanding the market concentration helps in evaluating supplier dependency. Knowing the application splits helps in diversifying revenue streams. The integration of raw material facts and regulatory updates ensures that strategies are built on a foundation of reality rather than speculation.
Ultimately, the Worldwide Wood Foam Market research is an investment in clarity. In a market defined by rapid change and complex sustainability criteria, having access to verified, detailed data is the difference between guessing and strategizing. We invite stakeholders to explore the full report to access the specific regional valuations, application splits, and competitive metrics that will define their success in this evolving landscape.
The transition to sustainable materials is inevitable. The question for industry leaders is no longer if they should adapt, but how quickly they can integrate solutions like wood foam into their operations. With the insights provided in our comprehensive study, PW Consulting aims to be the partner that accelerates that transition, turning market data into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


