



PW Consulting: Global Rail AC Market Hits $14.05B in 2025, Forecast 6.55% CAGR Through 2032

Worldwide Rail Air Conditioning Market: Strategic Intelligence for 2026 Decision-Making
As global rail networks accelerate modernization and passenger expectations for comfort and reliability intensify, the rail air conditioning market has emerged as a critical nexus of engineering innovation, regulatory compliance, and commercial opportunity. PW Consulting’s latest industry research delivers a comprehensive, data-driven assessment of this sector, providing executives, procurement leaders, and strategic planners with the actionable intelligence required to navigate a complex 2026 landscape. This study is not a static snapshot; it is a forward-looking strategic compass designed to align capital allocation, product portfolio planning, and competitive positioning with the market’s most consequential trajectories.
Worldwide Rail Air Conditioning Market
The research is anchored in rigorous historical analysis spanning 2020 through 2025, with a detailed forecast extending to 2032. Over this period, the market has demonstrated consistent expansion, transitioning from a total revenue baseline of approximately 10.8 billion USD in 2020 to an estimated 14.05 billion USD in 2025. The projected trajectory indicates sustained momentum, with the market expected to approach 14.77 billion USD in 2026 and continue scaling toward nearly 22 billion USD by the end of the forecast window. A compound annual growth rate of 6.55 percent underscores the sector’s structural resilience, driven by fleet renewal programs, urban transit expansion, and the integration of next-generation thermal management systems across diverse rail platforms. These figures represent more than aggregate movement; they reflect a fundamental shift in how rail operators conceptualize climate control, energy efficiency, and passenger experience as interdependent operational priorities.
Rail Market
Report Architecture and Operational Utility
PW Consulting’s methodology prioritizes translational insight over raw data compilation. The study is structured to support real-world planning cycles, offering decision-makers a clear pathway from macro trends to tactical execution. The report delivers an integrated examination of market sizing, segmentation dynamics, competitive positioning, and regulatory-technological inflection points, all calibrated to the practical needs of industry stakeholders.
Core Analytical Dimensions
The research dissects the market across multiple structural axes, enabling precise alignment with corporate strategy and operational planning:
- Comprehensive historical tracking and forward-looking revenue modeling that contextualizes growth within broader rail infrastructure investment cycles and fleet modernization timelines
- Analysis of product architecture evolution, including roof-mounted, split, and under-floor configurations, with attention to integration complexity, maintenance profiles, and application-specific performance requirements
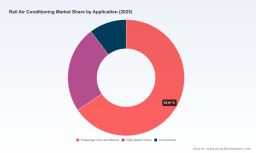
- Evaluation of deployment environments spanning passenger cars and metros, high-speed trains, and locomotives, highlighting how thermal load profiles, duty cycles, and operational constraints shape procurement preferences
- Geographic revenue mapping that identifies regional demand intensity, infrastructure maturity, and procurement pathway variations without oversimplifying local market nuances
- Assessment of material supply pressures, including copper price volatility for HVAC heat exchangers and skilled labor cost trajectories, with implications for manufacturing economics and margin management
Strategic Application for 2026 Planning
For executives confronting 2026 budgeting, capacity planning, and technology roadmap decisions, the report functions as an operational bridge between market intelligence and executable strategy. Procurement teams can leverage the segmentation analysis to validate supplier shortlists against application-specific performance thresholds and lifecycle cost expectations. Product development groups gain insight into technological adoption patterns, including inverter-driven compressor architectures, brushless DC motor integration, and low-global-warming-potential refrigerant transitions, enabling prioritization of R&D investments that align with near-term regulatory and operational mandates. Corporate strategy and business development functions benefit from competitive landscape mapping that clarifies positioning, partnership opportunities, and white-space identification across mature and emerging demand centers.
Competitive Landscape and Strategic Positioning
The rail air conditioning sector is characterized by a concentrated yet dynamically competitive environment, where established industrial manufacturers, specialized HVAC integrators, and regional equipment suppliers compete on engineering differentiation, compliance robustness, and global service reach. PW Consulting’s analysis maps this landscape with attention to both market structure and recent corporate activity, providing a realistic view of how leading players are shaping demand and defending share.
Market Concentration and Structural Dynamics
The market exhibits meaningful concentration among top-tier suppliers, with the top three firms collectively representing approximately 42.5 percent of revenue and the top five capturing roughly 58.3 percent. This structure reflects the technical barriers inherent in rail HVAC design, the importance of certified reliability, and the value of long-term operator relationships across multi-year rolling stock programs. At the same time, regional specialization and application-focused expertise continue to create room for nimble suppliers that can deliver tailored solutions for metro networks, high-speed corridors, and locomotive fleets. The competitive environment rewards companies that can combine thermal engineering precision with scalable manufacturing, regulatory compliance, and localized support infrastructure.
Leading Participants and Strategic Differentiation
Several companies define the current competitive rhythm through product innovation, contract execution, and certification readiness:
- Knorr-Bremse maintains a strong position through its HVAC division, supplying roof-mounted and under-floor units for passenger trains worldwide, and recently advanced its portfolio with a next-generation rail HVAC system targeting meaningful energy savings for European metro applications
- Faiveley Transport, operating under Wabtec Corporation, emphasizes modular air conditioning architectures with global installation experience across locomotives, coaches, and urban transit, and has been positioned as a primary HVAC supplier for major Indian Railways train expansions
- Toshiba Carrier Corporation focuses on advanced rail air conditioning units leveraging inverter technology for Japanese Shinkansen and international export projects, with an emphasis on lightweight and low-power designs
- Hitachi delivers integrated rail HVAC systems for high-speed trains and metros, incorporating energy recovery features, and has progressed validation testing for eco-friendly units tied to major high-speed infrastructure programs
- Bombardier Transportation, now part of Alstom, provides custom air conditioning packages for passenger rolling stock with an emphasis on reliability and compliance with EN 14750 standards, reinforced by recent major trainset supply awards in Europe
- Siemens Mobility offers climate control systems for rail applications, including platforms such as Mireo and Desiro, with a clear focus on sustainable cooling technologies and energy-conscious compressor innovation
- Mitsubishi Electric manufactures rail air conditioning equipment with variable refrigerant flow for metro and commuter trains, maintaining active global participation and updated certification coverage for its rail lineup
- Aqua Group produces HVAC systems for railcars, including distributed and centralized unit configurations, serving European and Asian operators with application-flexible designs
- STULZ Air Technology Systems supplies precision air conditioning for rail control rooms and passenger compartments, utilizing modular designs that support integration efficiency and serviceability
- Guangzhou Metro AC Equipment Co., Ltd. stands as a key Chinese supplier of air conditioning systems for urban rail transit, supporting domestic high-speed and metro projects with regionally attuned engineering and manufacturing execution
Recent Commercial and Technological Activity
The competitive picture is further illuminated by recent developments that signal where the market is heading in 2025 and 2026. Product launches emphasizing energy efficiency, contract awards tied to next-generation high-speed fleets, testing validation for environmentally aligned systems, supplier nominations for large-scale national rail programs, and updated compliance certifications all point to a sector in active transition. These events are not isolated milestones; they are indicators of how leading firms are recalibrating portfolios around efficiency, regulatory readiness, and regional program participation. The research synthesizes these moves into a coherent competitive narrative, helping stakeholders interpret which capabilities are likely to command premium positioning in upcoming procurement cycles.
Regulatory, Material, and Technological Forces Shaping 2026
Market trajectory in rail air conditioning is increasingly determined by intersecting external forces. Regulation, raw material economics, and technology substitution are no longer background variables; they are active determinants of cost structure, product design, and supplier selection. The report integrates these dynamics into a unified view of market risk and opportunity.
Compliance and Refrigerant Transition
Rail HVAC systems operate under strict performance expectations, including compliance with EN 14750, which governs air conditioning systems in rail vehicles and mandates reliable performance under extreme temperature conditions ranging from -25°C to +50°C. Beyond baseline performance, the refrigerant landscape is shifting. EU Stage V emission standards for refrigerants require low-GWP alternatives such as R1234yf in new rail HVAC systems from 2025, compelling manufacturers and operators to align product selection with environmental mandates while managing transition complexity. These requirements influence not only design engineering but also sourcing 전략, certification timelines, and lifecycle service planning.
Input Cost Pressures and Manufacturing Economics
Material and labor economics add another layer of strategic consideration. Copper prices for HVAC heat exchangers have risen 15 percent year-over-year to approximately 9,500 USD per tonne, directly affecting production costs for heat exchanger-intensive rail AC configurations. At the same time, skilled HVAC assembly labor costs in Europe averaged 45 EUR per hour in 2025, increasing 8 percent due to workforce shortages. These pressures interact with product architecture decisions, sourcing strategies, and regional manufacturing footprints, making cost resilience and supply chain flexibility critical competitive attributes in 2026 planning.
Technology Substitution and Efficiency Gains
Technological evolution continues to reshape performance expectations. The shift to brushless DC motors in rail AC compressors has been shown to reduce energy use by roughly 25 percent compared with traditional units, offering a clear pathway to operational savings and emissions-aligned performance. Inverter-driven architectures, energy recovery features, and modular integration approaches further expand the design space for manufacturers seeking to differentiate on efficiency without compromising reliability. The research evaluates how these technology trends interact with application requirements, certification frameworks, and operator priorities, enabling stakeholders to anticipate which solutions are likely to gain traction in upcoming procurement and fleet renewal cycles.
Translating Market Intelligence into Strategic Action
PW Consulting’s Worldwide Rail Air Conditioning Market research is designed to support decisive action under uncertainty. The study does not merely describe market size and segmentation; it contextualizes growth within the forces that will shape bidding outcomes, supplier negotiations, technology roadmaps, and regional expansion choices in 2026 and beyond. Executives who engage with the full analysis gain access to detailed segmentation insights, competitive benchmarking, procurement pathway considerations, and forward-looking indicators that connect market scale to strategic execution.
The report’s value lies in its ability to clarify where demand is forming, which technical and regulatory requirements are becoming non-negotiable, how leading suppliers are positioning themselves, and what cost dynamics may influence margin and pricing strategies. By integrating historical performance, forecast trajectory, and current industry developments into a single analytical framework, the research equips stakeholders with the perspective needed to prioritize investments, structure supplier relationships, and align product or procurement strategies with the market’s most durable trends.
For organizations preparing for 2026 planning cycles, the complete dataset, segmentation detail, competitive profiles, and regulatory-technological assessments provide the depth required to move from intuition to evidence-based strategy. PW Consulting’s full market research offers the comprehensive intelligence necessary to inform capital deployment, product planning, and competitive positioning with confidence. Readers seeking the complete segmentation breakdown, company-level analysis, and actionable recommendations are encouraged to access the source report directly, where the full scope of market intelligence is available for strategic review and decision support.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Air Conditioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


