



PW Consulting: Global Towed Array Sonar Market to Hit $1.83B by 2032, Growing at 5.2% CAGR

Global Undercurrents: Strategic Insights into the Towed Array Sonar Market Through 2032
The undersea domain has become the defining theater of modern naval competition. As quiet submarines grow more sophisticated and unmanned underwater vehicles proliferate, navies worldwide are re-evaluating their anti-submarine warfare capabilities. At the heart of this shift lies towed array sonar technology, a critical sensor suite that extends acoustic detection ranges far beyond the hull of a ship or submarine. For defense contractors, procurement officers, and investors, understanding where this market is heading is no longer optional. PW Consulting presents our comprehensive Worldwide Towed Array Sonar System Market analysis, designed to equip decision-makers with the intelligence needed to navigate a rapidly evolving landscape from 2026 through 2032.
This introduction provides a strategic preview of the findings contained within our full report. It outlines the trajectory of the global market, the competitive forces shaping supply, and the geopolitical and industrial dynamics driving procurement. Our goal is to demonstrate the depth of analysis available while highlighting why detailed segmentation and forward-looking modeling are essential for capitalizing on emerging opportunities.
Market Trajectory and Growth Outlook
The global towed array sonar market has demonstrated resilient growth over the past half-decade, evolving from a specialized naval requirement into a broader strategic asset class. Our analysis covers historical performance from 2020 through 2025, with a detailed forecast extending to 2032. In 2025, the market established a baseline of 1,280 million USD, reflecting sustained investment in anti-submarine warfare modernization programs across major naval powers.
Looking ahead, the forecast period reveals an accelerating expansion trajectory. Revenue is projected to reach 1,336.9 million USD in 2026, moderating slightly before climbing steadily through the end of the decade. By 2032, the market is anticipated to reach 1,825.23 million USD. This growth translates to a compound annual growth rate of 5.2 percent over the forecast window, driven by a combination of fleet renewal cycles, technological upgrades, and escalating undersea threats.
The historical data underscores a pattern of organic expansion punctuated by procurement spikes. Growth from 2020 to 2025 reflects the post-pandemic recovery of defense budgets and the prioritization of undersea surveillance assets. Notably, revenue growth is expected to gain momentum after 2027, suggesting that program approvals and major contract awards initiated in the mid-2020s will begin materializing in reported revenues toward the end of the decade. Decision-makers evaluating entry points or expansion strategies must account for this lag between procurement announcements and realized market revenue.
Strategic Segmentation and Application Realities
Effective market strategy requires a clear understanding of how demand is distributed across technology types, platforms, and geographic theaters. Our report dissects the market into granular segments that reveal where the highest-value opportunities reside.
Technology Types and Platform Integration
The market is bifurcated primarily by sensor architecture, with passive towed arrays commanding a larger revenue share than active systems. Passive arrays remain the cornerstone of long-range detection, favored for their ability to listen without revealing the host platform's position. Active towed arrays, while smaller in current revenue terms, are gaining traction in scenarios requiring precise target localization and tracking in high-clutter environments. Both technologies are increasingly integrated into multi-function suites that combine variable depth capabilities with advanced signal processing.
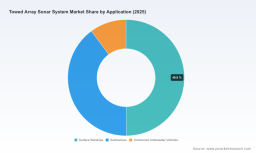
Platform adoption follows a distinct hierarchy. Surface warships represent the largest application segment, driven by the broad deployment of frigate, destroyer, and cruiser fleets equipped with variable-depth and towed array systems for open-ocean anti-submarine warfare. Submarines constitute the second-largest application, with towed arrays serving as essential complements to hull-mounted sonars on attack and ballistic missile submarines. A third, rapidly emerging segment is unmanned underwater vehicles. Though currently the smallest in revenue terms, this segment reflects a strategic pivot toward distributed sensing networks and autonomous reconnaissance, areas where lightweight towed array adaptations are beginning to appear in prototype and early-production configurations.
Geographic Demand Distribution
Demand is not uniformly distributed across global theaters. North America remains the largest regional market, reflecting the United States Navy's extensive modernization programs and the deep integration of towed array systems across submarine and surface combatant fleets. Europe follows as a significant market, shaped by NATO interoperability requirements and the procurement cycles of major naval powers. The Asia Pacific region represents a substantial and growing share of demand, fueled by security dynamics in key maritime corridors and the region's accelerating naval procurement. The Rest of World segment, while smaller in absolute terms, includes strategic procurements by allied nations seeking to enhance their anti-submarine capabilities in coordination with major defense partners.
For prospective suppliers and investors, the geographic breakdown is not merely a snapshot of current revenue. It reflects where procurement pipelines are deepest, where upgrade cycles are most active, and where export opportunities are constrained or enabled by regional policy frameworks. Our full report maps these dynamics in detail, providing the regional intelligence necessary to align sales strategies with actual demand centers.
Worldwide Towed Array Sonar System Market
Competitive Landscape: Leaders, Dynamics, and Strategic Positioning
The towed array sonar market is characterized by a concentrated supplier base, with a handful of established defense primes and specialized maritime technology firms commanding the majority of revenue. Our analysis indicates a heavily consolidated landscape, with the top three players accounting for 64.5 percent of market revenue and the top five representing 82.2 percent. This concentration reflects the high barriers to entry created by complex integration requirements, long certification timelines, and the necessity of deep relationships with naval procurement authorities.
Worldwide Towed Sonar Market
Several firms define the competitive frontier. L3Harris Technologies, based in Melbourne, Florida, has reinforced its position through the integration of advanced towed array suites such as the AN/SQQ-89 and thin-line arrays like the TB-29 and TB-37 for US Navy submarines and surface ships. In October 2025, the company secured a US Department of Defense contract for TB-37 Multi-Function Towed Array upgrades, signaling continued investment in next-generation signal processing and sensor capability. Thales Group, headquartered in Paris, supplies the CAPTAS variable depth sonar and towed array systems such as SLASM for anti-submarine warfare on frigates and destroyers. Its June 2025 delivery of the CAPTAS-4 towed array sonar to the Royal Canadian Navy for Halifax-class frigate upgrades demonstrates the company's ability to support both new construction and life-extension programs across allied fleets.
Lockheed Martin Corporation, based in Bethesda, Maryland, continues to develop and integrate towed array sonars including the AN/BQQ-10 for Virginia-class submarines and SURTASS/Low Frequency Active systems. A key integration milestone was achieved in November 2024 with the completion of AN/BQQ-10 towed array integration on a Block V Virginia-class submarine, underscoring the company's role in next-generation submarine sensor suites. Atlas Elektronik, part of ThyssenKrupp Marine Systems and headquartered in Bremen, Germany, manufactures low-frequency towed array sonars and systems tailored for Type 212 submarines, maintaining a strong European supply footprint. Leonardo S.p.A., based in Rome, offers towered array systems such as BlackHole and W-ASS for Italian Navy frigates and international export markets, while Ultra Maritime, headquartered in Dartmouth, UK, produces the Sea Spear towed array sonar and has supported Type 23 frigate upgrades to bolster Royal Navy anti-submarine warfare capabilities.
The competitive dynamics extend beyond product portfolios. Recent contract awards, delivery milestones, and integration achievements reveal which firms are successfully translating development work into fielded systems. Our report evaluates each competitor's strategic positioning, including their strength in specific technology segments, geographic reach, and the durability of their contractual relationships with major naval customers. For organizations considering partnerships, acquisitions, or competitive entry, this competitor intelligence is critical to understanding where market share is being won and lost.
Industry Dynamics: Supply Constraints, Regulation, and Geopolitical Forces
Market growth does not occur in a vacuum. Several structural forces are reshaping the supply environment, cost structures, and the pace at which new systems can be fielded.
Material Constraints and Cost Pressures
The production of sonar transducers relies heavily on PZT-based piezoelectric ceramics, which serve as the core sensing elements in towed array systems. Recent supply-side developments have introduced cost pressures. Rare earth supply constraints linked to Chinese export restrictions have driven an 8 percent price increase in PZT-based piezoelectric ceramics, according to mineral commodity data from January 2026. This escalation affects not only raw material costs but also the broader economics of sonar system production, particularly for manufacturers operating on fixed-price contracts or seeking to maintain competitive pricing in export markets. Understanding how suppliers are mitigating these cost pressures through material substitution, inventory strategies, or supplier diversification is essential for evaluating long-term profitability and contract risk.
Export Controls and Technology Transfer Restrictions
The transfer of towed array sonar technology is heavily influenced by regulatory frameworks governing defense trade. ITAR and the Wassenaar Arrangement impose strict export controls on sonar technologies, limiting technology transfers to non-NATO allies and complicating cross-border collaboration on development programs. These restrictions shape who can buy, who can build, and under what conditions systems can be integrated across allied supply chains. For commercial players, this means that market access is often determined as much by regulatory alignment as by technical capability. Our report examines how these controls affect regional market dynamics and where exceptions or allied cooperation frameworks create viable pathways for technology sharing and joint development.
Geopolitical Drivers and Alliance Frameworks
Geopolitical tensions are among the most powerful accelerants of demand. The AUKUS Pillar 2 agreement, announced in September 2024, has accelerated shared development of advanced anti-submarine warfare sonar technologies among the United States, United Kingdom, and Australia. This trilateral framework is fostering collaborative research, interoperability standards, and procurement alignment that benefit suppliers positioned to participate in joint programs. Simultaneously, security tensions in the South China Sea have driven Indo-Pacific nations to procure towed array sonars for anti-submarine warfare fleet upgrades, according to arms transfer data from December 2025. These regional pressures are expanding the addressable market beyond traditional NATO procurement cycles and creating new demand centers in Asia.
Integration with Unmanned and Distributed Systems
Beyond traditional platform integration, the market is witnessing a strategic shift toward distributed sensing. Towed array technology is being adapted and miniaturized for use with unmanned underwater vehicles, expanding the scope of where and how acoustic sensing can be deployed. This transition introduces new requirements around weight, power consumption, autonomous deployment, and data fusion, creating both challenges and opportunities for suppliers. Firms that can deliver compatible, scalable solutions for unmanned platforms will be positioned to capture growth in an application segment that, while currently small, is expected to expand as navy doctrines increasingly embrace autonomous reconnaissance networks.
Strategic Value for 2026 Decision-Making
For executives, procurement leaders, and investors evaluating the towed array sonar sector in 2026, the decisions made today will determine competitive positioning for the remainder of the decade. The market is entering a phase where growth is no longer linear but shaped by intersecting factors: fleet modernization timelines, material cost volatility, export control frameworks, alliance-driven R&D collaboration, and the emergence of unmanned platforms. A superficial understanding of market size and growth rate is insufficient to guide strategy. What is needed is detailed segmentation that reveals where revenue is concentrated, which applications are expanding fastest, which regions present the most viable export or partnership opportunities, and which competitors are securing the contracts that will define market share through 2032.
Our full Worldwide Towed Array Sonar System Market report delivers this depth. It combines macro-level trend analysis with actionable segmentation, competitor profiling, regulatory and supply chain mapping, and forward-looking scenario modeling. The report is designed to support concrete decisions: where to allocate sales and marketing resources, which technology segments to prioritize for R&D or acquisition, how to assess competitor moves in real time, and how to structure bids in a market where cost pressures and regulatory barriers can erode margins if not properly accounted for.
The preview provided here captures the structure and analytical rigor of the full study, but the complete picture requires access to the detailed data, segment breakdowns, regional demand models, and competitive intelligence compiled across hundreds of sources and validated through primary research. PW Consulting's analysis is built to serve as a strategic asset for organizations that need more than general market awareness. It is designed to provide the precision needed to act with confidence in a market where the difference between informed positioning and reactive decision-making can define long-term success.
For those committed to understanding the full scope of opportunity and risk in the towed array sonar market, the complete report offers the granularity and forward-looking insight necessary to translate market dynamics into strategic advantage. We invite you to explore the full study, where every segment, competitor profile, and dynamic driver is unpacked to support the decisions that will shape your position in the market through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Towed Array Sonar System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


