



PW Consulting: Global Circuit Breaker Market Hits $540M in 2025, 6.0% CAGR to $812M by 2032

Navigating the Classified Circuit Breaker Landscape: Strategic Intelligence for 2026 and Beyond
The global electrical safety and power distribution ecosystem is undergoing a structural transformation. As infrastructure ages, regulatory standards tighten, and digitalization reshapes equipment expectations, the UL-Classified circuit breaker segment has emerged as a critical nexus for manufacturers, distributors, contractors, and facility operators. Understanding where this market stands today—and where it is heading through 2032—requires more than surface-level headline figures. It demands a rigorous, data-grounded assessment of growth trajectories, competitive positioning, material dependencies, and the regulatory frameworks that define interchangeability and safety compliance.
PW Consulting’s newly released Worldwide Classified Circuit Breaker Market study is designed precisely for that purpose. Built on a foundation of historical tracking from 2020 through 2025 and extended forecast modeling through 2032, the research translates market signals into actionable strategy. For executives formulating 2026 investment plans, capacity allocations, procurement frameworks, and competitive responses, this report serves as a decision-grade intelligence asset. What follows is a strategic preview of the market architecture, the forces reshaping it, and the analytical depth available in the full study.
Market Trajectory: A Decade of Measured Expansion
The classified circuit breaker sector has demonstrated consistent, compounding growth over the past half-decade, reflecting broader trends in electrical infrastructure renewal, residential renovation cycles, commercial retrofitting programs, and industrial maintenance spend. Historical revenue data shows a market that navigated short-term volatility while establishing a clear upward slope. In 2020, global revenue stood at approximately 410.5 million USD. The subsequent years marked a period of recovery and acceleration, with 2025 closing at 540.0 million USD. This progression underscores a market that has moved beyond post-pandemic normalization into a phase of sustained demand generation driven by replacement cycles, code updates, and modernization initiatives.
The forward outlook reinforces this momentum. Forecasted revenue progresses from 578.59 million USD in 2026 to 811.96 million USD by 2032, embedding a compound annual growth rate of 6.0 percent across the projection window. This trajectory is not merely a linear extrapolation; it reflects the cumulative impact of loadcenter compatibility expansions, third-party classified adoption, and the gradual migration of legacy panels into upgraded safety and performance configurations. For strategic planners, the implication is clear: the market is large enough to support meaningful share capture, yet dynamic enough that timing, product alignment, and regional execution will separate leaders from laggards.
Electronic Circuit Breaker Market
Structural Composition: Type, Application, and Regional Architecture
The classified circuit breaker market is shaped by a layered segmentation structure that influences pricing, channel strategy, manufacturing focus, and go-to-market execution. At the product level, the landscape is anchored by two principal categories: miniature circuit breakers and molded case circuit breakers. Miniature circuit breakers dominate the revenue mix, reflecting their extensive deployment in residential loadcenters, light commercial panels, and replacement-driven retrofit activity. Molded case circuit breakers, while smaller in aggregate revenue share, represent a strategically vital segment for industrial maintenance, higher-current applications, and environments where durability, interrupt capacity, and serviceability are non-negotiable.
Application-side demand further differentiates execution priorities. Residential renovation continues to be a powerful demand engine, fueled by aging housing stock, safety upgrading mandates, and consumer-driven electrical modernization. Commercial retrofitting adds a complementary layer of volume, particularly in office, retail, and multi-family properties where panel compatibility and code compliance shape procurement decisions. Industrial maintenance, though smaller in relative scale, contributes critical margin characteristics and recurring demand patterns tied to operational uptime, predictive maintenance programs, and facility lifecycle planning.
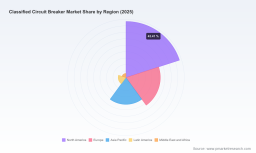
Regionally, the market exhibits a concentrated but geographically diverse demand profile. North America accounts for the largest share of revenue, reflecting the depth of loadcenter installed bases, the maturity of UL-classified interchangeability frameworks, and robust renovation and retrofit activity. Europe follows as a substantial market, supported by industrial infrastructure, commercial building upgrades, and evolving safety standards. Asia Pacific represents a significant and expanding base, where urbanization, grid investments, and manufacturing output continue to stimulate electrical equipment demand. Latin America and the Middle East and Africa, while smaller in absolute terms, offer incremental growth opportunities tied to infrastructure development, selective regional assembly strategies, and trade dynamics.
The full report decomposes these structural elements with greater precision, mapping how type, application, and regional drivers interact to shape volume, pricing, and competitive accessibility. Rather than presenting detached split data, the analysis emphasizes the strategic interplay between segments—where compatibility advantages, channel reach, and product portfolios determine which manufacturers can scale efficiently and which face structural constraints.
Competitive Dynamics: Incumbents, Compatibility, and Strategic Differentiation
The competitive field in the classified circuit breaker market is defined by a blend of broad-line electrical suppliers, specialized replacement-focused manufacturers, and global industrial players with extensive low- and medium-voltage portfolios. Market concentration remains meaningful, with the top three competitors collectively representing over half of revenue and the top five exceeding two-thirds. This concentration reflects the advantages of scale, established loadcenter compatibility, channel relationships, and brand trust in a category where safety certification and interchangeability are paramount.
Eaton Corporation maintains a particularly broad compatibility position, offering UL-Classified circuit breakers across multiple formats that align with loadcenters from General Electric, Siemens, Murray, Square D, and others. Its portfolio spans arc fault, ground fault, surge, and thermal magnetic protection, reinforcing its role as a cross-compatible replacement provider. Connecticut Electric competes with a focused replacement-oriented lineup, supplying UL-Classified breakers for residential and commercial loadcenters where compatibility and availability are the primary purchase drivers. Siemens participates with classified-compatible options, including replacements designed for Square D Type QO panels, while also leveraging its broader global breaker portfolio.
ABB Ltd brings scale across low, medium, and high voltage segments, with industrial, utility, and commercial applications forming the backbone of its circuit breaker business. Its classified-compatible solutions extend its reach into replacement and retrofit contexts where institutional procurement standards and performance requirements intersect. Schneider Electric, including its Square D branded heritage, demonstrates strong positioning in loadcenters and breaker ecosystems, with compatibility that allows third-party classified replacements to function across its platforms. General Electric, through GE Vernova, supplies breakers and loadcenters that accept UL-Classified replacements while also offering its own residential and commercial product lines.
The competitive field also includes a growing manufacturing presence from Asia and specialized industrial suppliers. CHINT Group has expanded its visibility through trade engagement and regional assembly initiatives, including recent demonstrations of power distribution solutions and local assembly activity aimed at strengthening supply chain resilience. Mitsubishi Electric contributes molded case and industrial-grade breakers with global reach. LS Electric supplies low and medium voltage breakers with an established international footprint. Fuji Electric focuses on power distribution and industrial applications, reinforcing the breadth of options available to buyers seeking industrial-grade performance alongside residential and commercial replacement demand.
Worldwide Classified Circuit Breaker Market
Recent industry activity underscores how competition is evolving beyond traditional product specs. In early 2026, CHINT highlighted an expanded exhibition presence and announced local assembly of air circuit breakers to reinforce regional supply commitments. Hager showcased prototypes of digitally enabled circuit breakers targeted at industrial applications, signaling imminent certification-driven launches. CNC Electric exhibited smart circuit breakers and intelligent devices at a major industrial trade event. These developments illustrate a broader shift in which manufacturers are not only competing on compatibility and price, but also on digital functionality, regional sourcing, and the ability to align product roadmaps with emerging certification timelines.
The complete study maps these competitive positions in greater detail, examining how product breadth, loadcenter compatibility networks, channel strength, and regional manufacturing strategies create differentiation. It also evaluates where entry barriers remain high, where substitutability pressures intensify, and how incumbent advantages can be defended or disrupted over the forecast horizon.
Industry Forces Shaping Demand and Execution Risk
Several structural dynamics are redefining how classified circuit breakers are specified, sourced, and deployed. Regulatory and safety frameworks remain central to market behavior. UL classification and listing establish the technical basis for safe mechanical and electrical interchangeability across loadcenters from multiple original manufacturers. This framework enables third-party replacement supply while preserving performance and safety expectations in residential and light commercial panels. Eaton’s compatibility reach, encompassing a wide range of loadcenters, illustrates how interchangeability can become a strategic moat when executed at scale. At the same time, manufacturers must continuously align with evolving standards, testing requirements, and listing obligations to maintain market access.
Material supply chains introduce another layer of strategic consideration. Circuit breaker manufacturing depends on copper, steel, and specialized polymers for contacts, housings, and insulation components. Material cost volatility, availability constraints, and sourcing geography can influence margin profiles and production planning, particularly for manufacturers balancing global scale with regional fulfillment expectations. Companies that manage material exposure through specification optimization, supplier diversification, and regional assembly strategies are better positioned to protect competitiveness during periods of input pressure.
Macro trends are also accelerating innovation and demand formulation. Grid modernization, renewable energy integration, and the adoption of digital or smart circuit breakers with remote monitoring capabilities are reshaping buyer expectations. These trends do not merely expand the addressable market; they alter the criteria by which products are evaluated. Electrical safety remains foundational, but connectivity, diagnostics, and integration with broader building or industrial management systems increasingly influence specification decisions, especially in commercial and industrial contexts.
Together, these forces create a market environment where compliance, material resilience, and technological differentiation converge. The report evaluates each force through a practical lens, linking regulatory requirements and material dependencies to segment behavior, competitive readiness, and near-term execution risk.
What the Study Delivers: From Macro Signals to Operational Playbooks
PW Consulting’s Worldwide Classified Circuit Breaker Market research is structured to support decision-making at multiple levels of the organization. At the strategic level, the study provides a forecast framework that traces revenue evolution from 2026 through 2032, anchored by historical data from 2020 to 2025. This enables leadership teams to benchmark growth expectations, stress-test assumptions, and align investment timing with market momentum. The analysis is presented in USD millions and calibrated to a 6.0 percent compound annual growth rate across the forecast period, offering a consistent reference point for planning and scenario development.
At the tactical level, the report examines segmentation dynamics across type, application, and region. Rather than isolating splits as static figures, it contextualizes how miniature and molded case circuit breakers perform against distinct demand drivers, how residential renovation, commercial retrofitting, and industrial maintenance shape purchasing behavior, and how regional demand profiles influence channel design, fulfillment strategy, and competitive exposure. This approach helps procurement, sales, and product teams prioritize where compatibility, pricing, and availability most directly affect win rates and share capture.
The competitive section goes beyond corporate descriptions to evaluate positioning logic. It assesses how broad-line compatibility, replacement-focused portfolios, industrial-grade portfolios, and regional assembly or sourcing strategies shape market access. It also incorporates recent developments—including trade show showcases, prototype disclosures, and local assembly announcements—to illustrate how product roadmaps and supply chain moves are shifting the competitive frontier. For executives tracking partnership opportunities, substitution threats, or regional expansion options, this analysis provides a structured basis for evaluating where value is created and defended.
Equally important, the study integrates industry context into the analytical narrative. Regulatory interchangeability standards, material input dependencies, and macro-driven innovation trends are treated not as background commentary but as active variables that influence demand elasticity, margin structure, and execution feasibility. The goal is to give organizations a practical reading of the market environment, not just a tally of sizes and shares.
Why This Intelligence Matters for 2026 Decision-Making
The 2026 decision environment calls for clarity on three questions: where demand is structurally growing, how competitive advantages are being constructed, and which external forces will alter execution outcomes. The classified circuit breaker market sits at the intersection of replacement economics, safety compliance, loadcenter compatibility, and emerging digital functionality. In such a market, the difference between a reactive strategy and a proactive one often comes down to the quality of the underlying intelligence.
Organizations evaluating capacity expansion, product portfolio adjustments, channel investments, or regional sourcing moves need more than headline growth numbers. They need to understand how type and application dynamics interact with regional demand, how compatibility breadth translates into competitive resilience, and how regulatory and material factors shape cost and risk. They also need to anticipate where digital and smart breaker innovations will begin to influence specification behavior, particularly in commercial and industrial segments.
This study is built to support those judgments. It combines historical grounding, forecast discipline, segmentation context, competitive evaluation, and industry dynamics into a single analytical framework. For executives, that means faster alignment on strategic priorities, sharper allocation decisions, and a more defensible basis for market entry, expansion, or defensive positioning.
Accessing the Full Market Intelligence
The preview above outlines the strategic architecture of the market and the analytical value embedded in the full research. However, the complete study contains the detailed segmentation breakdowns, regional revenue distributions, application-level demand patterns, company-specific positioning assessments, and forecast tables required to operationalize strategy. Those granular insights are essential for procurement planning, product roadmap prioritization, competitive benchmarking, and investment justification.
To obtain the full Worldwide Classified Circuit Breaker Market report and access the complete dataset behind this analysis, please visit the source page where the study is available for review and acquisition. The full report provides the depth needed to convert market intelligence into executable 2026 strategy—whether the objective is to strengthen compatibility-driven positioning, optimize regional supply, assess substitution risk, or align product development with emerging demand signals.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


