



PW Consulting: Global Anti-Blue Ray Myopia Lens Market to Hit $7,416.29M by 2032, 8.15% CAGR

Beyond Correction: Strategic Intelligence for the Worldwide Anti-Blue Ray Myopia Lenses Market (2026–2032)
The Convergence of Myopia Management and Digital Eye Protection
The global optical industry is undergoing a fundamental transformation. For decades, spectacle lenses were viewed primarily as corrective devices. Today, they have evolved into therapeutic interventions and protective wearables simultaneously. This shift is most evident in the Worldwide Anti-Blue Ray Myopia Lenses Market, where the dual imperatives of slowing pediatric myopia progression and mitigating digital eye strain are converging into a single, high-growth product category.
As organizations prepare their strategic roadmaps for 2026 and beyond, understanding the magnitude and mechanics of this convergence is no longer optional. It is a prerequisite for capacity planning, R&D allocation, partnership strategy, and competitive positioning. Our latest research release, the Worldwide Anti-blue Ray Myopia Lenses Market study, provides the analytical scaffolding required to navigate this complex landscape with precision.
Market Trajectory: From Recovery to Sustained Expansion
The historical trajectory of the market tells a compelling story of acceleration. Driven by rising global prevalence of myopia, particularly among school-aged children, and compounded by prolonged screen exposure across age groups, the market has moved steadily upward over the past half-decade. From a baseline in 2020, the segment has consistently expanded year-over-year, reflecting both increased diagnosis rates and broader consumer acceptance of functional lens designs.
Looking forward, the forecast period from 2026 through 2032 projects a compound annual growth rate of 8.15 percent. This sustained expansion signals that the category is transitioning from a niche innovation to a mainstream optical staple. The revenue trajectory suggests that by the early 2030s, the market will have more than doubled its size relative to the mid-2020s baseline. For executives, this growth curve is not merely a statistical indicator—it represents a widening window of opportunity for first-mover advantages in distribution, manufacturing scale, and clinical credibility. The strategic question for 2026 is no longer whether to invest in this space, but how to allocate resources to capture disproportionate value as the market matures.
The Technological Calibration: Substrate Absorption, Coatings, and Myopia-Control Optics
The product architecture underpinning this market is becoming increasingly sophisticated. Modern anti-blue ray myopia lenses are no longer simple filtered substrates. They represent a careful engineering balance between optical clarity, material index selection, and therapeutic optics. Manufacturers are leveraging substrate absorption technologies—such as UV420 blue light absorption factors—alongside advanced anti-reflective coatings to achieve blue light filtering without compromising visual fidelity.
Simultaneously, the myopia management component relies on peripheral defocus or diffusion optics designs, integrated into high-index resin materials across indices ranging from 1.499 to 1.74. The result is a functional lens that addresses two distinct clinical needs: reducing the rate of axial elongation in progressing myopes, and minimizing digital eye strain associated with extended near-work and screen exposure. This dual-function design philosophy is reshaping product development cycles, coating specifications, and inventory strategies across the value chain. Companies that can effectively communicate the clinical and experiential benefits of these integrated designs will hold a distinct advantage in prescription conversion and consumer loyalty.
Regulatory Inflection Points and Clinical Validation
One of the most significant catalysts reshaping market dynamics is the evolving regulatory environment. In September 2025, the U.S. Food and Drug Administration granted marketing authorization for Essilor Stellest eyeglass lenses, marking the first spectacle lens indicated to slow the progression of pediatric myopia in children ages six to twelve. This authorization was based on clinical data demonstrating a substantial reduction in myopia progression compared to single vision lenses. The FDA decision does more than validate a single product line; it establishes a precedent that opens the door for increased scrutiny, increased consumer trust, and increased prescription momentum across the broader myopia management category.
Parallel to this milestone, other major manufacturers have secured CE marking and FDA registration or authorization for their peripheral defocus and diffusion optics lenses, enabling distribution in key markets with recognized quality and safety benchmarks. These regulatory milestones are not abstract compliance achievements; they are direct enablers of prescriber confidence. When eye care professionals can reference authorized or registered products with documented clinical outcomes, the barrier to adoption drops significantly. For 2026 planning, organizations must factor regulatory status into their market entry strategies, partnership evaluations, and messaging architectures. The companies that can align their product narratives with clinical evidence and regulatory clarity will capture the prescribing share in an increasingly evidence-driven market.
Worldwide Anti-blue Ray Myopia Lenses Market
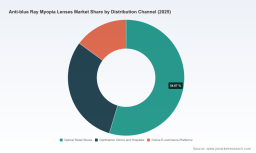
Distribution Realignment: Retail, Clinical, and Digital Channels
The path to the end user is undergoing structural change. Historically, optical retail stores have served as the dominant distribution backbone, supported by ophthalmic clinics and hospitals where prescriptions originate. Today, that hierarchy is being supplemented—and in some segments, disrupted—by the growth of online e-commerce platforms.
The coexistence of these channels creates a complex commercial landscape. Optical retail stores benefit from immediate fitting, in-person consultation, and after-sales service, which remain critical for pediatric prescriptions where frame selection, lens centration, and parent education all influence purchase decisions. Clinics and hospitals carry the authority of professional recommendation, making them essential gateways for myopia management products that require clinical endorsement. Meanwhile, online platforms are expanding reach, reducing friction for repeat purchases, and enabling direct-to-consumer education campaigns that build category awareness before a prescription is even written.
For 2026 strategy, the critical insight is that channel excellence is no longer about choosing one pathway; it is about orchestrating a multi-channel presence that matches the customer journey. Companies must evaluate where their product fits within each channel's operational model, how prescription capture occurs, and how service expectations differ. The market leaders will be those who can synchronize inventory, pricing, and brand messaging across physical and digital touchpoints without diluting the clinical credibility of the product.
Competitive Landscape: Incumbents, Specialists, and the Race for Differentiation
The competitive field in this market is characterized by a blend of global vision care giants and specialized manufacturers, each pursuing distinct strategies to secure share. At the top tier, conglomerates such as EssilorLuxottica, HOYA Vision Care, and ZEISS are leveraging substantial R&D budgets, established prescription networks, and brand recognition to push the frontier of myopia management optics. These players are not only competing on lens efficacy but also on coating durability, aesthetic design, and the breadth of their myopia control portfolios.
In parallel, a robust cohort of manufacturers—particularly from China, Japan, and Israel—is competing on material range, coating innovation, and value-positioning. Companies such as Jiangsu Green Stone Optical, Zhenjiang Select Optical, YOULI, Shanghai Conant Optics, Mingyue Glasses, Nikon, and Shamir Optical Industry are producing resin spectacle lenses with integrated anti-blue ray functionality, photochromic options, and infrared cut capabilities across a wide range of indices. Several of these firms carry CE and FDA registrations along with ISO9001 and ISO14001 certifications, enabling them to compete in regulated markets while offering flexible index options and cost-efficient manufacturing.
This dynamic creates a market structure where concentration is significant but not absolute. The leading players collectively command a substantial share of revenue, reflecting the advantages of brand equity, clinical partnerships, and global distribution. Yet the presence of capable mid-tier and regional manufacturers sustains pressure on pricing, accelerates feature innovation, and expands the overall supply base. For 2026 decision-makers, the strategic challenge is twofold: protect and extend position if you are an incumbent, or identify the segment, channel, or technology niche where differentiation can be achieved without triggering a direct confrontation with the largest brands.
Myopia Control Lens (Plastic Lens) Market
Recent Developments as Strategic Signals
Recent product and regulatory events offer a window into the direction the market is heading. In September 2025, the FDA authorization of Essilor Stellest lenses established a new benchmark for spectacle-based myopia control. In October 2025, HOYA introduced its Smooth Touch Xtreme coating on MiYOSMART lenses, pairing long-lasting hydrophobic performance with sustained blue light filtering—an enhancement that directly addresses practical consumer concerns around cleanliness, durability, and everyday usability. Later, in December 2025, EssilorLuxottica expanded its myopia management platform with Stellest 2.0 lenses powered by enhanced H.A.L.T. MAX technology, signaling that the innovation cycle is accelerating rather than plateauing.
These developments are more than product announcements. They are strategic signals. They indicate that coating technology, material durability, and next-generation optical designs are becoming decisive battlegrounds. They also suggest that manufacturers are racing to bundle clinical efficacy with tangible daily benefits, because the prescribing decision and the purchase decision are increasingly influenced by both evidence and experience. Organizations planning for 2026 must assess where their own technology roadmap aligns with these vectors and where gaps in coating, index range, or design architecture could become liabilities.
What the Research Delivers: Actionable Intelligence for 2026 Planning
Our Worldwide Anti-blue Ray Myopia Lenses Market report is designed to convert market complexity into executable strategy. Rather than offering a static snapshot, the study structures the market around the dimensions that matter most to commercial and operational decision-making.
The report provides a detailed segmentation analysis across lens materials, distribution channels, and regional markets. This breakdown enables teams to identify which material categories are gaining traction, which channels are driving prescription and purchase volume, and where regional dynamics are creating distinct growth environments. The analysis also includes a comprehensive competitive profiling of the key companies shaping the market, with headquarters, product strategies, and positioning insights that support benchmarking and partnership evaluation.
Beyond segmentation, the study examines market concentration dynamics, offering visibility into how revenue is distributed among leading players and what that implies for competitive intensity and entry barriers. The report further integrates the market context that shapes demand: the role of increased screen time in driving functional lens adoption, the material and coating technologies that define product performance, and the regulatory developments that are lowering or raising barriers in specific geographies.
Crucially, the research is built to support practical outputs. It can inform manufacturing capacity decisions, SKU architecture, coating investment priorities, channel partner selection, and geographic expansion sequencing. It provides the evidence base needed to justify R&D allocation toward myopia control optics and anti-blue light functionality, and it equips commercial teams with the segmentation intelligence required to target prescribers, retailers, and end consumers with precision.
The 2026 Decision Window: Why This Research Matters Now
2026 is a pivotal year for this market. The growth trajectory is established, the technology options are multiplying, and the regulatory environment is reinforcing clinical credibility. At the same time, the competitive field is tightening, and channel expectations are becoming more sophisticated. Organizations that enter this year with fragmented intelligence risk misallocating resources, over-indexing on saturated segments, or underestimating the importance of clinical and regulatory positioning.
The Worldwide Anti-blue Ray Myopia Lenses Market report is structured to close that intelligence gap. It provides the macro context, segmentation depth, competitive mapping, and dynamic insights needed to make informed choices about where to play and how to win. By translating growth signals into a structured strategic framework, the research enables leadership teams to align product development, commercial execution, and market entry timing with the realities of a rapidly evolving category.
Next Steps for Strategic Alignment
To leverage this intelligence effectively, organizations should begin by stress-testing current assumptions against the market's segmentation realities. Which lens material categories align with your manufacturing capabilities and margin targets? Which distribution channels match your service model and prescription capture strategy? Where does your regulatory status place you relative to competitors in key markets? Answering these questions with the support of detailed market data will sharpen strategic focus and reduce execution risk.
The full study provides the complete segmentation values, regional revenue figures, material-level breakdowns, and channel-level analysis that support these decisions. We invite you to access the source page for the complete dataset, the detailed company profiles, and the extended market dynamics discussion. In a market expanding at this pace, the difference between reactive positioning and proactive strategy is often a matter of how early and how precisely you can read the signals. This research is built to help you do exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-blue Ray Myopia Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


