



PW Consulting: Global LCD Glass Substrates Hit $8.35B in 2025, Poised for $10.73B by 2032 at 3.65% CAGR

Global Glass Substrates for LCD Market 2026–2032: Strategic Intelligence for Enterprise Decision-Makers
The worldwide market for glass substrates used in liquid crystal display manufacturing is entering a critical inflection point as panel makers navigate shifting demand patterns, stringent regulatory frameworks, and evolving supply chain architectures. Our newly released Worldwide Glass Substrates for LCD Market study delivers a comprehensive, data-grounded assessment designed to equip executives, procurement leaders, and R&D strategists with the intelligence required to position their organizations for sustained advantage through 2032.
Macro Trajectory and Structural Market Signals
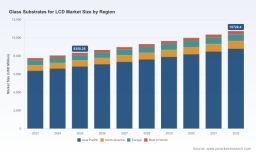
The sector demonstrated consistent expansion across the 2020–2025 historical window, with total revenue climbing to approximately 8350.25 million USD in the base year of 2025. Forward projections indicate a measured but resilient compound annual growth rate of 3.65 percent, translating the market toward roughly 10728.4 million USD by 2032. This trajectory reflects a mature yet indispensable component ecosystem where glass substrates remain foundational to display quality, thermal management, and manufacturing yield. Rather than a story of explosive growth, the data narrative points to incremental value creation driven by format transitions, substrate specialization, and regional rebalancing. Enterprise planners should interpret these figures not as static forecasts but as directional anchors that must be stress-tested against internal capacity roadmaps, panel-generation upgrade cycles, and downstream consumer electronics demand volatility.
Worldwide Glass Substrates for LCD Market
Report Architecture: Operational Content Designed for Execution
This research publication moves beyond high-level summaries to provide actionable structural insights that procurement, supply chain, and technology strategy teams can operationalize immediately. The analysis is organized to support cross-functional decision-making, with each module mapped to concrete planning workflows:
- Historical demand reconstruction spanning 2020 through 2025, enabling teams to isolate cyclical fluctuations from structural shifts in substrate specification preferences.
- Segment-level breakdowns that map substrate type adoption, application-channel demand distribution, and geographic consumption patterns, allowing readers to benchmark their positioning against broader market flows.
- Manufacturing and technology assessment covering substrate generation transitions, defect-rate optimization, thermal stability requirements, and the economics of moving toward larger glass-format production lines.
- Regulatory and compliance impact mapping, including heavy-metal thresholds, export control constraints, and tariff exposure pathways that directly influence sourcing models and regional contract structuring.
- Raw material and supply chain stress analysis addressing high-purity silica dependency, extended lead-time dynamics, and upstream mining disruption scenarios that affect cost forecasting and inventory strategy.
- Competitive positioning and corporate activity tracking, capturing recent product qualifications, production expansions, long-term supply agreements, and certification milestones that signal strategic intent among leading substrate suppliers.
Each section is built to serve as an internal briefing foundation, supporting capacity planning, vendor selection, risk mitigation, and scenario modeling. Decision-makers will find the documentation structured to translate directly into procurement memos, technology roadmap reviews, and capital allocation discussions.
Competitive Landscape: Strategic Posture of Leading Substrate Suppliers
Market concentration remains pronounced, with the top three participants capturing an estimated 88.5 percent share and the leading five reaching 96.2 percent collectively. This level of consolidation shapes pricing dynamics, technology diffusion pathways, and supplier negotiation leverage across the value chain. Understanding how incumbents are maneuvering provides essential context for enterprise sourcing and partnership strategies.
Corning Incorporated: Advancing High-Performance Alkali-Free Formats
Headquartered in Corning, New York, Corning continues to anchor its LCD substrate portfolio around the EAGLE XG family and next-generation alkali-free variants engineered for large-screen television and monitor panels. The company's October 2025 announcement of qualification for a next-generation EAGLE XG Slim glass substrate signals continued emphasis on ultra-thin panel architectures. For display manufacturers and downstream brands, these developments indicate that premium substrate performance is increasingly tied to form-factor reduction, optical transmission optimization, and compatibility with advanced production generations. Enterprises evaluating long-term supplier relationships should monitor how Corning's roadmap aligns with their own panel thickness targets, yield expectations, and cost-per-unit thresholds.
AGC Inc. and Asahi Glass: Scaling High-Transmission Substrates for Large-Format Demand
Based in Tokyo, AGC has maintained a strong presence in high-transmission glass substrates through its AN series, supporting large-format TV and IT panels with a focus on low defect rates and production consistency. The June 2025 commencement of mass production for Gen 11 LCD glass substrates at a new Japanese facility underscores AGC's commitment to scaling capacity in step with next-generation panel requirements. Asahi Glass, integrated within AGC's broader portfolio, contributes additional high-precision sheet capabilities for advanced displays. For IT and television panel producers, AGC's manufacturing expansion suggests a market environment where large-format generation transitions are accelerating, and suppliers are investing ahead of clear demand signals. Procurement teams should assess whether their internal roadmaps anticipate Gen 11 adoption timelines and whether current supplier allocations provide sufficient resilience as capacity shifts.
Nippon Electric Glass: Precision Substrates with Thermal Stability Focus
Nippon Electric Glass, operating from Otsu, Japan, has built a recognized position in precision glass substrates for LCD backlights and panels, emphasizing thermal stability as a differentiator for high-resolution displays. The November 2024 certification update under ISO 15312 reflects an ongoing commitment to process standardization and manufacturing quality assurance. For applications requiring stringent thermal management and display uniformity, NEG's product orientation offers a relevant alternative in substrate specification discussions. Enterprises operating in segments where display longevity and thermal resilience directly affect end-user experience should consider how NEG's process certifications and product characteristics compare with competing offerings in their qualification matrices.
Schott AG: Specialty Glass for Industrial and Medical Display Segments
Schott AG, headquartered in Mainz, Germany, supplies specialty glass substrates for LCD applications, including low-expansion borosilicate glasses tailored for industrial and medical display environments. This positioning highlights an important market nuance: while consumer electronics volumes dominate headline demand, high-reliability segments often require substrate formulations that balance dimensional stability, chemical resistance, and specialized performance characteristics. Organizations serving healthcare, instrumentation, or industrial control display markets may find greater strategic value in substrate options that prioritize specification precision over volume cost optimization. The report's segment analysis provides additional context on where these specialty dynamics intersect with broader market flows.
Tunghsu Group: Regional Scaling and Domestic Panel Supply Integration
Tunghsu Group, based in Tunghai, China, has established itself as a major producer of TFT-LCD glass substrates up to Gen 10.5, with supply relationships extending to domestic panel makers such as BOE and CSOT. The March 2025 signing of a long-term supply agreement for Gen 10.5 LCD glass substrates illustrates how regional manufacturers are deepening integration with local panel ecosystems. For multinational enterprises, this trajectory carries dual implications. On one hand, domestic capacity expansion can improve supply assurance and reduce logistical complexity within regional manufacturing footprints. On the other hand, shifting supplier geography interacts with export controls, tariff exposure, and technology-transfer restrictions, requiring sourcing strategies to be evaluated through a compliance and geopolitical lens as well as a commercial one.
Glass Substrate For Hard Disk Drives Market
AVIC Sanxin and IRICO Group: Mid-to-Large Format Capacity and Vertical Integration
AVIC Sanxin, operating from Shanghai, focuses on glass substrates for LCD panels with emphasis on mid-to-large size generations for consumer electronics. IRICO Group New Energy, headquartered in Beijing, supplies substrates for LCD and TFT displays while leveraging upstream production integration to pursue cost efficiency. Together, these players reflect an ongoing pattern in which substrate manufacturers align their generation coverage with the requirements of panel makers serving consumer electronics end markets. Vertical integration and generation-specific capacity allocation are becoming increasingly relevant variables in supplier evaluation, especially for enterprises seeking to balance cost structure against supply continuity.
Market Dynamics Shaping Sourcing and Planning Assumptions
Beyond corporate activity, a cluster of external dynamics is reshaping the operating environment for glass substrate procurement and display manufacturing strategy. Executives should incorporate these factors into scenario planning, contract structuring, and inventory policy design.
- Material cost structure: Alkali-free borosilicate glass accounts for a dominant share of LCD substrate material costs because high-purity silica requirements impose stringent sourcing and processing standards. This concentration means that raw material pricing, purity specifications, and supply reliability can materially influence total substrate economics.
- Regulatory compliance pressure: EU REACH regulations have mandated heavy-metal limits below 100 ppm in LCD glass substrates since the 2024 update. Compliance expectations are no longer peripheral; they affect material selection, supplier qualification, and cross-border procurement pathways, particularly for enterprises selling into European markets.
- Export control and technology transfer constraints: US CHIPS Act export controls have restricted advanced LCD glass substrate technology transfers to China as of 2025. This development introduces additional complexity for organizations managing global R&D collaboration, equipment sourcing, and supplier development across jurisdictions.
- Tariff exposure and regional cost asymmetry: China has imposed tariffs ranging from 10 to 25 percent on imported LCD glass substrates from Japan and the United States under Section 301 countermeasures. These measures alter the relative cost competitiveness of regional sourcing options and can shift the economics of cross-border supply arrangements.
- High-purity silica availability: Global high-purity silica sand supply lead times have extended to approximately 6 to 9 months due to mining disruptions in 2025. Extended lead times challenge just-in-time procurement models and increase the importance of forward planning, safety stock calibration, and supplier diversification.
These dynamics do not operate in isolation. They interact with generation transitions, regional manufacturing footprints, and the concentration of substrate supply among a small number of scale players. The full research publication connects these variables to segmentation-level demand patterns, regional consumption flows, and application-channel exposure so that enterprises can assess where these pressures are most likely to influence cost, availability, and qualification decisions.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle requires enterprises to make commitments under conditions of moderate growth, elevated supplier concentration, and material non-technical risk factors. In that environment, strategic value comes from understanding how macro trajectory, competitive behavior, regulatory exposure, and raw material constraints intersect rather than from viewing any single factor in isolation. The Worldwide Glass Substrates for LCD Market study is designed to provide that integrated perspective.
For procurement and supply chain leaders, the research supports supplier qualification prioritization, contract term evaluation, and sourcing-mix optimization by linking market concentration, generation coverage, and regional supply developments to practical purchasing considerations. For technology and product strategy teams, it provides context on substrate type preferences, application-channel demand distribution, and the implications of format transitions for panel architecture decisions. For executive and corporate development teams, it offers a structured view of where market value is accumulating, which participant strategies are gaining traction, and where compliance or geopolitical factors may alter competitive positioning over the forecast horizon.
The publication also functions as an internal alignment tool. Because the analysis is organized around segmentation, dynamics, and competitive activity, it can be used to frame cross-functional discussions across R&D, manufacturing, procurement, and regional operations without requiring each group to reconstruct the underlying market logic independently.
How to Use This Intelligence
Enterprises gain the most value when the research is treated as a decision-support platform rather than a one-time read. The segmentation data, competitive tracking, and market dynamic analysis are most effective when mapped onto internal assumptions about panel-generation adoption, demand volatility, regional manufacturing strategy, and supplier risk tolerance. The report enables this mapping by presenting macro trajectory alongside structural breakdowns and recent corporate developments, allowing teams to test their strategic hypotheses against market-level evidence.
To access the complete segmentation analysis, regional and application-channel demand distribution, detailed supplier activity timelines, and full dynamic impact assessment, visit the official PW Consulting research page. The complete Worldwide Glass Substrates for LCD Market report provides the depth required to translate these strategic signals into precise planning actions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Substrates for LCD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


