



PW Consulting: Global Automotive Helical Spring Market Hits $3.12B in 2025, Projected to Reach $4.29B by 2032

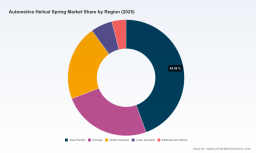
Navigating the Automotive Helical Spring Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview
The automotive helical spring market stands at a critical inflection point as global original equipment manufacturers navigate simultaneous pressures from electrification, regulatory tightening, and supply chain realignment. Our latest Worldwide Automotive Helical Spring Market study provides a comprehensive, data-driven foundation for strategic planning through the end of the decade. Built on a rigorous historical baseline spanning 2020 through 2025 and extending forecast visibility to 2032, this intelligence asset translates complex market signals into actionable pathways for procurement leaders, product development teams, and competitive strategy executives. With the global market reaching approximately 3.12 billion USD in 2025 and projected to expand toward 4.29 billion USD by 2032, a compound annual growth rate of 4.65 percent shapes the trajectory that forward-looking organizations must navigate. The following analysis outlines the structural forces defining the sector, the competitive architecture shaping supplier relationships, and the operational dimensions that will separate resilient companies from those left behind. This is a trailer for a deeper intelligence asset. Complete segmentation breakdowns, regional revenue distributions, type-specific growth profiles, and company-by-company financial exposure metrics are available through the full report. Accessing the complete dataset ensures that your strategic planning rests on verified, granular intelligence rather than generalized industry narratives.
Macro Trajectory and Demand Architecture
Market expansion over the past half-decade reflects a sector recovering from post-pandemic supply disruptions while absorbing structural shifts in vehicle architecture. Revenue progression from 2.55 billion USD in 2020 through a brief contraction in 2021, followed by recovery and acceleration into 2025, illustrates the resilience of helical spring demand even amid semiconductor constraints, logistics bottlenecks, and raw material volatility. The forecast window extends steady growth across 2026 through 2032, with the market projected to nearly double its 2020 baseline by decade end. Several underlying demand vectors sustain this trajectory. Passenger vehicle production recovery in key Asian and European markets continues to anchor volume, while commercial fleet operators increasingly retrofit and maintain suspension systems to extend asset lifecycles. Light commercial vehicle deployments in urban logistics networks further stimulate replacement and OEM demand. Heavy commercial applications, though smaller in relative volume, contribute to baseline stability due to rigorous maintenance schedules and longer service intervals. The diversity of end-use demand across passenger cars, light commercial vehicles, and heavy commercial vehicles creates a portfolio effect that buffers individual segments against cyclical downturns. Understanding how these application streams interact with regional manufacturing footprints, cost structures, and supplier capabilities forms a central pillar of the full report. Readers seeking precise revenue allocations across application categories and regional markets will find detailed breakdowns in the complete study.
Competitive Architecture and Strategic Positioning
The competitive landscape reflects a concentrated yet fragmented structure where global specialists operate alongside regional cost-optimized manufacturers. Top-three concentration reaches approximately 38.45 percent, while the top five suppliers command roughly 52.6 percent of market revenue. This concentration level indicates meaningful scale advantages among leading players, yet leaves sufficient room for regional specialists to capture niche value through customization, localized service, and application-specific engineering. Japanese firms such as NHK Spring, Showa Corporation, and Chuo Spring maintain strong positions through advanced manufacturing, OEM relationships, and product integration expertise spanning passenger cars, trucks, and motorcycles. NHK Spring recently advanced its portfolio with a product launch in September 2025, introducing high-strength helical springs optimized for electric vehicle suspensions and lightweighting objectives. Showa Corporation completed durability testing validation in April 2025 for helical springs integrated into Honda hybrid vehicle lineups, reinforcing quality assurance narratives aligned with electrified powertrain requirements. Mubea Fahrwerke GmbH continues to strengthen its European OEM footprint, earning supplier nomination from BMW in June 2025 for helical torsion springs in next-generation chassis systems. Its affiliate Lesjöfors Springs extends spring manufacturing capabilities across Europe and Asia, supporting shock absorber and engine valve applications with broad geographic reach. Chinese manufacturers such as Zhejiang Changchun Spring and Huanyu Spring emphasize cost-effective high-volume production and custom helical compression solutions, leveraging steel alloy capabilities and export-oriented supply chains. Industrial Spring Inc. anchors North American heavy-duty truck suspension supply, serving a market segment where durability and load-bearing performance drive purchasing decisions. Competitive differentiation now extends beyond unit pricing. Lightweight design, fatigue resistance, corrosion mitigation, and supply chain responsiveness increasingly determine sourcing outcomes. The full report maps competitive positioning through revenue estimates, product scope, geographic coverage, and recent strategic moves, enabling procurement teams to benchmark supplier alternatives with precision.
Material, Regulatory, and Operational Dynamics Shaping Value Chains
Several interconnected external forces are reshaping how helical springs are specified, manufactured, and validated. Raw material conditions influence production economics and supplier margin structures. Automotive helical springs predominantly rely on SAE 5160 high-carbon spring steel, with prices experiencing fluctuations of 10 to 15 percent due to alloy scrap supply constraints. At the same time, silicon-manganese steel adoption has demonstrated significant corrosion reduction of approximately 30 percent in high-humidity regions, creating engineering incentives for material substitution where environmental exposure is elevated. Regulatory frameworks are also altering design priorities. Euro 7 emission standards mandate lighter suspension components, pushing development teams to redesign helical springs for around 20 percent weight reduction without compromising fatigue performance. These requirements directly impact geometry planning, material selection, and validation testing cycles. Safety standards add additional specification rigor, with FMVSS 209 requiring helical springs in seat belt retractors to withstand 5000 cycles at a 2000N load, reinforcing the importance of certified manufacturing controls and traceability. Labor economics further differentiate regional production strategies. Precision coiling operations require skilled labor, with US hourly rates near 28 USD compared with roughly 6 USD in China. This cost differential shapes make-versus-buy decisions, nearshoring evaluations, and automation investment pacing. Companies that integrate material strategy, compliance readiness, and labor optimization into a cohesive sourcing and design framework gain meaningful competitive advantage. The complete report translates these dynamics into scenario-based implications for procurement, product engineering, and regional capacity planning, with actionable guidance for managing volatility and capturing value from materials innovation.
What the Full Study Delivers
The Worldwide Automotive Helical Spring Market study is structured to support decision-making across multiple functional domains. It provides verified historical data, forward-looking forecasts, and multi-dimensional segmentation that connects market size with strategic interpretation. The analysis is organized to answer practical questions that leaders face when allocating capital, qualifying suppliers, and preparing for regulatory or technological transitions. Key deliverables include a complete market sizing framework covering the historical period and forecast horizon, with consistent methodology that supports trend analysis and benchmarking. Segmentation analysis examines market structure by region, type, and application, offering organizations the ability to align sourcing and product roadmaps with demand concentration patterns. Competitive profiling explores the strategies, geographic reach, product focus, and recent developments of leading suppliers, enabling structure-to-strategy comparisons for procurement and partnership evaluation. The study also integrates material and regulatory context so that engineering and compliance teams can assess how raw material trends and standard requirements influence cost, design, and validation timelines. Scenario interpretations translate data into operational guidance, highlighting where growth is likely to concentrate, where margin pressure may intensify, and where supplier diversification or vertical integration could improve resilience. This report is particularly valuable for organizations planning OEM negotiations, capacity investments, or entry into new application streams. It is designed for teams that need more than top-line estimates: they require structured intelligence that links market behavior to internal planning assumptions, risk registers, and strategic initiatives. Full access to the source data, including detailed regional and application breakdowns and type-level revenue distributions, ensures that decisions are grounded in a complete picture rather than partial indicators.
Worldwide Automotive Helical Spring Market
Strategic Takeaways for 2026 and Beyond
As organizations prepare for 2026 planning cycles, several strategic priorities emerge from the current market architecture. Supplier evaluation must extend beyond unit pricing to include lightweighting capability, fatigue and corrosion performance, compliance readiness, and geographic flexibility. Procurement strategies should assess how raw material volatility, particularly in high-carbon spring steel and alloy scrap availability, will affect cost forecasting and contract structuring. Engineering teams need to anticipate how regulatory pressure, especially around weight reduction and safety validation, will influence spring design, testing cycles, and qualification timelines. Competitive positioning will increasingly reward suppliers that can combine scale, precision manufacturing, and application-specific engineering with reliable delivery and regional responsiveness. Companies that treat the helical spring market as a static commodity segment risk underestimating the value of technical differentiation and supply resilience. Those that align sourcing, product development, and regulatory strategy with verified market intelligence will be better positioned to manage cost, performance, and risk through the forecast period. The full report converts these priorities into detailed benchmarks, regional demand maps, type-level growth outlines, and supplier profiles that support structured decision-making. Accessing the complete study provides the granularity necessary to validate assumptions, compare alternatives, and align cross-functional teams around a shared market view.
Automotive Leaf Spring Assembly Market
The Worldwide Automotive Helical Spring Market study is available now. Complete regional, type, and application breakdowns, supplier financial context, and scenario-based planning guidance are included in the full report. Download the complete intelligence package to equip your 2026 strategy with verified, presentation-ready market insights.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Helical Spring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


