



PW Consulting: Global Air Quality Sensor ICs Market to Hit $1.57B by 2032

A Strategic Imperative for Semiconductor Leaders: Navigating the Global Air Quality Sensor ICs Market (2026–2032)
The global trajectory of environmental monitoring is no longer defined solely by regulatory compliance; it is increasingly driven by a convergence of consumer health awareness, automotive cabin optimization, and industrial automation. For semiconductor strategists and product leaders, the air quality sensor integrated circuit (IC) market represents a high-growth vector where technological differentiation meets expanding application scope. Our latest research into the Worldwide Air Quality Sensor ICs Market provides a granular, forward-looking intelligence framework designed to support critical investment and portfolio decisions throughout the 2026–2032 forecast horizon.
In a landscape characterized by rapid technological iteration and shifting geopolitical supply chains, relying on historical analogs or fragmented public data is insufficient. This report distills complex market mechanics into actionable strategic insights, enabling stakeholders to identify high-value segments, anticipate competitive disruptions, and align R&D roadmaps with emerging demand patterns. The following analysis outlines the core value proposition of this study, highlighting the macro-economic currents, competitive dynamics, and operational frameworks that will define market leadership in the coming years.
Market Trajectory and Macro-Economic Foundations
The air quality sensor IC industry has demonstrated robust resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a market that has consistently grown its total addressable revenue, culminating in an estimated global valuation of approximately 780.0 million USD in the base year. This upward momentum is not merely cyclical; it is structural, fueled by the integration of sensing technologies into everyday electronic ecosystems and stringent indoor air quality (IAQ) mandates across major built environments.
Looking ahead, the forecast period from 2026 to 2032 projects sustained expansion. By 2026, the market is poised to cross the 868.92 million USD threshold, signaling a decisive acceleration in adoption rates across both mature and emerging application verticals. The compound annual growth rate (CAGR) for this forecast window stands at a compelling 10.51 percent, underscoring the sector's capacity to outperform broader semiconductor segments. As the timeline extends toward 2032, revenue projections escalate significantly, reflecting the maturation of next-generation sensor platforms and the deepening penetration of multi-parameter ICs in high-volume consumer and industrial deployments.
Air Quality Sensor Market
This growth trajectory is underpinned by a fundamental shift from single-function sensing to integrated, intelligent monitoring solutions. Manufacturers are increasingly prioritizing ICs that combine particulate matter detection, volatile organic compound (VOC) analysis, and environmental compensation within unified packages. Our research quantifies the revenue contribution of these converging technology stacks while isolating the specific drivers that will determine market share allocation among key geographies and end-use segments. While precise regional and application-level revenue breakdowns are detailed exclusively within the full report, the strategic narrative is clear: value is migrating toward ecosystems that demand higher accuracy, lower power consumption, and seamless system integration.
Technology Segmentation: From Discrete Sensing to Integrated Intelligence
The architecture of the modern air quality sensor IC market is defined by a multidimensional segmentation structure that spans technology type, application domain, and geographic deployment. At the core of the technology split, the market encompasses gas sensor ICs, particulate matter sensor ICs, and an emerging category of integrated multi-parameter ICs. Each of these technology tracks presents distinct value chains, manufacturing complexities, and performance benchmarks, requiring stakeholders to evaluate investment opportunities through a nuanced lens of risk and return.
Gas sensor ICs continue to anchor a substantial portion of overall revenue, driven by the persistent demand for VOC and NOx detection in both indoor and outdoor environments. Concurrently, particulate matter sensor ICs are witnessing accelerated adoption as public health initiatives and smart city infrastructure projects mandate real-time PM2.5 and PM10 monitoring. The integrated multi-parameter segment, though currently smaller in absolute scale, represents a critical frontier for differentiation, as system designers increasingly seek consolidated solutions that reduce bill-of-materials complexity and streamline embedded processing requirements.
On the application side, the market is diversified across consumer electronics, automotive cabin monitoring, industrial and smart city infrastructure, and medical and healthcare sectors. Each vertical carries unique performance tolerances, certification pathways, and procurement cycles. Consumer electronics leverage sensor ICs for personal health and home automation, while automotive cabin monitoring demands robust, humidity-tolerant solutions capable of operating in dynamic vehicular environments. Industrial and smart city deployments prioritize scalability, environmental ruggedness, and network interoperability, whereas medical and healthcare applications require exceptional accuracy and calibration stability to support diagnostic and therapeutic workflows.
The report provides a comprehensive mapping of these application segments, analyzing how revenue streams are distributed and where onboarding barriers remain highest. Rather than presenting isolated percentage splits, the study ties application dynamics to broader macro trends—such as the proliferation of energy-efficient HVAC systems in commercial buildings and the regulatory push toward healthier vehicle interiors—enabling readers to assess which verticals will generate the highest marginal returns over the forecast period.
Competitive Landscape: Key Players and Strategic Positioning
The global air quality sensor IC market is characterized by a moderately concentrated competitive environment, where a handful of established incumbents and technology specialists command a significant share of overall revenue. Our analysis indicates that the top three firms collectively account for approximately 42.5 percent of total market revenue, while the top five players extend their combined footprint to roughly 58.8 percent. This concentration level suggests a market where scale advantages and proprietary technology stacks play a decisive role, yet sufficient white space remains for agile entrants and specialized component suppliers to capture value in niche or rapidly evolving subsegments.
Among the recognized leaders shaping this competitive landscape is Sensirion AG, headquartered in Stäfa, Switzerland. Sensirion has built a strong reputation for its CMOSens®-based sensor ICs and modular platforms, including the SGP40 and SGP41 VOC/NOx sensor families and the integrated SEN6x platform that combines PM, CO2, and multi-gas sensing capabilities for indoor air quality monitoring. In December 2025, the company announced next-generation SEN65 and SEN63C indoor air quality sensor platforms, signaling a continued commitment to multi-parameter measurement enhancement and system-level optimization.
Worldwide Air Quality Sensor ICs Market
ScioSense B.V., based in Eindhoven, Netherlands, competes through its specialization in MOX-based air quality sensor ICs, notably the ENS16x, ENS160, and ENS170A series. These products are engineered for VOC, multi-gas, and indoor air quality detection, with certain variants offering integrated processing and automotive-grade qualifications. ScioSense's focus on configurable gas sensing solutions positions it as a flexible supplier for OEMs seeking customized environmental monitoring architectures.
Bosch Sensortec GmbH, operating from Reutlingen, Germany, leverages its MEMS expertise to deliver a diversified portfolio that includes the BME688 and BME690 4-in-1 gas, humidity, temperature, and pressure sensors augmented with AI-driven interpretation capabilities. The company also offers the BMV080, an ultra-compact PM2.5 particulate matter sensor. In June 2025, Bosch Sensortec unveiled the BME690 with up to 50 percent reduced power consumption, specifically optimized for high-condensation environments. Continuing this momentum, the company introduced the BMV080 in January 2026, describing it as the world's smallest fanless PM2.5 particulate matter air quality sensor for ultra-compact IoT devices.
Renesas Electronics Corporation, headquartered in Tokyo, Japan, supplies the ZMOD series of air quality sensor IC modules, including the ZMOD4410 for total VOC and indoor air quality applications and the ZMOD4510 for outdoor monitoring. Renesas differentiates its offerings through a firmware-configurable architecture that simplifies signal conditioning and accelerates time-to-market for end-product developers.
Infineon Technologies AG, based in Neubiberg, Germany, is recognized for its XENSIV™ PAS CO2 sensor ICs, which utilize photoacoustic spectroscopy to deliver accurate indoor air quality and CO2 monitoring within compact form factors. In September 2024, Infineon released the XENSIV PAS CO2 5V sensor for smart buildings, emphasizing real-time air quality data delivery and compliance with IAQ standards.
The competitive field also includes prominent contributors such as Amphenol Advanced Sensors (Telaire) in St. Marys, Pennsylvania, USA, which manufactures CO2, VOC, dust/PM, and humidity sensors leveraging NDIR and other technologies for HVAC, building automation, and automotive use cases. Amphenol SGX Sensortech, based in Corby, United Kingdom, develops MOX and other gas sensor technologies for indoor air quality, with recent introductions including the SGX4410 and SGX4510 series for versatile detection. Additionally, Cubic Sensor and Instrument Co., Ltd. in Wuhan, China, produces integrated air quality sensor modules that combine PM, CO2, VOC, and environmental parameters using NDIR, laser, and other sensing technologies.
Our report goes beyond corporate profiling to examine product portfolio overlaps, pricing strategies, and the strategic implications of recent product launches. By connecting launch timelines to broader market demand shifts, the analysis reveals which technology roadmaps are likely to capture disproportionate adoption and which legacy architectures may face margin compression.
Industry Dynamics: Supply Chain Pressures, Regulatory Shifts, and Environmental Realities
Market growth does not occur in a vacuum. The air quality sensor IC sector is navigating a complex matrix of macro-economic and regulatory forces that will profoundly influence sourcing strategies, cost structures, and regional competitiveness. In January 2026, U.S. Presidential Proclamations imposed a 25 percent tariff on certain advanced computing chips, while directing policy actions on critical minerals supply chains. Although this measure primarily targeted high-performance computing semiconductors, its ripple effects extend to the broader semiconductor ecosystem, potentially affecting the cost and availability of sensor IC components that depend on specialized fabrication processes and advanced packaging technologies.
Simultaneously, geopolitical tensions surrounding critical material access continue to shape the industry's operational calculus. China's restrictions on rare earth and critical mineral exports have raised expectations of supply shortages and increased input costs for materials integral to MEMS and gas sensor production. These constraints are particularly relevant for manufacturers that rely on specific element dependencies for sensor calibration, thermal management, or protective coatings. Strategic procurement and supply chain diversification are no longer optional; they are competitive necessities that will determine which firms can sustain margin stability through the forecast period.
Beyond geopolitical and trade dynamics, the environmental footprint of semiconductor manufacturing itself introduces additional cost and compliance pressures. Semiconductor fabrication processes generate air pollutants, including VOCs, NOx, SOx, and particulate matter, which influence upstream environmental compliance costs for sensor IC production. As regulators worldwide tighten emissions monitoring and enforce more rigorous sustainability standards, sensor manufacturers may face increased capital and operational expenditure requirements to maintain compliant production lines. Our report evaluates how these upstream dynamics intersect with downstream demand, identifying the segments that are best insulated from cost pass-through challenges and the geographies where regulatory alignment may facilitate faster adoption.
What This Research Delivers: An Operational Framework for 2026 Decision-Making
The Worldwide Air Quality Sensor ICs Market research is engineered to function as a strategic decision-support tool, not merely a descriptive data repository. Stakeholders across semiconductor manufacturing, component distribution, systems integration, and venture investment will find the report structured to answer the questions that directly impact capital allocation and product planning.
Key analytical deliverables include a comprehensive historical and forecast revenue assessment across the entire market and within defined segmentation parameters. The study traces the trajectory from 2020 through 2025 to establish baseline momentum, then projects forward through 2032 to map inflection points, growth accelerations, and potential saturation thresholds. By isolating the CAGR for the forecast period and contextualizing it within technology adoption curves, the report enables readers to differentiate between short-term demand spikes and durable secular growth.
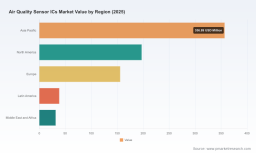
The segmentation analysis provides a structured dissection of revenue by region, by type, and by application, allowing decision-makers to pinpoint where value creation is concentrated and where emerging pockets of demand are forming. Rather than exposing granular percentage splits in this preview, the full report delivers the precise regional revenue contributions and application-specific valuation profiles that procurement leaders, product managers, and investment analysts require to build robust market-entry or expansion strategies.
Competitive profiling within the study extends to a detailed examination of the top market participants, their strategic positioning, and the implications of recent innovations. The report evaluates how product launches from Sensirion, Bosch Sensortec, ScioSense, Renesas, Infineon, Amphenol, and Cubic Sensor and Instrument are reshaping performance expectations, power budgets, and form-factor constraints. By cross-referencing launch timelines with market demand signals, the analysis helps readers anticipate which corporate roadmaps will drive consolidation, which may open partnership opportunities, and where disruptor potential resides.
Additionally, the research integrates a critical assessment of industry dynamics, including tariff impacts, critical mineral supply risks, and environmental compliance cost trajectories. These factors are mapped against regional and segment-level demand profiles to identify the operating environments that will yield the most favorable risk-adjusted returns. The objective is to equip readers with a holistic view of the forces that will govern not only market size, but also profitability and long-term competitive resilience.
Positioning Your Organization for the Forecast Horizon
As the air quality sensor IC market advances toward the 2032 horizon, success will depend on the ability to interpret high-level growth signals with precision, align product roadmaps with evolving performance expectations, and navigate a supply environment that is increasingly sensitive to geopolitical and regulatory interventions. The structural expansion reflected in the forecast—a CAGR of 10.51 percent from 2026 through 2032—represents a meaningful opportunity, but it also intensifies competition for market share, talent, and preferred supply chain positioning.
This report is designed to convert that opportunity into executable strategy. By synthesizing historical performance, forward-looking projections, competitive intelligence, and macro-environmental analysis into a single cohesive narrative, it enables stakeholders to move beyond speculation and base their 2026 decisions on rigorously validated market intelligence. Whether the objective is to prioritize R&D investment, evaluate potential acquisition targets, optimize regional sales focus, or assess supply chain vulnerability, the study provides the structured insight necessary to act with confidence.
To access the complete segmentation data, full competitor profiles, detailed forecast tables, and region-specific strategic commentary, we invite you to consult the full Worldwide Air Quality Sensor ICs Market research report. The complete analysis delivers the granular revenue breakdowns, application-level valuation profiles, and competitive dynamics that will inform your most critical strategic choices throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Air Quality Sensor ICs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


