



Worldwide Tandem Rolling Mill Market: Why 3.7% CAGR and Asia Pacific Shift Strategy

Strategic Trends & Commercial Opportunities in the Worldwide Tandem Rolling Mill Market
Market Snapshot: Scale, Structure, and Core Challenges
The global tandem rolling mill market has entered a phase of steady, structurally supported expansion. Measured in USD millions, the sector has grown from a baseline of roughly 590 million in 2020 to just over 714 million in 2025, and forward indicators point to a consistent climb through 2032. The implied compound annual growth rate sits at approximately 3.7 percent, reflecting a market that is maturing rather than exploding. This trajectory is neither a cyclical surge nor a speculative boom; it is the result of long-lived capital investments in metal processing infrastructure, where replacement cycles, capacity modernization, and incremental efficiency upgrades compound over time.
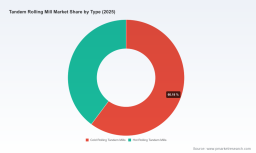
The market structure carries a distinctly concentrated character. A small cluster of global technology providers commands a majority share of high-value equipment sales, service contracts, and retrofit business. This concentration is not a barrier to entry so much as a reflection of the engineering complexity, process know-how, and after-sales ecosystem required to deliver mills that meet today's metallurgical specs. Customers are no longer purchasing standalone machinery; they are acquiring integrated process lines with embedded automation, flatness control, and energy management capabilities. As a result, the commercial value has shifted from hardware volume to performance assurance, uptime guarantees, and lifecycle optimization.
Three interlocking challenges define the current inflection point for operators, equipment builders, and investors.
- Raw material price volatility and margin pressure. Recent pricing data shows hot-rolled coil benchmarks in the U.S. Midwest reaching multi-quarter highs, while Northeast Asia spot prices have climbed on the back of automotive, shipbuilding, and construction demand. Elevated input costs compress downstream margins and force rolling mill operators to extract more throughput per unit of energy and labor. Mills that cannot deliver consistent gauge control, reduced rework, and faster line speeds face deteriorating economics, making modernization decisions less optional and more urgent.
- The precision-at-thinner-gauges dilemma. Demand for advanced high-strength steels, electrical steels, and specialty non-ferrous alloys is pushing processors toward tighter tolerances, thinner gauges, and more uniform property distribution. Traditional rolling configurations struggle to maintain shape, flatness, and thermal stability at these specifications without significant upgrades to automation, work roll selection, and closed-loop control. The challenge is technical, but the commercial consequence is clear: capacity that cannot hold spec loses premium contracts.
- Energy, emissions, and regulatory exposure. Rolling operations are energy-intensive, and the operational cost of reheating, rolling, and auxiliary systems is increasingly tied to carbon intensity and local enforcement regimes. Mills that continue to rely on legacy furnace and drive configurations face rising operating costs and potential compliance friction. Conversely, energy-efficient upgrades are moving from "nice-to-have" engineering projects to core components of plant economics and financing eligibility.
These challenges converge on a single strategic question: how to justify and sequence capital investment in a market where utilization, specification compliance, and energy cost are all moving targets. The answer increasingly lies in targeted modernization, process digitization, and selective capacity additions rather than blanket expansion.
Key Drivers Reshaping the Tandem Rolling Mill Market
The market's upward arc is not accidental; it is being pulled by a set of reinforcing drivers that reshape where value is created and how competitive advantage is earned. Four forces stand out.
1. Technology innovation shifting from mechanical throughput to process intelligence
The most consequential technical shift is the migration from mechanical stand-alone capability to integrated, closed-loop process systems. Tandem configurations are increasingly paired with advanced shape and flatness control, automated gap and tension regulation, and real-time thermal modeling. In steel, this translates into the ability to hold tighter tolerances on high-strength and thin-gauge products without sacrificing line speed. In aluminum and non-ferrous processing, it means more uniform properties across wider strips and better control of surface quality for automotive and packaging grades.
PW Consulting
Recent contract activity illustrates this direction. One global equipment supplier secured an order for a two-stand tandem cold rolling mill oriented toward automotive and can sheet production at a new facility in China, signaling that end-market specification requirements are steering equipment selection. In a separate modernization project, a major Japanese heavy section mill adopted compact cartridge mill stands and a tandem rolling mill control system for automatic gap control, an upgrade pattern that prioritizes responsiveness and precision over raw capacity addition. These are not isolated events; they reflect a broader preference for upgrades that improve controllability, reduce variability, and extend the useful life of existing assets.
2. Policy and regulatory pressure reshaping cost structures and procurement priorities
Regulatory and industrial policy environments are acting as both constraint and catalyst. On the constraint side, energy pricing, emissions expectations, and local content or sourcing requirements in certain regions are altering the economics of plant operation and equipment selection. On the catalyst side, the same pressures are accelerating demand for more efficient reheating, reduced thermal losses, and automation that lowers labor intensity and variability.
Industry reference material indicates that modern tandem rolling lines incorporating energy-efficient technologies such as regenerative burners in reheating furnaces can achieve average energy savings above 30 percent while reducing CO2 and NOx emissions. That magnitude of operational improvement changes the payback calculus for upgrades and makes energy performance a relevant criterion in vendor evaluation. In practice, this means policy and cost pressures are aligning: the mills that can demonstrate lower specific energy consumption and cleaner operation are better positioned to secure internal capital approval, favorable financing, and in some cases preferential consideration in regulated or semi-regulated procurement environments.
Worldwide Tandem Piston Compressors Market
3. Demand-side shifts toward advanced materials and application-specific specifications
On the demand side, the story is one of specialization. Steel processors are increasingly asked to deliver advanced high-strength grades, more consistent electrical steels, and narrower tolerance windows for automotive lightweighting and electrical applications. Aluminum and non-ferrous processors face similar pressure from automotive can-sheet, packaging, and specialty alloy requirements. In electrical steel applications, for instance, tandem cold rolling configurations are being specified with emphasis on high-precision automation, temperature modeling, and edge control to meet extremely thin gauges and uniform property demands.
This demand shift matters commercially because it rewards capability over capacity. A mill that can reliably deliver a premium specification earns a different revenue profile than one that competes primarily on tonnage. It also changes the upgrade logic: companies are more willing to invest in precision control, surface quality, and automation when those investments unlock access to higher-margin product mixes rather than merely increasing throughput of commoditized grades.
4. Supply chain and cost structure reconfiguration favoring selective modernization
Supply chain dynamics are reinforcing a preference for targeted investment. Steel input prices have exhibited notable swings, with U.S. Midwest hot-rolled coil benchmarks reaching levels that represent a significant year-over-year increase, while Northeast Asia prices have moved higher on demand from automotive, shipbuilding, and construction. When input costs rise, the operating leverage of a rolling operation depends heavily on yield, downtime, and energy efficiency.
That reality is pushing many operators away from greenfield expansion toward modernization that improves existing asset productivity. Retrofit programs that restore reliability, replace wear components, and upgrade control systems can deliver meaningful reductions in unplanned downtime and improve throughput consistency without the cost and lead-time burden of new greenfield capacity. A recent turnkey-style rehabilitation project in Italy, for example, focused on restoring reliability and reducing downtime in a tandem cold rolling mill by replacing key mechanical components. Projects of this nature reflect a market where extending asset life and stabilizing operations can be more commercially attractive than building new capacity from scratch.
Competitive Landscape and Leading Strategies
The competitive field is defined by a relatively small group of globally capable equipment and technology providers, each competing on a different combination of metallurgical expertise, automation depth, regional reach, and aftermarket support. Concentration in the market means that procurement decisions are often shaped by the perceived risk reduction, technical support coverage, and integration capability a vendor can offer, not only by headline equipment price.
Several strategic positioning patterns are visible among leading players.
- Integrated precision and automation as a differentiator. Some suppliers have built their reputation around continuous tandem cold mill solutions with advanced shape control, thickness uniformity, and automation systems, especially for electrical steel and high-precision applications. Their value proposition is less about brute-force capacity and more about repeatability, thin-gauge capability, and process stability. This is particularly relevant for customers whose product roadmap depends on meeting tighter specifications and accessing premium end markets.
- Broad-spectrum capability across ferrous and non-ferrous metals. Other leaders compete by offering a wide range of cold and tandem rolling solutions covering multiple strip widths, alloys, and configurations, including modular designs that combine rolling and forming units. This breadth allows them to serve diverse processor portfolios and to propose flexible equipment architectures that can adapt to changing product mixes. For customers with multi-metal operations or uncertain product strategies, that flexibility can be a decisive commercial advantage.
- Regional execution and aftermarket intensity. A further dimension of competition comes from suppliers with strong regional execution capability and deep aftermarket presence. Modernization, component replacement, and reliability-focused rehabilitation projects create recurring touchpoints with customers and build long-term service relationships. In concentrated markets, the ability to respond quickly with localized engineering support and spare-part logistics can be as important as the original equipment sale.
- Specialty configurations for demanding alloys. Some participants specialize in high-capacity, automation-driven tandem solutions with particular strengths in magnetic materials, stainless steel, and special alloys, using design choices such as small work roll diameters and large-stroke shifting to handle difficult processing requirements. This kind of specialization allows them to command position in niches where generic solutions underdeliver on metallurgy or control.
The landscape is evolving along three overlapping trends. First, differentiation is increasingly tied to digital control, energy performance, and specification compliance rather than to mechanical configuration alone. Second, the boundary between "new equipment" and "modernization" is blurring, as many contracts effectively extend the life and capability of installed bases rather than adding entirely new lines. Third, regional demand centers, especially in Asia, are generating a steady cadence of new orders and upgrade projects that reward suppliers with both global technology and local project execution. Taken together, these trends suggest a market where winners are those who can pair process technology with dependable service, and where the most attractive commercial opportunities often emerge in selective upgrades rather than indiscriminate expansion.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Looking ahead, several trends are likely to shape where growth concentrates and which capabilities command premium positioning.
- Continued selective modernization over blanket capacity addition. Given the maturity of the market and the cost of new greenfield builds, a meaningful share of investment will continue to flow toward retrofits, control-system upgrades, and reliability improvements. Expect more contracts focused on gap control, flatness optimization, automation, and component renewal. The commercial opportunity here lies in sequencing upgrades that unlock higher-margin products and reduce operating cost, rather than pursuing capacity additions that do not improve specification performance.
- Energy efficiency and emissions performance becoming procurement criteria. As energy costs and regulatory scrutiny remain salient, mills that can quantify and deliver energy savings, lower specific consumption, and reduced emissions will have an advantage in both internal approval processes and external competitiveness. Equipment and service offerings that integrate energy-efficient furnace technologies, optimized drive configurations, and process control that reduces waste are likely to see stronger demand, particularly where financing or compliance considerations are tied to efficiency outcomes.
- Premium specification capability as the route to margin differentiation. Demand for advanced high-strength steels, electrical steels, and specialty non-ferrous products is expected to keep pressure on processors to deliver thinner gauges, tighter tolerances, and more uniform properties. Providers that can demonstrate repeatable thin-gauge performance, advanced automation, and metallurgical process control will be better positioned to support customers moving up the value chain. The strategic implication is that capability upgrading and product-mix upgrading are increasingly two sides of the same investment decision.
These trends carry meaningful but manageable risks. Raw material price volatility can shift the urgency of upgrades and the affordability of capital projects. Regional demand cycles in automotive, construction, and shipbuilding can speed up or slow down order books. And the concentration of capable suppliers means that procurement negotiations often hinge on ecosystem support and integration risk, which can raise barriers for newer entrants attempting to compete on price alone. Still, the underlying direction is clear: value is migrating toward precision, efficiency, and reliability.
Strategic Implications and Action Steps for Decision-Makers
For manufacturers and processors, the near-term priority is to align capital planning with specification and efficiency outcomes rather than with tonnage targets alone. Targeted modernization that improves gauge control, reduces downtime, and lowers specific energy consumption can improve both margin resilience and access to premium product segments. Where new capacity is justified, it should be evaluated against the ability to hold tighter specs and to integrate efficiently with existing automation and material-handling systems.
For investors and strategic planners, the most durable opportunities are likely to be found in providers and projects that combine process technology with strong aftermarket and service economics. In concentrated markets, recurring service relationships, retrofit pipelines, and energy-performance-driven upgrades can offer more predictable value than pure equipment volume. It is also worth monitoring regional demand centers where new orders and modernization projects are accumulating, since execution capability and local support often determine long-term share dynamics.
Worldwide Steel Rolling Oils Market
For procurement and sourcing leaders, vendor evaluation should expand beyond baseline equipment cost to include controllability, automation depth, energy performance, and the credibility of the support ecosystem. In a market where specification risk and operating cost are both high, the cheapest initial price can be misleading if it comes with higher variability, more downtime, or weaker efficiency.
Because the market is shifting across technology, regulation, and demand simultaneously, decision-makers benefit from having detailed segmentation data, regional dynamics, and customized scenario analysis at hand before committing to capital or partnership choices. A comprehensive research report can provide the granular breakdowns, competitive benchmarking, and forward scenarios needed to translate these directional trends into concrete project prioritization and sourcing strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Tandem Rolling Mill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


