



Vein Finders Market to Hit $563.91M by 2032: The 11.51% CAGR Drivers

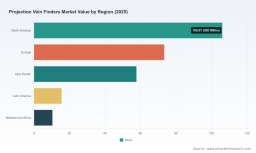
The Projection Vein Finders Market: Strategic Trends & Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
The global projection vein finders market has evolved from a niche clinical accessory into a mainstream capital equipment category, driven by steady demand for vascular access accuracy and procedural efficiency. Valued at approximately 263.2 million USD in 2025, the market is projected to expand to 563.91 million USD by 2032, reflecting a compound annual growth rate of 11.51 percent. This trajectory underscores a structural shift in how healthcare providers approach venipuncture, infusion, and diagnostic sampling—moving from anatomical palpation toward technology-assisted visualization that reduces failed attempts, patient discomfort, and clinician cognitive load.
The market's growth has not been linear. The period from 2020 through 2025 demonstrated a meaningful acceleration, with revenue climbing from 151.2 million USD to 263.2 million USD as procurement cycles normalized post-pandemic, hospital capital budgets reopened, and awareness of vascular access complications gained traction across clinical leadership. The forward-looking period from 2026 through 2032 points toward sustained expansion, with annual revenue expected to cross 400 million USD by the end of the decade. Such growth rates indicate that projection-based vein visualization is transitioning from early adopter enthusiasm to operational standard in many care settings.
Despite the favorable trajectory, several structural challenges are shaping the market's next phase. First, reimbursement fragmentation remains a persistent constraint. In many healthcare systems, there are no dedicated reimbursement codes for vein finder utilization, meaning acquisition and operating costs are typically absorbed as general capital or consumable expenditures rather than generating direct revenue streams. This dynamic forces procurement decisions to be justified primarily through workflow efficiency, complication reduction, and staff retention metrics rather than billable returns—a reality that compresses adoption timelines in price-sensitive environments and elevates the importance of total cost of ownership framing.
Second, the competitive and regulatory landscape is rewarding clinically differentiated engineering while pressuring undifferentiated hardware. Non-contact projection vein visualization systems are generally classified as Class 1 510(k) exempt devices in the United States and Class 1 devices in Europe, subject to general controls rather than premarket notification in many cases. In the European Union, however, compliance with the Medical Device Regulation (MDR 2017/745), including clinical evaluation, ISO 13485 quality management, and CE marking, remains a meaningful market access gate. The regulatory profile is comparatively accessible, but it also lowers barriers for new entrants, intensifying pressure on incumbents to demonstrate real-world differentiation beyond core near-infrared projection.
Third, end-user expectations are shifting from device presence to workflow integration. Hospitals increasingly include vein finders in tenders that specify rechargeable batteries, mounting stands, disposable sterile covers, and medical-grade components designed for seamless integration into vascular access procedures. Buyers are no longer evaluating standalone imaging performance alone; they are assessing bedside integration, infection prevention compatibility, staff training burden, and device ruggedness across diverse patient populations, including pediatric, dark-skinned, and scarred patients. This evolution is transforming procurement from a product purchase into a procedural enablement decision.
For executives and investors, the implication is clear: the market is large enough to reward scale, yet nuanced enough that value capture depends on execution quality, clinical relevance, and go-to-market discipline. Broad headline growth masks significant variation in segment attractiveness, procurement cycle intensity, and competitive intensity across geographies and application settings.
Key Drivers Powering Market Evolution
Several interconnected forces are shaping the direction of the projection vein finders market. Understanding which drivers are structural versus cyclical is essential for strategic planning, capital allocation, and capability building.
Technological innovation and imaging differentiation remain the most visible growth engine. The category is moving beyond basic near-infrared projection toward higher-resolution imaging engines, multi-color mapping, hands-free operation, and image fusion features that adapt to varying skin tones and vein conditions. Recent product activity illustrates this trajectory: AccuVein's launch of the AV600 next-generation near-infrared vein visualization device to U.S. customers in March 2026 introduced a 4x pixel count imaging engine and a sealed housing designed for infection prevention. This type of advancement matters because it simultaneously addresses two long-standing user pain points—image clarity for difficult access cases and device maintainability in infection-conscious environments. As imaging performance improves, the clinical value proposition expands from routine venipuncture assistance to more complex vascular access scenarios, broadening the addressable use cases within the same facility.
Policy, regulatory, and procurement frameworks are another critical driver, though they operate more as enablers and filters than as direct demand catalysts. The relatively accessible regulatory classification of most non-contact projection systems reduces time-to-market friction, but the burden of proof in procurement has increased. In the European Union, alignment with MDR 2017/745, clinical evaluation expectations, ISO 13485 quality management, and CE marking continues to shape which manufacturers can scale across regulated markets. In practice, this means that regulatory readiness is becoming a strategic moat: companies with mature quality systems and documented clinical evaluation pathways can expand faster and with lower compliance risk than those relying on reactive certification efforts. Meanwhile, procurement specifications are increasingly detailed. Tender documents such as those issued for medical vein visualization systems now commonly reference rechargeable batteries, stands or mounts, disposable sterile covers, and medical-grade components. These requirements elevate the importance of product ecosystem design and supplier reliability, not just device-level performance.
Demand-side behavioral shifts are reshaping where and how vein finders are deployed. Clinician and patient expectations around vascular access quality have risen, particularly in settings where repeated failed attempts carry operational and reputational costs. Hospitals and clinics are prioritizing tools that reduce puncture attempts, improve first-pass success, and support staff who manage high-volume vascular access workloads. At the same time, there is growing interest in point-of-care and decentralized settings, including emergency services and home care, where portability and ease of use can be decisive. This demand evolution is expanding the conversation beyond large inpatient departments into ambulatory, diagnostic, and field-adjacent care environments, each with distinct usability thresholds and procurement dynamics.
Supply-side and cost structure dynamics are also influencing competitive positioning. Manufacturers spanning the United States, China, and other production hubs are competing on multiple fronts: imaging quality, ergonomic design, multi-color projection modes, hands-free conversion, and pricing accessibility. Companies such as NextVein, Shenzhen Vivolight Medical Device & Technology Co., Ltd., ZD Medical Inc., HelloVein, and AimVein illustrate how product breadth is expanding across handheld and fixed-mount formats, with feature sets targeting affordability, customization across skin tones, and workflow flexibility. At the same time, established players like Christie Medical Holdings and Venoscope LLC continue to emphasize clinical heritage, patented near-infrared technology, and integration into provider networks. The resulting supply landscape is more pluralistic than in prior years, which benefits buyers through choice but also forces manufacturers to clarify defensible positioning rather than compete solely on specification sheets.
A notable demand-side catalyst is the role of procurement consortia and supplier agreements in widening access. Christie Medical Holdings' selection to exhibit VeinViewer at the Vizient Innovative Technology Exchange in August 2025, alongside expanded access through a Vizient provider agreement for vascular imaging solutions, highlights how distribution and group purchasing pathways can accelerate visibility and adoption among member hospitals. In healthcare markets where procurement is consolidated or influenced by shared sourcing networks, such relationships can materially affect competitive reach.
Taken together, these drivers suggest that the market's next growth wave will be won by organizations that align imaging innovation with procurement realities, regulatory readiness, and workflow integration. Technology alone is necessary but not sufficient; commercial execution around specification alignment, infection-prevention compatibility, and procurement narrative is increasingly decisive.
Worldwide LED Vein Finders Market
Competitive Landscape and Leading Strategies
The projection vein finders market features a mix of established clinical imaging specialists, regional manufacturing players, and increasingly agile entrants offering feature-rich handheld and fixed-mount solutions. Market concentration reflects meaningful but not insurmountable consolidation, with the top three players accounting for approximately 45.5 percent of revenue and the top five reaching roughly 62.3 percent. This concentration pattern indicates that scale and brand recognition matter, while still leaving substantial room for differentiated mid-tier and emerging competitors to capture specific use cases, geographies, or procurement segments.
Established U.S. players are leaning into imaging leadership, clinical heritage, and network-aligned distribution. AccuVein, Inc., operating from Medford, New York, has positioned itself around near-infrared projection vein visualization systems, most notably the AV600 and AV500, which project real-time superficial vasculature to improve venipuncture success. Its March 2026 introduction of the AV600 with a 4x pixel count imaging engine and sealed housing reflects a strategy centered on next-generation imaging fidelity and infection-prevention compatibility—two factors that resonate with procurement teams under pressure to reduce complications and support hygiene protocols. Christie Medical Holdings, Inc., based in Lake Mary, Florida, continues to emphasize its VeinViewer line, including the Vision2 advanced model with MaxReach and the portable Flex handheld, built on patented near-infrared technology for direct projection of vascular images onto skin. Christie's August 2025 participation in the Vizient Innovative Technology Exchange and associated provider agreement expansion points to a distribution and access strategy that leverages group purchasing visibility to broaden reach among member hospitals.
Mid-tier and emerging manufacturers are competing through affordability, feature breadth, and workflow flexibility. NextVein LLC offers the V800NV, a lightweight handheld digital system with multi-color projection modes that can convert to hands-free operation, positioned as an affordable high-performance alternative for vein visualization. This approach targets buyers who want advanced projection capability without premium pricing, particularly in settings where portability and multi-mode contrast are operationally valuable. Shenzhen Vivolight Medical Device & Technology Co., Ltd. manufactures the V800 series, including V800P and V800F, which project real-time vascular maps onto skin using near-infrared technology for clinical vein location. ZD Medical Inc., based in Hangzhou, produces portable medical projection infrared vein finders designed for real-time visualization, with support for difficult access cases such as pediatric, dark-skinned, or scarred patients—an explicit focus on clinically challenging populations that can differentiate a device in procurement evaluations.
Chinese and Asia-based entrants are expanding feature diversity and customization options. HelloVein develops AR and projection vein finders, including the Lite 2.0 and Max 3.0 models, with multi-color options, size adjustments, and image fusion features for venipuncture assistance. AimVein supplies projection vein finders such as the Pro 3.0, offering multi-color mapping with 10+ modes for customized contrast across skin tones and vein conditions. These product strategies reflect a broader trend: differentiation is increasingly defined by adaptive visualization, ergonomics, and user-configurable contrast rather than by projection capability alone. Meanwhile, Venoscope LLC and TransLite LLC / Veinlite continue to serve the market with devices using transillumination and projection technology for vascular access assistance, maintaining presence in segments where combined illumination approaches remain relevant.
PW Consulting
Strategically, the market is exhibiting both consolidation pressure and fragmentation potential. On one hand, larger players benefit from clinical credibility, established distribution relationships, and the ability to invest in next-generation imaging engines and sealed, infection-conscious housing designs. On the other hand, the relatively accessible regulatory classification of many non-contact projection systems lowers entry barriers, enabling new and regional manufacturers to introduce competitive hardware at varied price points. This dynamic creates a market where incumbents must continually raise the bar on image quality, workflow integration, and procurement-aligned feature sets, while newer entrants must prove durability, support infrastructure, and real-world reliability to progress from initial trials to repeatable purchasing.
A key evolution to watch is the shift from product competition to solution competition. Procurement is increasingly contextual: buyers evaluate devices alongside rechargeable batteries, stands or mounts, disposable sterile covers, and compatibility with vascular access workflows. Manufacturers that design for this broader ecosystem—and can articulate the operational benefits in procurement language—are better positioned to move beyond specification-based comparisons. Distribution relationships and group purchasing visibility, as illustrated by recent exhibition and agreement activity in the sector, are becoming important amplifiers of product merit, especially in concentrated procurement environments.
For market participants, the strategic question is not simply whether to compete, but where to position. Options include leading on imaging performance and infection-prevention design, competing on portability and affordability with strong feature sets, targeting difficult-access patient populations with specialized visualization, or building distribution alliances that expand access through institutional procurement channels. Each path carries different capital, operational, and competitive implications.
Vein Finder Market
Forward Outlook: Trends Shaping 2026–2032
Looking ahead, three interconnected trends are likely to define the projection vein finders market over the next three to five years.
First, imaging performance and adaptive visualization will become baseline expectations rather than differentiators. As higher-resolution imaging engines and multi-color projection modes become more common, the competitive center of gravity will shift toward application-specific usability, skin-tone adaptability, and workflow integration. Devices that can maintain clear projection across diverse patient populations and clinical settings will earn stronger repeat-use adoption, while those that perform well only in idealized conditions will face growing scrutiny. The commercial opportunity lies in pairing imaging advances with practical usability features—hands-free conversion, ergonomic form factors, and configuration flexibility—that make the technology easier to embed into daily practice.
Second, procurement-driven ecosystem requirements will increasingly shape product roadmaps. Buyers are specifying rechargeable batteries, mounting options, disposable sterile covers, and medical-grade components as part of the purchasing decision. This trend pushes manufacturers to think beyond the device unit and design for bedside integration, infection-prevention compatibility, and supply chain reliability. Companies that anticipate these requirements and align their offerings with tender language will gain an advantage in institutional procurement cycles. The risk is that manufacturers focused narrowly on hardware specifications may find themselves outpaced by competitors who offer a more complete procedural solution.
Third, distribution alliances and group purchasing pathways will play a larger role in market access. As procurement becomes more consolidated in certain regions and health systems, visibility through innovation exchanges and provider agreements can accelerate adoption independently of headline price competition. This does not eliminate the importance of product merit, but it does mean that go-to-market strategy—partner selection, clinical demonstration, and procurement narrative—will be as consequential as engineering quality. The opportunity for manufacturers is to build repeatable access channels; the risk is overreliance on a narrow set of relationships or underinvestment in clinical evidence and support infrastructure.
These trends carry inherent uncertainties. Reimbursement structures may evolve slowly, keeping acquisition decisions anchored in capital efficiency and operational outcomes rather than direct billing. Regulatory expectations in the European Union and other regulated markets will continue to require disciplined quality management and clinical documentation. Competitive entry remains relatively accessible, which could pressure margins unless differentiation is clearly established. Nonetheless, the underlying demand logic—better vascular access outcomes, reduced failed attempts, and improved clinician and patient experience—provides a durable foundation for continued growth.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to translate imaging and ergonomic strengths into procurement-ready value propositions. Product roadmaps should account for rechargeable power, mounting flexibility, sterile cover compatibility, and adaptive visualization across skin tones and difficult-access populations. Equally important is building clinical and quality-system credibility that supports expansion into regulated markets and institutional tenders. Differentiation will increasingly depend on workflow integration and supply reliability, not imaging claims alone.
For investors, the market's double-digit growth trajectory justifies attention, but value capture will be uneven. The most attractive opportunities lie with companies that combine defensible technology, repeatable procurement access, and disciplined cost structures, while also demonstrating readiness for regulatory and quality expectations in key regions. Due diligence should probe not only product features but also distribution alliances, tender adoption patterns, and post-sale support capability, since these factors often determine whether initial trials convert into sustained purchasing.
For procurement leaders and healthcare operators, the actionable focus is to evaluate vein finders as procedural enablement tools rather than standalone devices. Assessments should weigh first-pass success potential, compatibility with infection-prevention workflows, staff training burden, and total cost of ownership across battery replacement, sterile covers, mounts, and service. Where possible, procurement criteria should be aligned with the operational outcomes that matter most in the specific care setting, whether that is high-volume inpatient vascular access, ambulatory throughput, or point-of-care portability.
Detailed segment data, regional nuances, application-level dynamics, and customized scenario analysis can sharpen these decisions further. For decision-makers seeking a deeper, structured view of the market—including segmentation detail, competitive positioning, and procurement-aligned recommendations—the full PW Consulting report provides the supporting framework and granular intelligence needed to move from strategic direction to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Projection Vein Finders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


