



Worldwide Nervous System Medications: 7.12% CAGR Path to $222.6B

Navigating the Nervous System Medications Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
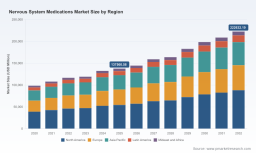
The global nervous system medications market has entered a phase of sustained expansion, with total revenue projected to climb from approximately $137.6 billion in 2025 to over $222 billion by 2032, reflecting a compound annual growth rate of 7.12 percent. This trajectory underscores a structural shift in how neurological and psychiatric conditions are diagnosed, treated, and managed across healthcare systems worldwide. The growth is not merely incremental; it signals deepening clinical reliance on targeted pharmacotherapies, expanding indication coverage, and increasing integration of nervous system treatments into broader chronic care pathways. As healthcare providers confront growing caseloads of neurodegenerative, psychiatric, and pain-related conditions, pharmaceutical stakeholders are recalibrating portfolios to capture value across both established and emerging therapeutic areas.
Despite the favorable macro trajectory, the sector faces several pivotal challenges that will shape competitive outcomes over the next decade. First, the tension between innovation and patent cliffs remains acute. Recent exclusivity losses on widely prescribed anti-epileptic and psychiatric agents have accelerated generic infiltration, compressing margins for originator manufacturers while simultaneously expanding affordable access for patients and payers. Second, reimbursement architectures are undergoing recalibration. Payers are increasingly scrutinizing real-world effectiveness, pharmacoeconomic outcomes, and differentiated clinical value, particularly for high-cost neurology therapies and specialty injectables. This environment rewards manufacturers that can demonstrate measurable health economic benefits rather than relying solely on clinical efficacy narratives. Third, supply chain dependencies continue to introduce volatility. The concentration of active pharmaceutical ingredient sourcing, particularly for complex nervous system compounds, across select contract manufacturing ecosystems has highlighted the need for geographic diversification, inventory resilience, and robust quality oversight. These dynamics collectively demand a more agile, data-informed approach to portfolio strategy, pricing, and market access.
PW Consulting
Key Drivers Shaping Market Evolution
Technological and scientific breakthroughs are redefining the therapeutic ceiling for nervous system disorders. The emergence of first-in-class mechanisms that target peripheral pain pathways without engaging opioid receptors illustrates a broader industry pivot toward safer, mechanism-driven interventions. Concurrently, advances in monoclonal antibody platforms and neurodegenerative disease modulation are expanding the treatment frontier for conditions historically considered difficult to modify pharmacologically. These scientific strides are enabling developers to pursue earlier intervention, more precise patient stratification, and formulations that improve adherence through reduced dosing frequency or alternative delivery routes. For commercial teams, the implication is clear: therapeutic differentiation increasingly hinges on mechanism novelty, convenience, and aligned diagnostic ecosystems rather than incremental efficacy gains alone.
Worldwide Sedative-Hypnotic Drug Market
Regulatory environments are simultaneously reshaping market entry and lifecycle management. Regulators have maintained a relatively active approval cadence, with notable clearances spanning acute pain management, advanced Parkinson’s motor fluctuation therapies, and expanded indications for neuroimmunological conditions. At the same time, agencies are embedding more nuanced post-market requirements, including genetic or biomarker-based testing considerations, pediatric expansion pathways, and real-world evidence expectations. These regulatory nuances create both opportunity and complexity. Companies that proactively design development programs with regulatory and market access requirements in mind are gaining faster, more defensible commercial launches, while those that treat approval as an endpoint rather than a commercial starting point risk under-monetizing valuable assets.
On the demand side, patient and provider behavior is evolving in ways that favor targeted CNS therapeutics. Growing awareness of mental health conditions, broader screening initiatives, and destigmatization efforts are expanding treatment-seeking behavior across psychiatric indications. In neurology, clinicians are increasingly prioritizing therapies that reduce caregiver burden, minimize administration friction, and support long-term disease management. This demand shift is particularly pronounced in outpatient and community care settings, where ease of use, tolerability, and predictable supply are decisive adoption factors. At the same time, healthcare systems are under pressure to control total cost of care, driving preference for treatments that can reduce hospitalizations, emergency interventions, or downstream complications.
Cost structure and supply dynamics complete the driver quartet. Nervous system product portfolios remain sensitive to raw material availability, specialty formulation requirements, and manufacturing scale-up timelines. Regional concentration in active ingredient production has created pockets of exposure, prompting manufacturers to reassess dual-sourcing strategies, technology transfer readiness, and inventory buffers. At the same time, the interplay between branded innovation and generic entry is restructuring profitability across drug classes. Market participants are increasingly balancing portfolio mix between protected innovation, lifecycle management, and generic or biosimilar positioning to sustain revenue resilience through competitive transitions.
Competitive Landscape and Leading Strategies
The competitive field in nervous system medications is characterized by a mix of large diversified pharmaceutical companies, focused neurology and psychiatry specialists, and generic manufacturers with substantial distribution reach. This structure creates a fragmented yet strategically layered environment where value capture depends on therapeutic focus, patent positioning, and market access execution. Leading players are not competing on the same axis; instead, they are differentiating through portfolio concentration, mechanism leadership, and lifecycle management agility.
Worldwide Central Nervous System (CNS) Stimulants Market
Several strategic patterns stand out among top competitors. Large diversified companies are leveraging neuroscience pipelines alongside broad commercial infrastructures to cross-sell into adjacent therapeutic areas and maintain payer relationships across multiple categories. Their advantage lies in scale, regulatory experience, and the ability to fund long-cycle neurodegenerative and neuroimmunological programs. Focused neurology and psychiatric specialists, by contrast, are pursuing sharper differentiation through niche indications, specialized delivery formats, and concentrated medical affairs engagement. These companies often move faster in targeted disease areas and build deep clinical credibility that supports premium positioning in specific segments. Generic and broad portfolio manufacturers continue to play a critical role in expanding access and managing cost pressure, particularly as exclusivity windows close on established products. Their strategic emphasis typically centers on supply reliability, formulation breadth, and competitive pricing across retail and institutional channels.
Recent commercial and regulatory activity illustrates how these strategies are unfolding in practice. The approval of a first-in-class non-opioid peripheral pain mechanism reflects the industry’s push to reduce opioid reliance while addressing acute pain with a differentiated pharmacological approach. In advanced Parkinson’s disease, new subcutaneous therapy options demonstrate continued investment in improving motor fluctuation management and patient convenience. Expanded indications in neuroimmunology and early symptomatic Alzheimer’s therapies highlight how incumbents are extending franchise value through lifecycle refinement and geographically staggered regulatory launches. At the same time, exclusivity changes affecting certain anti-epileptic and psychiatric agents are reshaping competitive intensity in those categories, forcing originators to plan for volume transitions and generic entrants to compete on distribution strength and cost efficiency.
The market structure is evolving along three interlocking trends. Consolidation remains relevant for players seeking scale in commercialization, supply chain control, or pipeline breadth, especially where therapeutic areas require sustained investment and multi-market execution. Differentiation is intensifying as mechanism innovation, delivery innovation, and diagnostic alignment become more central to market access conversations. New and emerging entrants are finding room in specialized indications, novel pain pathways, and psychiatric formulations where focused development can outperform broad but diffuse strategies. The result is a market in which strategic positioning matters as much as scientific merit: companies that clearly define the patient population, value proposition, and reimbursement narrative they are pursuing are better equipped to convert clinical progress into durable commercial outcomes.
Forward Outlook: Trends Defining the Next 3 to 5 Years
Looking ahead, one of the most consequential trends will be the continued shift toward mechanism-specific and non-opioid pain management strategies. As clinical and regulatory momentum builds around peripheral-targeted interventions, the acute and chronic pain segments are likely to experience a gradual but meaningful rebalancing away from traditional opioid-centric prescribing. Commercial winners in this space will be those that can pair differentiated pharmacology with clear safety positioning, practical dosing, and integration into surgical and emergency care pathways. A second major trend will be the broader adoption of neurodegenerative and neuroimmunological therapies as disease-management staples rather than niche options. With approvals and indication expansions advancing in conditions such as early symptomatic Alzheimer’s disease and generalized myasthenia gravis, neurological care is increasingly moving toward earlier diagnosis, biomarker-informed treatment selection, and longer-duration therapy management. This shift creates opportunities for manufacturers and service providers that can support diagnostic workflows, adherence infrastructure, and specialty distribution.
A third trend will be increasing segmentation within psychiatric and neurological prescribing driven by tolerability, administration preference, and health economic considerations. As payers and providers compare alternatives more rigorously, value will accrue to therapies that offer measurable advantages in adherence, side-effect profiles, or total cost-of-care impact. This environment favors portfolio strategies that are explicit about which clinical and economic problems they solve, rather than competing solely on broad category presence. At the same time, uncertainty persists. Patent expirations will continue to redraw competitive boundaries, reimbursement pressure may accelerate pricing negotiation and value-based contracting, and supply chain vulnerabilities could disrupt product availability if not proactively managed. Market participants should therefore treat resilience, evidence generation, and access strategy as core commercial capabilities rather than supporting functions.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to sharpen therapeutic positioning around clearly defined patient outcomes and access-enabling evidence. Investments in differentiated mechanisms, convenient delivery, and robust real-world data generation are likely to yield stronger launch momentum and more defensible pricing positions, especially in categories where generic competition and reimbursement scrutiny are intensifying. For investors, the most attractive opportunities will be found where scientific differentiation, regulatory timing, and market access readiness converge. Due diligence should focus not only on clinical promise but also on exclusivity windows, lifecycle planning, supply chain exposure, and the likelihood of reimbursement alignment in target markets. For procurement and supply chain leaders, the emphasis should shift toward multi-source readiness, demand forecasting for specialty nervous system products, and supplier diversification that reduces concentration risk without sacrificing quality or continuity.
Across all roles, the strategic value of granular market intelligence is rising. Broad category growth signals are useful for direction, but durable decisions depend on segment-level dynamics, competitive timing, regional access conditions, and product-level lifecycle trajectories. Stakeholders seeking to translate these trends into actionable portfolio, investment, or procurement decisions can benefit from deeper segmentation detail, competitive scenario mapping, and tailored market access analysis that aligns with specific strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Nervous System Medications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


