



Container Twistlock Market Shaping Shifts Beyond the 5.12% CAGR Story

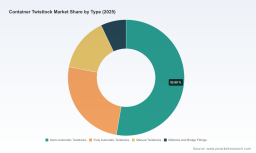
Strategic Trends and Commercial Opportunities in the Worldwide Container Twistlock Market
Market Landscape and Core Challenges
The global container twistlock market has established itself as a critical component of international trade infrastructure, enabling the secure stacking and transport of intermodal freight containers across maritime, rail, and road networks. Valued at approximately 585.4 million USD in 2025, the market reflects steady growth from its 2020 baseline of 451.3 million USD, driven by expanding global trade volumes and the ongoing modernization of logistics infrastructure. With a projected compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast period, the market is expected to reach roughly 830.34 million USD by 2032. This trajectory underscores the essential role of twistlock technology in maintaining the efficiency and safety of containerized cargo movement worldwide.
Despite this positive momentum, the industry is navigating several structural challenges that will define competitive dynamics in the coming years. One prominent tension lies in the coexistence of legacy manual systems alongside emerging automated alternatives. While manual and semi-automatic twistlocks continue to dominate procurement spending due to lower upfront costs and established supply chains, the accelerating electrification and automation of port operations are reshaping deployment priorities. Terminal operators and shipping lines are increasingly evaluating equipment that reduces manual intervention, minimizes occupational safety risks, and integrates with digital cargo management systems. This transition creates a bifurcation in procurement behavior, where cost-conscious operators in developing regions prioritize affordability, while advanced hubs invest in higher-capacity and remotely controlled solutions.
A second challenge centers on standardization and regulatory alignment across diverse operating environments. Function, dimensions, strength requirements, and testing protocols for twistlocks are governed by international specifications such as ISO 3874, which defines performance expectations for securing series 1 freight containers, and ISO 1161, which standardizes corner fittings geometry to ensure compatibility. Compliance with these standards is necessary but not sufficient for market access in specialized segments. Marine applications demand class society approvals from organizations such as ABS, DNV-GL, and CCS, while rail intermodal transport often requires AAR certification. The multiplicity of certification pathways complicates product development cycles, raises compliance costs, and creates barriers for smaller manufacturers seeking to expand into regulated segments. Companies that streamline certification strategies and align product portfolios with multiple standards gain a distinct advantage in penetrating high-value applications.
Supply chain and cost structure pressures represent a third critical juncture. Container twistlocks are primarily manufactured from high-strength forged or cast steel, making the category sensitive to fluctuations in metallurgical raw material pricing. With steel rebar futures trading at approximately 3103 CNY per ton in early 2026, manufacturers face ongoing input cost volatility that compresses margins and influences pricing strategies. At the same time, concentrated customer bases and long replacement cycles in maritime shipping mean that demand elasticity is relatively low in core segments. This dynamic forces producers to balance cost pass-through mechanisms with volume retention, particularly as logistics operators optimize total cost of ownership rather than focusing solely on unit price. The interaction between raw material economics, certification costs, and procurement cycles creates a complex environment where operational efficiency and product differentiation become decisive competitive levers.
Key Drivers Shaping Market Evolution
Technology innovation and the shift toward operational automation are restructuring how twistlocks are designed, deployed, and integrated into broader cargo handling ecosystems. The move toward electrification and remote control in twistlock systems reflects a broader industry ambition to reduce manual intervention, improve consistency in container securing, and enhance worker safety in demanding terminal environments. Recent product advancements illustrate this trajectory clearly. In November 2025, LOX Container Technology introduced its Road Gen 2 electrified fully retractable automatic clamping twistlock, which has been adopted in autonomous vehicle projects across Europe, North America, and Asia. This development signals that automatic twistlock technology is no longer confined to specialized pilot programs; it is entering operational use cases where interoperability with automated transport systems and reduced reliance on human handling are central requirements.
For manufacturers and equipment suppliers, this technological shift carries strategic implications. Fully automatic and semi-automatic solutions are gaining relevance not only in high-throughput container terminals but also in contexts where safety regulations, labor constraints, and throughput targets converge. The capability to offer remotely controlled, fully retractable designs that align with autonomous project specifications opens pathways to differentiated positioning. At the same time, the maturity of manual and semi-automatic product lines remains commercially significant, particularly where capital expenditure limits or operational models favor proven, lower-complexity equipment. The strategic opportunity lies in developing modular product architectures that allow customers to upgrade or adapt securing systems as automation adoption accelerates, rather than forcing a binary choice between legacy and advanced configurations.
Container Leasing Market
Policy and regulatory environments continue to shape market demand with direct consequences for product design and market access. ISO 3874 remains the foundational specification for function, dimensions, strength requirements, and testing of twistlocks, latchlocks, stacking fittings, and lashing systems used in securing series 1 freight containers. Complementing this, ISO 1161 standardizes corner fittings geometry, ensuring that twistlocks maintain compatibility across container fleets. These standards reduce fragmentation and create a baseline for interoperability, which benefits large-scale logistics operators seeking predictable performance across multiple ports and transport modes. However, the regulatory landscape extends beyond baseline compatibility. Marine applications require class society approvals, and railroad intermodal use often depends on AAR-certified components. These layered certification demands reward manufacturers that invest early in compliance infrastructure and maintain transparent documentation for end users and regulators.
Recent compliance-driven activity also indicates that standards are not static reference documents; they influence product refreshes and catalog positioning. In September 2025, various manufacturers maintained ongoing availability of ISO 3874-compliant manual, semi-automatic, and automatic twistlocks with updated strength requirements for container securing. This sustained alignment with recognized specifications suggests that compliance is becoming a market expectation rather than a differentiating feature alone. For market participants, the implication is clear: regulatory adherence must be embedded into engineering and quality processes, while differentiation is increasingly achieved through performance under load, durability, ease of maintenance, and compatibility with automated handling workflows.
Demand-side behavior is evolving as logistics operators reconsider total cost of ownership, safety performance, and throughput reliability. Containerized trade remains the backbone of global commerce, and the requirement to secure containers during stacking, vessel loading, and intermodal transfers generates consistent demand across maritime shipping, road and rail transport, and port terminals and storage. Yet procurement priorities are shifting. Terminal operators and fleet managers are placing greater weight on equipment that reduces manual handling risks and supports consistent securing performance across high-volume cycles. This preference is especially pronounced in segments where labor availability, training costs, and occupational safety considerations add operational pressure. Semi-automatic and fully automatic twistlocks address these concerns by standardizing engagement and disengagement processes, reducing variability introduced by manual operation, and supporting integration with digital tracking and monitoring systems.
Simultaneously, the market is witnessing demand segmentation based on application intensity and operating environment. High-cycle maritime shipping applications prioritize strength, reliability, and class society compliance, while road and rail transport segments focus on compatibility with chassis and inter-box connectors, alongside capacity ratings suited to specific load profiles. Port terminals and storage environments, meanwhile, value equipment that supports efficient stacking, quick turnaround, and safe handling in congested yard operations. This segmentation encourages manufacturers to refine product messaging and specification packages for distinct use cases rather than offering uniform solutions. Companies that map product capabilities to application-specific requirements and communicate the operational benefits clearly are better positioned to capture demand in targeted segments.
Supply chain and cost structure dynamics add another layer of complexity to market growth. Because twistlocks are manufactured primarily from high-strength forged or cast steel, input cost movements directly influence production economics. With steel rebar futures around 3103 CNY per ton in early 2026, manufacturers must navigate a cost environment where pricing discipline and efficiency in material utilization become critical. This is not solely a margin issue; it also affects product development decisions, inventory planning, and the commercial feasibility of specialized variants. In response, some producers are emphasizing yield optimization, forging and casting process improvements, and configuration strategies that balance performance with material intensity.
Hitch Lock Market
Beyond raw material considerations, supply chain resilience is increasingly valued by procurement teams. Global delivery expectations, strategic stocking locations, and the ability to support both loose and fixed lashing equipment requirements influence supplier selection. Logistics operators prefer partners that can maintain availability across key regions, reduce lead time variability, and support urgent replacement needs without compromising certification or quality standards. This environment rewards manufacturers and distributors that invest in multi-node inventory strategies and maintain transparent supply chain communication. It also creates differentiation opportunities for companies that can combine regional proximity with consistent compliance and technical support.
Competitive Landscape and Leading Strategies
The market features a diverse mix of established marine equipment manufacturers, regional producers, and specialists focused on automated or certified twistlock solutions. This diversity reflects the broad application base of the category, spanning maritime shipping, road and rail transport, and port terminals and storage. Rather than a single dominant model, competitive success depends on how effectively companies align product portfolios with certification needs, application intensity, regional availability, and increasingly, automation readiness.
PW Consulting
Several leading players demonstrate distinct strategic positioning. Pacific Marine & Industrial, based in California, offers manual, semi-automatic, and automatic container twistlocks, including AAR-approved railroad inter-box connectors and class society approved models for marine deck cargo securing. This breadth of certification coverage enables the company to address multiple regulated applications through a unified product strategy. Container Technics NV, headquartered in Antwerp, supplies certified twistlocks and stackers for container vessels and ConRo ships, with strategic stock positioned in Antwerp, Dubai, Houston, and Shanghai for worldwide delivery of loose and fixed lashing equipment. Its regional inventory footprint supports responsiveness and reduces delivery friction for global customers.
General Lashing System Co., Ltd. in Ningbo manufactures twistlocks designed for deck and hatch cover installation, including semi-automatic models with large seat variants for marine shipping cargo securing. This application-oriented specialization illustrates how design focus on specific installation contexts can create a defensible position in marine securing segments. Shanghai Metal Corporation produces a broad range of twistlocks, including semi-automatic, fully automatic, dovetail, and manual types for shipping applications, reflecting a portfolio approach that targets varied customer preferences and budget profiles. Zava Marine Corporation supplies durable manual twistlocks meeting stringent safety standards for shipbuilders, shipowners, and offshore operators, emphasizing reliability and compliance in demanding marine environments.
Additional participants illustrate further strategic angles. SEC Ship's Equipment Centre Bremen GmbH & Co. KG is a leading manufacturer of container lashing equipment, including twistlocks, serving global ports and reinforcing the importance of established distribution and service reach. TEC Container operates as an OEM supplier of container lashing gear and handling equipment, including twistlocks, highlighting the relevance of manufacturing partnerships and integrated equipment offerings. Delta Mark, based in the USA, supplies semi-automatic and manual shipping container twistlocks, including AAR-approved models with up to 50-ton capacity for rail, ships, and trucks, demonstrating how capacity ratings and rail certification can support position in intermodal transport.
Automation-focused differentiation is also increasingly visible. LOX Container Technology, with a Europe-focused automation orientation and global reach, specializes in remotely controlled, electrified, fully retractable automatic twistlocks for autonomous vehicle projects and container securing, reducing manual handling. This focus points to a strategic direction in which technological integration and automation compatibility become core value propositions rather than optional features. In India, International Trailer & Parts manufactures retractable, non-retractable, screw, handle, casted, welded, and forged twistlocks and spare parts for trailer container chassis, reflecting a broad component and parts orientation that supports regional fleet and trailer ecosystems. NDRAGOLD in Jalandhar produces high-quality twistlocks with compact design for export markets, while Karma Steels manufactures forged container spreader twistlocks and guide assemblies, showing how specialized forging capabilities can support specific handling configurations. CIE Manufacturing provides twistlocks as part of intermodal chassis technology for secure container transport across modes, emphasizing integration within broader transport equipment rather than standalone component sales. ILS in Belgium supplies left and right-handed longitudinal U-frame twistlocks with high BLS ratings for container vessels, and MacGregor, part of the Cargotec group in Sweden, offers integrated cargo handling systems including advanced twistlocks with emphasis on safety and efficiency for marine applications, reinforcing the value of system-level solutions and maritime engineering credibility.
The competitive landscape is evolving through a combination of differentiation and selective consolidation pressure. On one side, product differentiation is intensifying around certification breadth, material and manufacturing quality, capacity ratings, automation readiness, and regional service availability. Companies that can demonstrate compliance with ISO 3874 and ISO 1161, secure class society or AAR approvals where required, and support automated or electrified deployment models are better positioned to command preference in higher-value segments. On the other side, the market structure encourages consolidation of supply chain value in certain channels, particularly where customers prioritize vendor reliability, multi-region stock availability, and integrated lashing solutions over purely price-based sourcing.
New entry and expansion dynamics are also shaping the field. Lower-cost manufacturing bases continue to support competitive offerings in manual and semi-automatic categories, especially where export-oriented design, compact form factors, and quality consistency meet international expectations. At the same time, automation-linked innovation is raising the barrier for entry in advanced segments, where engineering complexity, certification timelines, and integration with autonomous or electrified systems require sustained investment. This creates a market environment in which incumbents with strong certification records, established distribution networks, and clear automation roadmaps can strengthen their position, while nimble regional players can thrive by focusing on specific applications, parts supply, or cost-efficient product lines.
Future Outlook and Emerging Opportunities
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, automation and remote-controlled twistlock systems will move from selective deployment to broader operational relevance, particularly in terminals and logistics projects that prioritize safety, throughput consistency, and reduced manual handling. Electrified, fully retractable designs suitable for autonomous vehicle projects and automated securing workflows are expected to gain incremental adoption where capital investment and infrastructure readiness align. This trend opens opportunities for manufacturers that can deliver reliable automatic solutions, support integration with terminal control systems, and demonstrate measurable operational benefits.
Second, certification and standards alignment will remain central to market access, but the commercial emphasis will increasingly shift toward demonstrating performance under real operating conditions. As ISO 3874 and ISO 1161 continue to provide the baseline for function, dimensions, strength requirements, and testing, companies that combine compliance with strong load retention, durability, and ease of maintenance will stand out. Class society approvals and AAR certification will continue to gate participation in marine and rail intermodal segments, making early and efficient certification strategy a competitive asset rather than a back-office task.
Third, cost pressure from steel raw materials and the need for supply chain resilience will reinforce the value of efficient manufacturing, strategic inventory positioning, and transparent sourcing. With input costs influenced by prices such as the approximately 3103 CNY per ton steel rebar futures level observed in early 2026, producers will continue to optimize material usage, forging and casting processes, and product configurations that balance performance with cost. Customers will increasingly favor suppliers that can maintain availability across regions, support urgent replacement needs, and reduce total cost of ownership through reliability and service responsiveness.
These trends create commercial opportunities for manufacturers that can bridge traditional robustness with automation readiness, for investors evaluating companies with strong certification portfolios and regional distribution advantages, and for procurement teams seeking suppliers that reduce operational risk while meeting evolving technical requirements. At the same time, uncertainty remains. Adoption of fully automatic systems may proceed more slowly in cost-sensitive regions, certification requirements may evolve as operating practices change, and raw material volatility can disrupt margin planning and pricing stability. Companies that treat these uncertainties as design constraints rather than external noise will be better prepared to capture value as the market matures.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to align product development with both compliance rigor and automation trajectory. This means maintaining clear adherence to ISO 3874 and ISO 1161, pursuing class society and AAR approvals where relevant, and developing product variants that support remote control, electrification, and integration with automated securing workflows. Equally important is building regional availability and aftermarket support, since responsiveness and parts supply often influence repeat procurement as much as initial price.
For investors, the most compelling signals are certification breadth, application-specific engineering strength, regional distribution capability, and credible roadmaps for semi-automatic and fully automatic solutions. Businesses that combine these attributes with disciplined material cost management and multi-region stock positioning are better equipped to navigate segmented demand and regulatory complexity. Investment diligence should therefore weigh not only unit economics but also the ability to serve marine, rail, and terminal applications reliably under varying operating conditions.
For procurement and logistics operators, the strategic focus should be on total cost of ownership, safety performance, and compatibility with current and near-term handling requirements. Evaluating suppliers on certification coverage, capacity ratings, maintenance burden, and availability across key locations can reduce operational risk and support smoother integration with automated or semi-automated processes. As deployment scenarios mature, access to detailed segment-level data and customized guidance can help refine specification choices and sourcing strategies. For those seeking a more granular view of regional splits, application demand patterns, type-level dynamics, and company-level positioning, the full PW Consulting market study offers expanded segmentation detail and tailored strategic recommendations to support planning decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Container Twistlock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


